What is the baseline valuation and scope of the Continuous Casting Machine Market?
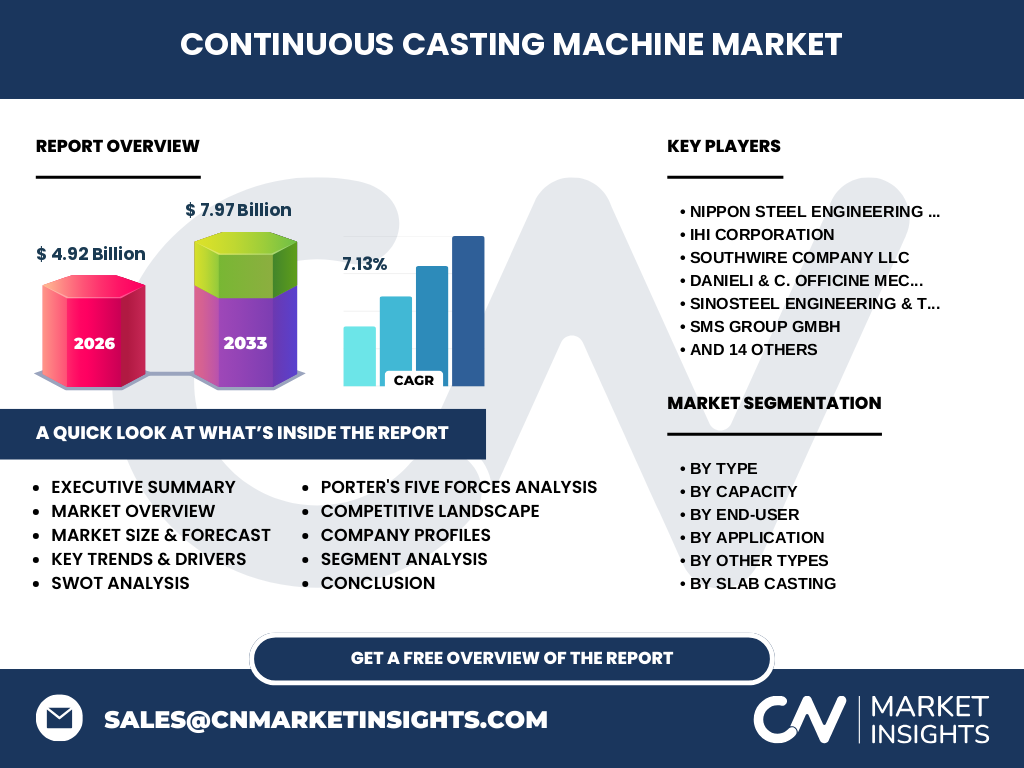
Our analysis indicates the Continuous Casting Machine Market reached $4.92 Billion in 2026. This foundational sector encompasses heavy industrial machinery required to solidify molten steel, copper, and aluminum into semi-finished shapes like billets, blooms, and slabs, serving as the literal backbone of modern metallurgical processing.
Structural Growth Drivers and Market Restraints
The market is propelled by a 7.13% CAGR driven by surging infrastructure demands, countered by the high capital expenditure required for advanced metallurgical refits. Stringent environmental mandates by regulatory bodies like the World Steel Association pressure mills to adopt energy-efficient casting lines.
Emerging Industry Trends and Transformation Patterns
Industry trends highlight a rapid pivot toward near-net-shape casting and digital twin integration. Mills increasingly rely on Primetals Technologies Limited and SMS group GmbH to supply intelligent automation that minimizes energy loss during high-speed billet and thin slab production.
Pandemic Aftershocks and COVID-19 Impact Analysis
The pandemic severely disrupted global supply chains for heavy steelmaking components, causing temporary halts in port logistics across Antwerp and Shanghai. However, post-pandemic economic stimulus packages aggressively revived construction, accelerating market recovery toward projected 2027 figures.
Competitive Benchmarking and Industry Concentration
The landscape features high concentration among elite engineering houses. Market leaders like Danieli & C. Officine Meccaniche S.p.A. and Nippon Steel Engineering Co. Ltd. leverage proprietary curved mold and multi-strand technologies to dominate global mill contracts against regional players.
Executive Summary of the Continuous Casting Machine Market
Our comprehensive report reveals a robust market trajectory, scaling from $4.92 Billion in 2026 to $7.97 Billion by 2033. Strategic investments in thin slab and multi-strand bloom casters represent the highest-yield opportunities for global metallurgical equipment manufacturers.
What is the long-term market forecast for the Continuous Casting Machine Market from 2027 to 2033?
The market is projected to expand robustly, reaching $7.97 Billion by 2033 at a steady 7.13% CAGR. This expansion is heavily underpinned by surging demand for high-grade structural beam blanks and specialized strip casting equipment across emerging industrial economies.
Granular Segmentation Analysis of Casting Technologies
Segmentation is categorized by type (billet, bloom, slab, beam blank), capacity, end-user (foundries, metallurgical plants), and application (steel, copper, aluminum). Slab casting dominates volume, while specialized beam blank units command premium margins in structural engineering applications.
Geographic Distribution and Regional Market Performance
Asia-Pacific commands the lion's share of installations, anchored by massive steel hubs in China and India. Meanwhile, European markets focus on greenfield decarbonization upgrades, driven by stringent EU carbon border adjustment mechanisms impacting traditional blast furnace routes.
In-Depth Regional Review of Production Hubs
North American operations prioritize automation retrofits to combat localized labor constraints, utilizing advanced machinery from suppliers like Hazelett Corporation. Conversely, Asian markets continue constructing massive greenfield multi-strand slab and billet facilities near major coastal ports.
Strategic Positioning in Company Profiles
Industry titans such as Tenova S.p.A., IHI Corporation, and Inductotherm Group Inc. differentiate themselves through proprietary electromagnetic stirring and advanced metallurgical modeling. Their strategic focus remains on reducing carbon footprints via hydrogen-ready casting innovations.
Porter's Five Forces Assessment of Competitive Dynamics
Supplier power remains moderate due to specialized metallurgy requirements, while buyer power is high given the multi-million-dollar capital outlays involved. Threat of substitutes is remarkably low, as continuous casting remains fundamentally irreplaceable for mass metal solidification.
SWOT Analysis of the Continuous Casting Machine Industry
Key strengths include high operational efficiency and technological maturity, offset by weaknesses like massive upfront capital costs. Opportunities abound in near-net-shape innovations, though threats from volatile raw material pricing and tightening environmental regulations persist.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from alloy refiners and raw steel producers to specialized machine fabricators like Sinosteel Engineering & Technology Co. Ltd. and ultimately to automotive and construction end-users requiring precision-cast structural profiles.
High-Potential Investment Insights and Strategic Recommendations
Investors should target developers of thin slab and strip continuous casting machines, as these technologies offer superior energy yields. Partnerships with firms specializing in zero-emission electric arc furnace integration represent optimal avenues for long-term equity growth.
Conclusion and Definitive Industry Takeaways
The continuous casting sector stands at an inflection point of technological modernization. Reaching $7.97 Billion by 2033 demands that equipment manufacturers aggressively incorporate digital automation and sustainable metallurgy practices into their core offerings.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing global trade registry data, primary executive interviews with engineering heads at firms like Sarralle Group, and secondary macroeconomic indicators from the World Bank and International Iron and Steel Institute.
Scope of the Report and Analytical Parameters
This report covers global deployment data across steel, copper, and aluminum applications from 2026 to 2033. Limitations exclude micro-foundries operating legacy ingot molds outside of industrialized commercial output metrics.
Recent Strategic Developments and Corporate Partnerships
Recent months saw major joint ventures focused on digital twin integration, with firms like Continuus-Properzi S.p.A. and Retech Systems LLC announcing advanced alloy casting trials aimed at aerospace and specialized industrial applications.