Market overview and structural significance of the Vending Machine Operators Market
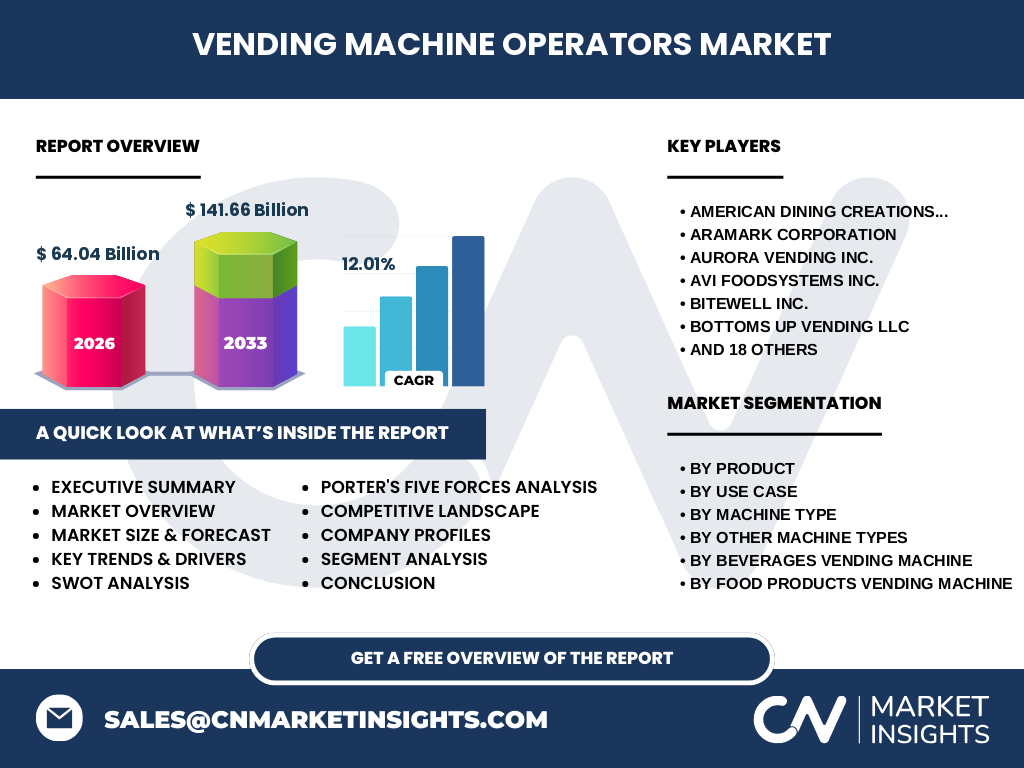
The Vending Machine Operators Market reaches a foundational valuation of 64.04 Billion in 2026, driven by unattended retail transformation. Our analysis indicates operators manage critical cold chain logistics, raw food sourcing, and telemetry integration across corporate and retail channels.
What are the primary growth drivers and market restraints shaping the industry?
Labor shortages and contactless payment demands act as primary catalysts. Conversely, regulatory compliance regarding nutritional labeling by bodies like the FDA restrains deployment speed. Operators must balance supply chain volatility with automated asset management.
Emerging trends and digital transformation patterns in the sector
The shift toward smart telemetry and biometric payment systems redefines operator efficiency. Real-time inventory tracking for perishable items minimizes spoilage, directly improving operational margins for companies managing complex supply routes.
COVID-19 impact analysis and subsequent recovery trajectory
Pandemic-era office closures severely disrupted transit and corporate segments. However, the recovery trajectory showcases accelerated adoption of contactless hygiene-focused interfaces and micro-market conversions in high-density corporate offices.
Competitive landscape and market consolidation dynamics
Industry leadership is consolidated among major players like Aramark Corporation, Compass Group USA Inc., and Selecta Group B.V. These giants leverage massive scale for purchasing power, route optimization, and proprietary cashless infrastructure deployment.
Executive summary of key analytical findings
Our comprehensive research projects the Vending Machine Operators Market to surge from 64.04 Billion in 2026 to 141.66 Billion by 2033, representing a robust 12.01% CAGR fueled by unattended retail innovations.
Market forecast trajectory from 2027 to 2033
Accelerated expansion between 2027 and 2033 will push the market to 141.66 Billion at a 12.01% CAGR. This trajectory relies on smart machine adoption and diversified product offerings spanning fresh food and personal care.
Segmentation analysis across product, use case, and machine categories
Segmentation spans product lines like soft drinks and hot meals, use cases including corporate offices and transit hubs, and hardware like fresh food and healthcare units. Each segment demands tailored supply chain protocols and specialized logistics.
Geographic distribution and regional performance metrics
Regional performance varies based on labor costs and urban density. North America dominates early tech adoption, while Europe emphasizes energy-efficient refrigeration units complying with strict environmental directives.
In-depth regional review of high-density metropolitan markets
Metropolitan centers in North America and Western Europe drive heavy volume due to high foot traffic in transit hubs. Operators here prioritize rapid restocking schedules and dynamic pricing algorithms to maximize revenue per square foot.
Strategic positioning of leading corporate profiles
Industry stalwarts like PepsiCo Inc. and The Coca-Cola Company integrate vertical product supply with direct operator networks. Specialized operators like AVI Foodsystems Inc. focus on bespoke regional foodservice offerings.
Porter's Five Forces competitive assessment
Supplier power remains moderate due to consolidated beverage manufacturers, while buyer power is high in corporate contracts. Threat of substitution from traditional retail is mitigated by the unmatched convenience of unattended placement.
SWOT analysis of the operational ecosystem
Strengths lie in established route networks and cashless infrastructure. Weaknesses involve high hardware maintenance costs. Opportunities emerge in healthcare vending, while threats include vandalism and raw ingredient price inflation.
Value chain analysis from raw materials to end-users
The value chain flows from raw food and beverage producers through equipment manufacturers like Royal Vendors Inc. and SandenVendo America Inc., culminating in operator route logistics and end-user contactless purchase points.
Strategic investment insights and high-potential areas
Investors should target operators integrating IoT telemetry and fresh-food capabilities. Companies partnering with innovators like Bitewell Inc. capture high-margin healthy eating demographics within corporate office spaces.
Conclusion and critical industry takeaways
The Vending Machine Operators Market transitions from a coin-operated utility to a digital, data-driven retail channel. Achieving a 12.01% CAGR requires strategic technology investment and disciplined route optimization.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by combining trade registry data, primary executive interviews with operators like Canteen Vending Services Inc., and secondary macroeconomic indicators regarding retail foot traffic.
Scope of the report and analytical coverage parameters
This report covers global operational dynamics, hardware manufacturing, and product categorization through 2033. Excluded from primary scope are independent micro-retail setups lacking automated telemetry infrastructure.
Recent developments, partnerships, and strategic moves
Recent market activity highlights strategic mergers and cashless rollout partnerships. Industry participants actively deploy advanced telemetry from suppliers like Azkoyen Group to streamline preventative maintenance and route restocking.