What is the baseline market scope and valuation of the Coworking Space Management Software Market?
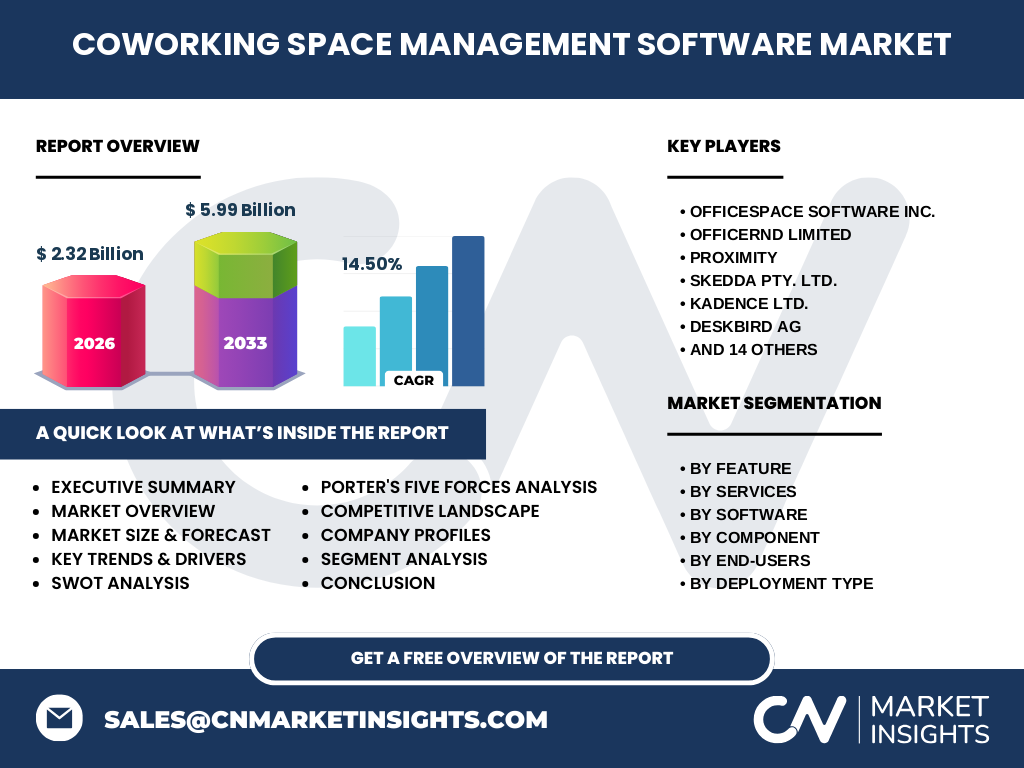
Our analysis indicates that the Coworking Space Management Software Market market size stands at 2.32 Billion in 2026. This valuation reflects the critical infrastructure required to manage flexible workspaces, automate billing, and coordinate facility operations across global business hubs.
What are the primary structural growth drivers, restraints, and opportunities shaping the Coworking Space Management Software Market industry trends?
The market is propelled by hybrid work adoption, though data privacy compliance acts as a persistent restraint. Enterprise demand for flexible leasing presents a multi-billion dollar expansion opportunity for vendors integrating IoT access control.
How are emerging trends reshaping operational paradigms in the Coworking Space Management Software Market analysis?
The shift toward AI-driven space utilization analytics is redefining tenant management. Platforms offering automated community engagement and mobile access are capturing disproportionate market share as operators prioritize touchless, data-backed environments.
What was the lingering COVID-19 impact trajectory on the Coworking Space Management Software Market?
While pandemic lockdowns initially contracted flexible office footprints, the subsequent recovery accelerated digital transformation. Operators rapidly adopted cloud-based solutions to manage decentralized scheduling and enforce occupancy limits, permanently altering the software adoption curve.
How is the competitive landscape characterized among major ecosystem participants?
The market features intense competition between agile innovators like OfficeRnD Limited, Cobot, and established enterprise players. Strategic consolidation is rising as vendors acquire advanced mobile access capabilities to secure end-to-end platform dominance.
Executive Summary: High-Level Synthesis of Market Dynamics
Driven by a robust 14.50% CAGR, the ecosystem is transitioning from basic booking tools to comprehensive operational suites. Vendors embedding advanced CRM and automated billing modules are best positioned to capture enterprise-grade contracts.
What is the trajectory of the Coworking Space Management Software Market forecast through 2033?
The market is projected to surge from 2.32 Billion in 2026 to reach 5.99 Billion by 2033. This expansion is underpinned by relentless corporate demand for decentralized workspaces and agile real estate management solutions.
How do segmentation vectors dictate product development and deployment strategies?
Segmentation spans deployment types, components, features, services, software types, and end-users. Cloud-based deployment dominates due to scalability, while specialized modules for billing, CRM, and facility management drive software differentiation.
Regional Market Analysis and Geographic Distribution Patterns
North America leads consumption due to early adoption of hybrid work models, while Europe follows closely driven by stringent data localization requirements. Asia-Pacific represents the fastest-growing frontier fueled by rapid urbanization and startup hubs.
An In-Depth Regional Review of Enterprise Flexible Workspace Adoption
Metropolitan hubs in North America and Western Europe demonstrate high software saturation, demanding deep API integrations with enterprise HR tools. Conversely, emerging markets show higher demand for turnkey, mobile-first booking and billing solutions.
Strategic Positioning of Leading Companies in the Ecosystem
Firms like OfficeSpace Software Inc. and Nexudus Ltd. target enterprise facility integration, whereas specialized players like Skedda Pty. Ltd. and deskbird AG focus on frictionless, self-service booking experiences for mid-market operators.
Porter's Five Forces Analysis of Competitive Intensity
Competitive rivalry is high due to low switching costs among basic booking tools. However, supplier power remains moderate, while the threat of substitution is tempered by the specialized complexity of enterprise billing and IoT hardware integration.
SWOT Analysis: Evaluating Internal Capabilities and Market Realities
Strengths lie in robust automation features, while weaknesses involve integration friction with legacy real estate hardware. Opportunities in enterprise hybrid policies heavily outweigh threats from macroeconomic volatility and tightening data security regulations.
Value Chain Analysis from Software Development to End-User Deployment
The value chain flows from cloud infrastructure providers and API developers to software vendors, specialized implementation partners, and finally end-user enterprises. Integration and consulting services capture significant margin during deployment phases.
High-Potential Investment Insights and Strategic Recommendations
Investors should target platforms offering native IoT access control integration and predictive analytics. B2B enterprise migration represents the most lucrative segment, favoring vendors with robust security compliance certifications.
Conclusion and Strategic Takeaways for Industry Stakeholders
Achieving scale in this market requires transcending basic scheduling functionality to deliver unified, data-driven workplace ecosystems. Proprietary analytics and seamless API connectivity will separate market leaders from legacy participants.
Research Methodology and Baseline Data Triangulation
Our baseline estimates are triangulated by combining proprietary trade registry data, primary stakeholder interviews with workspace operators, and secondary macroeconomic indicators regarding commercial real estate absorption rates.
Scope of the Report and Analytical Parameters
This report covers global software deployments across dedicated coworking spaces, enterprise hubs, and business centers from 2026 to 2033. Hardware-exclusive access control systems are excluded except where integrated directly with management platforms.
Recent Developments, Strategic Partnerships, and Product Launches
Recent market activity highlights aggressive R&D investment in AI-powered space optimization and strategic acquisitions of mobile access startups. Industry leaders are actively forging alliances with commercial real estate giants to secure enterprise distribution channels.