What is the scope and industry significance of the Steel Strapping Market?
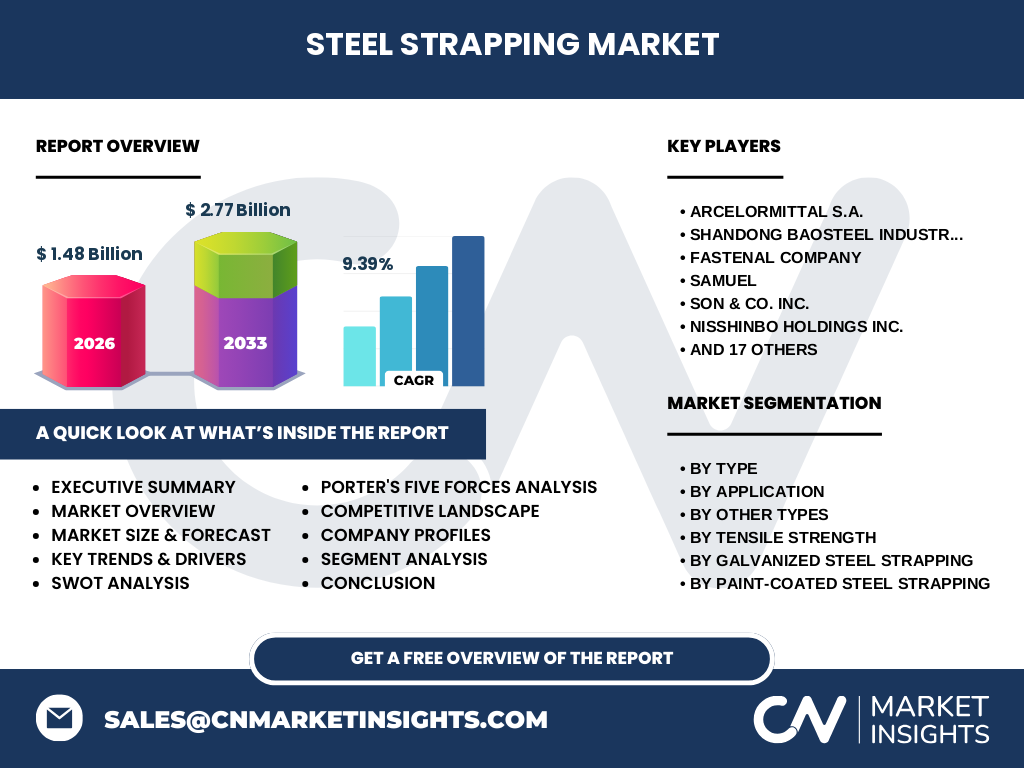
Our analysis indicates that the Steel Strapping Market represents a foundational pillar for heavy industrial packaging, securing a valuation of 1.48 Billion in 2026. This sector is critical for securing heavy-duty shipments of metals, timber, and construction materials across global supply chains. Regulatory bodies such as the AAR (Association of American Railroads) mandate strict tensile performance standards for transit compliance.
Key market drivers, restraints, challenges, and opportunities shaping Steel Strapping Market
Growth is propelled by surging infrastructure spending and heavy manufacturing demands. However, raw material volatility in hot-rolled and cold-rolled coils creates margin pressures. Opportunities lie in expanding high-tensile and specialized corrosion-resistant variants that withstand severe logistical hurdles at major global shipping hubs.
Emerging trends and growth patterns in Steel Strapping Market
The shift toward advanced Paint-Coated Steel Strapping, specifically polyester and polypropylene variations, is accelerating. These coatings prevent atmospheric oxidation and rust during maritime transit, outperforming legacy bare metal alternatives in humid trade lanes.
How did the COVID-19 pandemic impact the Steel Strapping Market and recovery trajectory?
Pandemic-era supply chain bottlenecks severely disrupted slab steel allocation and logistics channels. Recovery has been robust, driven by post-pandemic infrastructure stimulus packages globally, leading directly to the projected market expansion to 2.77 Billion by 2033.
Competitive benchmarking and strategic dynamics in the industry
The landscape features a mix of multinational conglomerates and specialized regional producers. Industry leaders like Signode, ArcelorMittal S.A., and Samuel, Son & Co. Inc. leverage integrated steel supply chains to maintain competitive pricing and secure high-volume supply contracts.
Executive Summary
The Steel Strapping Market industry trends reveal a high-growth trajectory, expanding at a robust CAGR of 9.39% from 2027 to 2033. Strategic investments in automated packaging lines and high-tensile metallurgical formulations are essential for capturing high-margin industrial accounts.
Market forecast from 2027 to 2033
Driven by expanding industrial output in developing economies, the market is poised to scale from its 2026 baseline to 2.77 Billion by 2033. This trajectory reflects a sustained compound annual growth rate of 9.39% over the forecast horizon.
Segmentation analysis across product types and applications
The market segments by type into Blue-Tempered, Paint-Coated, Galvanized, and Other Types. Application verticals include metal, paper, glass, building, and other sectors. Tensile strength categories are split between Regular Duty and High Tensile, catering to diverse load-bearing requirements.
Regional market analysis and geographic distribution
Geographic performance is heavily anchored by heavy manufacturing hubs in Asia-Pacific, North America, and Europe. Localized constraints, such as stringent European packaging waste directives and North American rail transit regulations, dictate regional product adoption patterns.
In-depth regional review of high-performance territories
Asia-Pacific dominates consumption due to massive steel production and fabrication activities in China, supported by key regional entities like Shandong Baosteel Industry Co. Ltd. and Tianjin Hongmei Steel Strips Co. Ltd. Meanwhile, North American demand relies on heavy-duty transit networks.
Company profiles and strategic positioning
Prominent players such as Fromm Holding, Acme Steel Co., and Fastenal Company focus on direct distribution and proprietary strapping tool ecosystems. Their strategic positioning emphasizes end-to-end packaging solutions rather than commoditized strap sales.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate to high, dictated by raw steel feedstock availability from giants like ArcelorMittal S.A. Competitive rivalry is intense, compelling manufacturers to innovate through specialized coatings like electro-galvanized and hot-dip galvanized variants.
SWOT analysis of the global sector
Strengths include unmatched tensile durability for heavy loads. Weaknesses involve high sensitivity to steel pricing fluctuations. Opportunities emerge in automated secondary packaging, while threats stem from substitution risks posed by heavy-duty synthetic composite straps.
Value chain analysis from raw materials to end-users
The value chain initiates with iron ore extraction and primary steelmaking by mills like Bhushan Power & Steel. Material is then precision-rolled, heat-treated or coated, and distributed through industrial suppliers to end-users in metal fabrication and paper mills.
Investment insights and strategic high-potential areas
Investors should target manufacturers specializing in high-tensile and polyester-coated steel strapping. These segments offer superior margins and align with modern automated logistics requirements across major industrial ports and fulfillment centers.
Conclusion and key takeaways for industry stakeholders
The Steel Strapping Market market size expansion to 2.77 Billion by 2033 underscores the sector's vital role in global heavy industry. Firms focusing on metallurgical innovation and corrosion resistance will capture outsized market share.
Research methodology for baseline estimates
Our research methodology triangulates primary stakeholder interviews with C-level executives, secondary trade registry data, macroeconomic industrial output indicators, and custom econometric modeling to establish authoritative baseline valuations and forecasts.
Scope of the report and coverage parameters
This report covers global manufacturing, distribution, and consumption dynamics of steel strapping across all listed product types, tensile grades, and application verticals. Exclusions involve non-steel alternatives such as plastic or polyester cord strapping.
Recent developments, partnerships, and strategic moves
Recent industry activity highlights capacity expansions by firms like Samuel, Son & Co. Inc. and new product rollouts focusing on eco-friendly, low-emission paint coatings. These strategic maneuvers aim to comply with tightening environmental regulations while boosting structural integrity.