What is the market overview, definition, scope, and industry significance of Fuels Market?
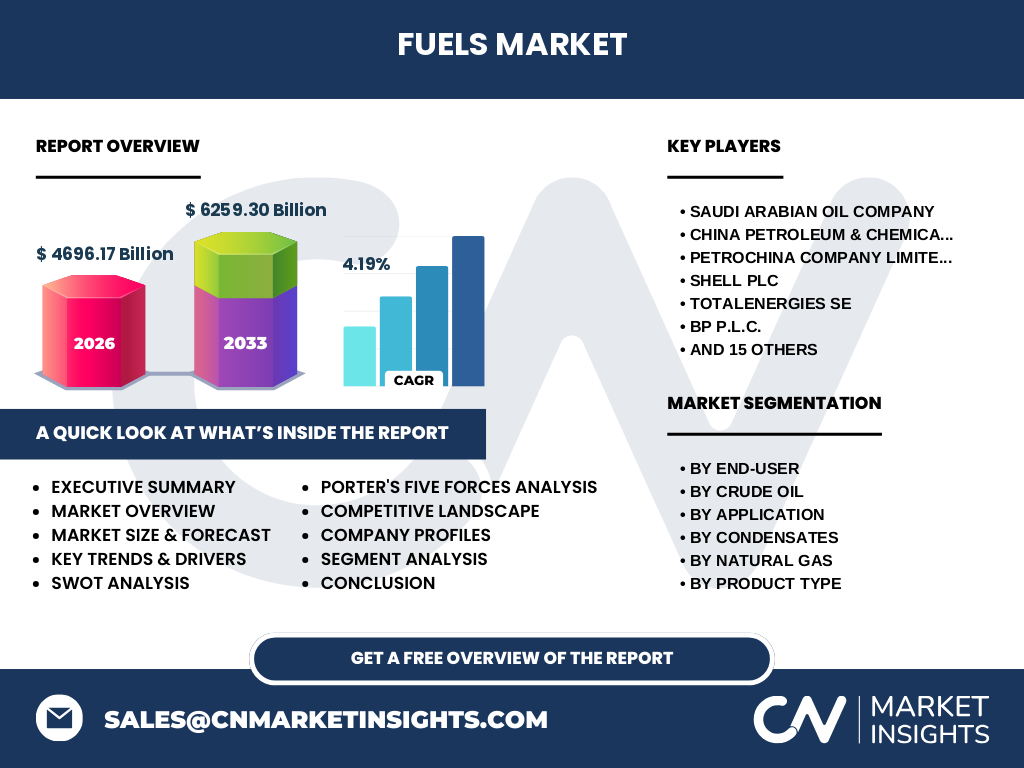
Our analysis indicates that the Fuels Market encompasses the extraction, processing, and distribution of vital energy commodities, reaching a market size of $4,696.17 Billion in 2026. This foundational sector underpins global industrial output, powering everything from Downstream Refiners to complex utility grids across international trade lanes.
Key market drivers, restraints, challenges, and opportunities shaping Fuels Market
Growth is heavily propelled by escalating baseline energy demands from emerging economies and continuous technological investments by giants like Saudi Arabian Oil Company and Exxon Mobil Corporation. However, strict environmental mandates by bodies such as the International Maritime Organization act as restraints, forcing operational shifts toward cleaner extraction methods.
Emerging trends and growth patterns in Fuels Market
The sector is witnessing a decisive pivot toward digital transformation and enhanced recovery techniques in fields rich in Shale Gas and Unconventional Natural Gas. Industry leaders like Shell plc and TotalEnergies SE are strategically investing in integrated gas networks to capture high-margin opportunities.
COVID-19 impact analysis — how the pandemic affected Fuels Market and the recovery trajectory
The pandemic triggered unprecedented demand destruction, temporarily paralyzing logistics networks utilized by PetroChina Company Limited and Chevron Corporation. Recovery has been robustly steered by post-lockdown industrial reactivation and structural supply adjustments orchestrated by OPEC+ containment frameworks.
Competitive landscape — major players, market concentration, and strategic dynamics
The competitive arena features a blend of dominant national oil companies and supermajors including BP p.l.c., Eni S.p.A., and Petróleo Brasileiro S.A. Market concentration remains high in upstream extraction, where scale dictates cost efficiency, while downstream segments focus on localized logistical resilience.
Executive summary — high-level synthesis of key findings about Fuels Market
The Fuels Market analysis demonstrates resilient valuation expansion, projecting a climb to $6,259.30 Billion by 2033 at a CAGR of 4.19%. Strategic realignment toward liquefied products and natural gas streams remains critical for sustaining long-term portfolio profitability amid shifting regulatory landscapes.
Market forecast — projected growth from 2027 to 2033
Driven by sustained industrial electrification and chemical feedstock requirements, the market is poised to expand from its 2026 baseline of $4,696.17 Billion to $6,259.30 Billion by 2033. This trajectory reflects a steady compound annual growth rate of 4.19% over the forecast timeline.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation spans multiple dimensions: End-User (including Downstream Refiners and Utilities), Product Type (covering Crude Oil, Natural Gas, and LPG), Extraction Source, and Natural Gas Liquids. Each category serves a distinct role in balancing regional refinery feedstock inputs with final consumer utility demands.
Regional market analysis — geographic distribution and performance across regions
Geographic performance is heavily anchored by rapid industrialization in Asia-Pacific, paired with mature, optimized extraction infrastructure across North America and the Middle East. Regional variances are dictated by local reserve availability, pipeline connectivity, and domestic energy security policies enacted by state authorities.
In-depth regional review — detailed examination of key regional markets
North America maintains a dominant extraction footprint led by shale assets managed by EOG Resources Inc. and Devon Energy Corporation. Simultaneously, Middle Eastern hubs driven by QatarEnergy command global export volumes, balancing European import dependencies managed through terminals operated by firms like Equinor ASA.
Company profiles — strategic positioning of leading companies in Fuels Market
Key market participants leverage distinct geographical strengths. China Petroleum & Chemical Corporation and CNOOC Limited dominate domestic refining and offshore integration, while Western supermajors like ConocoPhillips or Apache Corporation optimize asset portfolios through targeted upstream divestments and technological automation.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate to high due to geopolitical reserves control by entities like PJSC Rosneft Oil Company and Petróleos de Venezuela S.A. Threat of substitutes is cushioned by the irreplaceable nature of hydrocarbon feedstocks in chemical manufacturing, while buyer power fluctuates with regional oversupply conditions.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Core strengths lie in entrenched global distribution networks and massive capital outlays by firms such as PJSC LUKOIL and Murphy Oil Corporation. Weaknesses involve high carbon exposure, whereas opportunities exist in liquefied gas expansion. Threats stem from aggressive decarbonization mandates and volatile commodity price cycles.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain initiates upstream with seismic surveying and drilling in Onshore Fuels and Offshore Fuels, flows midstream via pipeline transportation and LNG carriers, and terminates downstream where Distributors And Traders supply fuel to Industrial Or Chemical Plants.
Investment insights — strategic recommendations and high-potential areas
Investors should prioritize assets aligned with high-margin Natural Gas Liquids (such as Ethane and Propane) and infrastructure projects championed by Occidental Petroleum Corporation. Operational efficiency and low break-even costs in unconventional plays represent primary criteria for sustainable equity appreciation.
Conclusion and key takeaways
The Fuels Market industry trends highlight an essential balancing act between meeting surging baseline energy needs and optimizing asset carbon intensity. With a projected valuation of $6,259.30 Billion by 2033, proactive capital allocation into technological innovations will separate market leaders from legacy laggards.
Research methodology — detail how baseline estimates are triangulated
Baseline estimates are meticulously derived by triangulating primary stakeholder interviews with C-suite executives, official trade registry statistics from energy ministries, and secondary macroeconomic indicators. This multi-tiered cross-referencing ensures robust quantification of market sizing and regional consumption patterns.
Scope of the report — coverage parameters and limitations
This comprehensive analysis covers global trade flows, extraction methodologies, and product categorizations spanning 2026 through 2033. Limitations include unpredictable geopolitical disruptions and sudden regulatory policy shifts that may temporarily distort short-term commodity price realizations and volume outputs.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent strategic maneuvers involve major joint ventures in deepwater extraction and long-term LNG supply agreements forged by global operators. Companies continuously refine their operational footprints to enhance supply chain resilience, responding dynamically to shifting trade tariffs and international energy security requirements.