What is the scope and industry significance of the Recreation Market?
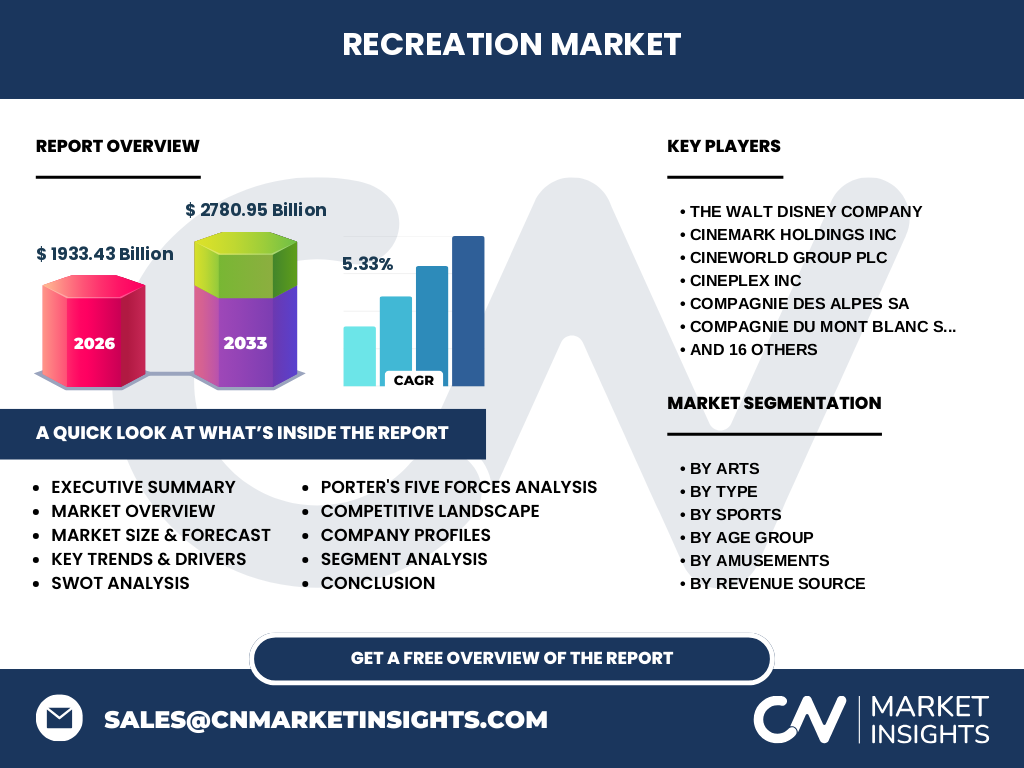
Our analysis indicates that the Recreation Market size reaches 1933.43 Billion in 2026, driven by global demand for Amusements, Arts, and Sports. This sector spans theme parks managed by The Walt Disney Company and fitness chains like Gym Group plc, serving as a critical economic engine for tourism, municipal infrastructure, and discretionary consumer spending worldwide.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Recreation Market?
Growth is propelled by rising disposable incomes and consumer appetite for immersive live experiences. However, capital-intensive infrastructure hurdles and fluctuating supply chains for specialized ride hardware constrain rapid expansion. Opportunities abound in digital integration, particularly leveraging media rights and mobile ticketing to capture younger demographic cohorts across urban centers.
Emerging trends and growth patterns in the Recreation Market
The shift toward hyper-personalized, tech-enabled leisure experiences is transforming operators like Universal Parks And Resorts. Consumers increasingly favor experiential spending over material goods, boosting demand for niche cultural events and premium individual sports facilities, which alters traditional asset utilization models.
COVID-19 impact analysis and recovery trajectory
Pandemic-era lockdowns severely disrupted traditional revenue streams like gate admissions and live sponsorships, forcing legacy operators to restructure debt and adopt contactless operations. The subsequent recovery trajectory highlights a resilient rebound, as pent-up consumer demand accelerates foot traffic across regional amusement parks and fitness hubs.
Competitive benchmarking and strategic market concentration
The landscape features a mix of multinational conglomerates like The Walt Disney Company and regional players such as Compagnie des Alpes SA. Market concentration is moderate to high in themed entertainment, compelling mid-tier operators to differentiate through localized intellectual property and strategic municipal partnerships.
Executive summary of key findings
Based on our research, the Recreation Market is poised for robust expansion, scaling from 1933.43 Billion in 2026 to 2780.95 Billion by 2033. Achieving a 5.33% CAGR, success hinges on digital transformation, optimized merchandising, and catering to diverse age groups ranging from Gen Z to active seniors.
Recreation Market forecast from 2027 to 2033
Our forecasting models project the market to expand from 2027 to 2033, culminating in a total valuation of 2780.95 Billion by the end of the forecast period. This steady trajectory reflects a compound annual growth rate of 5.33%, underpinned by sustained capital investments in premium leisure infrastructure.
Segmentation analysis by arts, type, sports, age group, amusements, and revenue source
The sector is categorized by Arts (Performing Arts, Visual Arts, Cultural Events), Type (Amusements, Arts, Sports), Sports (Team, Individual, Recreational), Age Group (Aged 35 and Younger, 35-54, 55 and Older), Amusements (Theme Parks, Water Parks, Arcades), and Revenue Source (Media Rights, Merchandising, Tickets and Sponsorship), each dictating distinct operational strategies.
Regional market analysis and geographic distribution
Geographic performance varies significantly due to local regulatory frameworks, real estate costs, and disposable income levels. North America and Europe dominate through mature theme park ecosystems and sports leagues, while Asia-Pacific emerges as the fastest-growing frontier, propelled by rising middle-class populations in China and Japan.
In-depth regional review of key markets
North America remains anchored by major players like Cedar Fair LP and Six Flags Entertainment Corporation, benefiting from established tourism corridors. Meanwhile, Asian markets are anchored by innovators like Oriental Land Company Ltd, leveraging high-density rail networks and strategic tourism boards to drive consistent visitation.
Strategic positioning of leading companies in the Recreation Market
Industry leaders employ distinct defensive and offensive moats. Merlin Entertainments Group focuses on multi-brand urban attractions, whereas Hall of Fame Resort And Entertainment Co integrates sports-themed real estate. This diverse positioning safeguards margins against inflationary pressures on raw construction materials.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to specialized ride and turf manufacturers, while buyer power is high given abundant leisure alternatives. Threat of substitution is mitigated by proprietary intellectual property held by firms like The Walt Disney Company, though high initial capital requirements create formidable entry barriers.
SWOT analysis of the sector
Strengths include strong brand equity and resilient consumer demand. Weaknesses involve high fixed operating costs and weather dependency. Opportunities lie in digital streaming of live events and international expansion. Threats encompass macroeconomic recessions and stringent safety regulations enforced by municipal authorities.
Value chain analysis from raw materials to end-users
The value chain originates with raw material providers for construction and digital software developers, flowing through operators like Cineworld Group plc and Cineplex Inc, and culminating with end-consumers experiencing live entertainment, sports, or ticketing solutions.
Investment insights and high-potential areas
Investors should target opportunities at the intersection of technology and leisure, specifically companies enhancing guest experiences via mobile apps, AR/VR integration, and diversified merchandising streams that protect against seasonal attendance dips.
Conclusion and key takeaways for industry stakeholders
The Recreation Market industry trends highlight an essential pivot toward experiential value and digital integration. With the market reaching 1933.43 Billion in 2026, stakeholders must prioritize agile asset management and targeted demographic engagement to capture long-term value.
Research methodology for baseline estimates
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with executives from firms like Cinemark Holdings Inc and Grupo Sports World SAB de CV, and secondary macroeconomic indicators governing global discretionary spending.
Scope of the report and coverage parameters
This report covers global market dynamics from 2026 to 2033, analyzing qualitative and quantitative metrics across specified segments. Limitations include unforeseen geopolitical shocks and localized regulatory shifts that may temporarily distort regional attendance figures.
Recent developments, corporate announcements, and strategic moves
Recent strategic maneuvers involve aggressive portfolio expansions by firms such as Guangdong Jinma Entertainment Corp Ltd and localized partnership deals executed by Country Club Hospitality And Holidays Ltd, reflecting an industry-wide push to capture post-pandemic leisure demand through innovative product launches.