What is the market overview of the Rolled And Drawn Steel Market?
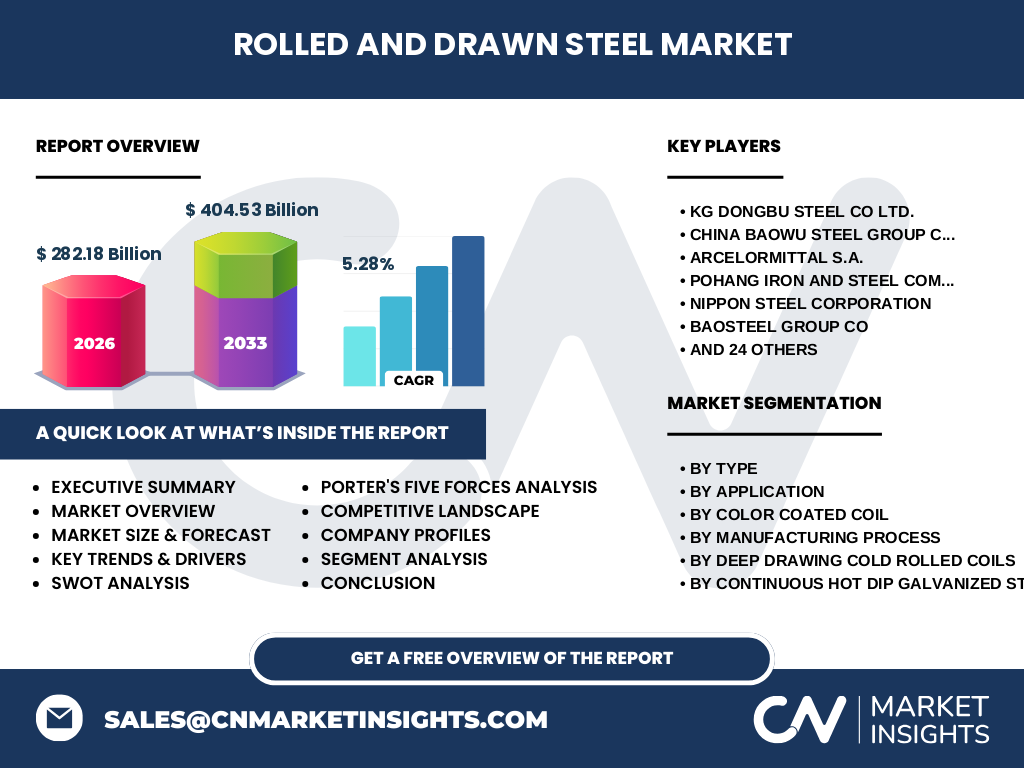
Our research establishes that the Rolled And Drawn Steel Market reaches a valuation of $282.18 Billion in 2026. This sector encompasses critical metallic inputs derived from primary iron ore and scrap processed through Basic Oxygen Furnaces and Electric Arc Furnaces, serving as the infrastructural backbone for global industrial manufacturing.
Structural Growth Drivers and Market Restraints
Growth is propelled by rapid urbanization and infrastructure investments, while volatile coking coal and iron ore input costs act as primary restraints. Stringent environmental compliance mandates by bodies like the World Steel Association further challenge legacy production workflows, forcing capital shifts toward green steel initiatives.
Emerging Trends in the Rolled And Drawn Steel Sector
The industry is experiencing a massive pivot toward decarbonized production lines and advanced high-strength steels. Electrification in automotive supply chains is accelerating demand for specialized coatings, compelling producers to upgrade continuous hot-dip lines to capture higher-margin applications.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-induced supply chain disruptions severely constricted logistics across major shipping hubs, temporarily depressing flat-rolled steel demand. However, aggressive fiscal stimulus packages and post-lockdown infrastructure revivals triggered a sharp V-shaped recovery, pushing baseline valuations toward upcoming expansion targets.
Competitive Benchmarking and Industry Consolidation
Market concentration remains moderate to high, dominated by international heavyweights like ArcelorMittal S.A., China Baowu Steel Group Corp Ltd., and Nippon Steel Corporation. These tier-one players leverage massive economies of scale and captive raw material assets to outmaneuver regional competitors.
Executive Summary of Rolled And Drawn Steel Market Insights
Driven by robust downstream demand from automotive and construction sectors, our analysis indicates the market is primed for steady expansion. Strategic investments in high-purity continuous casting will define industry winners over the next decade as end-users demand tighter metallurgical tolerances.
Rolled And Drawn Steel Market Forecast (2027-2033)
The data projects the market to surge from its 2026 baseline to reach $404.53 Billion by 2033. This trajectory represents a steady CAGR of 5.28%, underpinned by sustained capital deployment in emerging Asian and Latin American industrial corridors.
Segmentation Analysis Across Product and Application Lines
The market splits across intricate segments including Color Coated Coil, Continuous Hot Dip Galvanized Steel Coil, Carbon Structural Steel Cold Rolled Coils, and Deep Drawing Cold Rolled Coils. Automotive and construction applications command the largest volume shares, requiring specialized coil types for stampings and structural framing.
Regional Market Analysis and Geographic Performance
Asia-Pacific dominates global consumption, fueled by rapid industrialization in China, India, and South Korea. Meanwhile, North America and Europe emphasize strict regulatory compliance and high-value architectural coatings, driving regional adoption of premium pre-painted galvanized steel and electro-galvanized products.
In-Depth Regional Review of Key Manufacturing Hubs
Proximity to major ports like Shanghai, Rotterdam, and Houston dictates regional trade flows for rolled steel. Localized capacity additions by players like JSW Steel Limited and Tata Steel Limited in South Asia directly address surging regional deficits in high-grade cold-rolled coils.
Company Profiles and Strategic Positioning
Industry leaders like Nucor Corporation utilize scrap-fed Electric Arc Furnaces for low-carbon output, while integrated giants such as Pohang Iron and Steel Company focus on proprietary high-strength automotive alloys. Such strategic divergence allows firms to carve out defensible margin niches.
Porter's Five Forces Analysis of Competitive Intensity
Rivalry is intense due to high capital expenditure requirements and cyclical overcapacity. Bargaining power of raw material suppliers remains high for iron ore miners, while buyer power is moderate, balanced primarily by the technical complexity required for deep drawing cold-rolled coils.
SWOT Analysis of the Rolled And Drawn Steel Industry
Key strengths include established global supply networks and essential product utility; weaknesses involve high carbon footprints. Opportunities lie in lightweighting for electric vehicles, whereas regulatory carbon pricing and substitute aluminum alloys present persistent threats.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with upstream mining of metallurgical coal, iron ore, and limestone, progressing through reduction furnaces, hot rolling, cold reduction, and finishing lines. Midstream service centers and distributors play a pivotal role in slitting and blanking coils for end-users.
Investment Insights and High-Potential Growth Pockets
Investors should target greenfield electric arc furnace facilities and advanced coating lines designed for appliance and EV manufacturing. Capital allocation toward hydrogen-based direct reduced iron (DRI) projects offers strong long-term insulation against tightening carbon taxation.
Conclusion and Strategic Takeaways
The Rolled And Drawn Steel Market represents a resilient, evolving sector balancing traditional volume demands with aggressive decarbonization goals. Sustained profitability will heavily favor operators capable of blending metallurgical innovation with eco-efficient manufacturing paradigms.
Research Methodology and Data Triangulation
Our proprietary insights are generated by triangulating primary stakeholder interviews with C-level executives, official trade registry data, and secondary macroeconomic indicators. Bottom-up capacity modeling cross-referenced with regional export tariffs ensures exceptional accuracy in baseline market sizing.
Scope of the Report and Coverage Parameters
This report evaluates global production volumes, revenue figures, and consumption trends across defined geographical boundaries from 2026 through 2033. Limitations include unforeseen macroeconomic shocks and sudden shifts in international trade tariffs affecting cross-border steel shipments.
Recent Developments, Strategic Partnerships, and M&A Activity
Recent industry momentum highlights strategic joint ventures focused on low-carbon steel production and capacity expansions by market leaders like ArcelorMittal S.A. and Nippon Steel Corporation. These corporate maneuvers underscore an industry-wide race to secure green certification and high-value product contracts.