Corporate Strategy Market Overview and Industry Significance
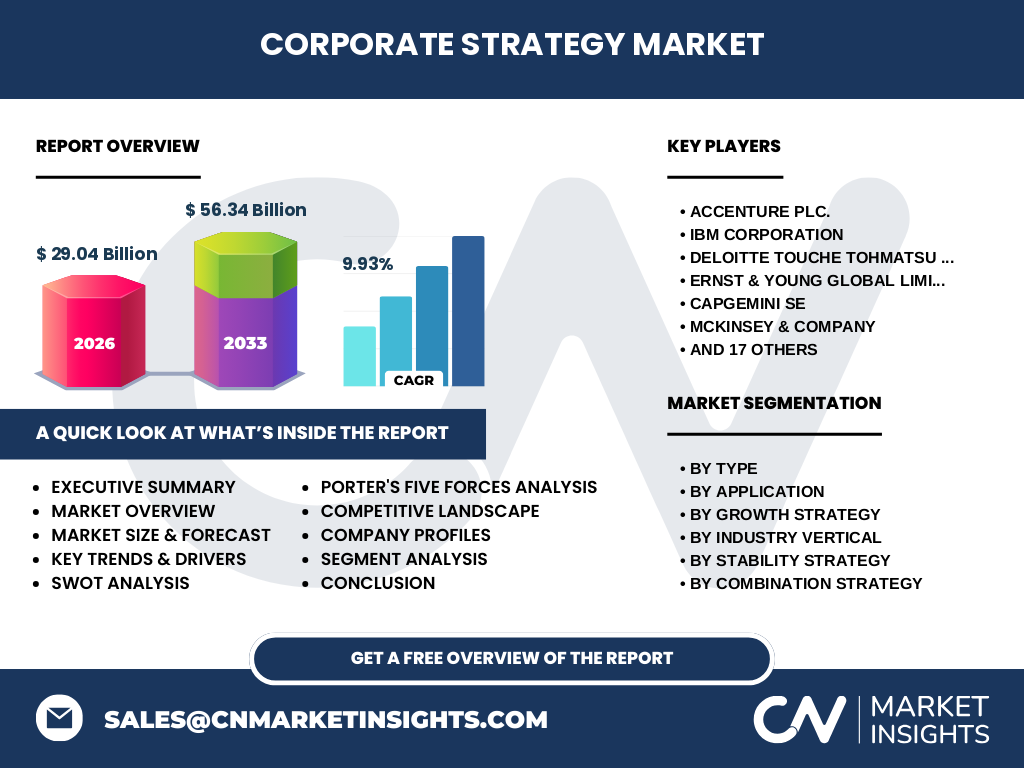
Our analysis indicates that the Corporate Strategy Market market size reaches 29.04 Billion in 2026. This sector encompasses executive advisory frameworks navigating complex regulatory environments such as SEC compliance and EU antitrust directives. Firms leverage these consulting paradigms to optimize resource allocation, manage supply chain volatility, and drive sustainable enterprise value across global macroeconomic cycles.
Structural Growth Drivers, Restraints, and Opportunities
The data suggests that accelerating digital transformation initiatives act as primary structural catalysts. However, severe talent shortages in specialized advisory domains pose operational restraints. Strategic opportunities emerge as organizations require targeted guidance on navigating cross-border trade friction, shifting labor regulations, and integrating advanced analytics into operational workflows.
Emerging Industry Trends and Growth Patterns
Corporate Strategy Market industry trends highlight a definitive pivot toward agile business model innovation and integrated sustainability metrics. Enterprises increasingly demand hyper-personalized consulting interventions rather than generic frameworks. This shift heavily favors agile innovators capable of deploying proprietary diagnostic tools to accelerate enterprise transformation and secure competitive advantage.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic fundamentally disrupted traditional advisory engagements, forcing an abrupt transition to remote capability delivery and immediate liquidity preservation. Our research shows that post-pandemic recovery relies heavily on strategic resilience planning, supply chain diversification, and accelerated cloud adoption. This crisis acted as a massive catalyst for modernizing corporate advisory service delivery models.
Competitive Landscape and Strategic Dynamics
Market concentration remains moderately fragmented among elite tier-one institutions and specialized boutique firms. Industry giants like McKinsey & Company, Boston Consulting Group Inc., and Bain & Company Inc. dominate large-scale transformations, while specialized players like Simon-Kucher & Partners GmbH carve out high-margin niches in pricing and growth advisory.
Executive Summary of Key Findings
Our comprehensive Corporate Strategy Market analysis projects phenomenal expansion, reaching 56.34 Billion by 2033 at a robust CAGR of 9.93%. Accelerated demand across financial services and healthcare verticals underpins this growth trajectory, emphasizing the critical need for sophisticated risk management and business model innovation frameworks.
Market Forecast from 2027 to 2033
Driven by persistent macroeconomic headwinds and rapid technological disruptions, the market is set to expand significantly from its 2026 baseline of 29.04 Billion to 56.34 Billion by 2033. This consistent 9.93% CAGR reflects sustained corporate reliance on external expert guidance to navigate complex restructuring and expansion initiatives.
Segmentation Analysis Across Core Categories
Segmentation spans Growth Strategy, Stability Strategy, Retrenchment Strategy, and Combination Strategy. Applications target Small, Medium, and Large Enterprises. Consulting service types break down into Business Model Innovation, Market Research, Cost Reduction, and Performance Improvement. Growth strategies further divide into Market Expansion, Product Development, and Diversification categories.
Regional Market Analysis and Geographic Distribution
Geographic performance demonstrates distinct maturity curves, with North America retaining dominant market share due to high enterprise density and early technology adoption. Europe follows closely, driven by stringent regulatory compliance mandates, while the Asia-Pacific region exhibits the fastest growth velocity, propelled by surging industrialization and expanding financial services sectors.
In-Depth Regional Review
North American enterprises prioritize aggressive digital transformation and portfolio diversification, whereas European markets focus heavily on sustainability mandates and governance frameworks. Meanwhile, APAC economies like India and Southeast Asia experience massive demand for foundational market entry and scaling strategies, led by expanding middle-class consumer bases and robust IT sectors.
Strategic Positioning of Leading Companies
Industry leaders deploy distinct strategic positioning to capture market share. Firms like Accenture plc. and IBM Corporation integrate technical implementation with strategic advisory. Meanwhile, legacy giants like Deloitte Touche Tohmatsu Limited and PricewaterhouseCoopers International Limited leverage their vast audit and tax networks to cross-sell comprehensive corporate restructuring and compliance services.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of buyers remains high due to the abundance of capable consulting providers. Threat of substitutes is moderate, countered by the specialized human capital required for complex transformations. Competitive rivalry is fierce among tier-one firms, while threat of new entrants is mitigated by high brand equity and proprietary methodology requirements.
SWOT Analysis of the Corporate Strategy Sector
Key strengths lie in deep industry expertise and robust proprietary analytical frameworks. Weaknesses involve high project costs and reliance on scarce talent. Opportunities abound in emerging digital ecosystems and ESG advisory, while major threats include economic downturns reducing discretionary corporate consulting budgets and tightening data privacy regulations.
Value Chain Analysis and Industry Structure
The value flow begins with foundational macroeconomic data inputs, primary stakeholder interviews, and regulatory registries. This raw intelligence is processed through proprietary analytical models by firms like Oliver Wyman LLC and Roland Berger Strategy Consultants GmbH, ultimately delivering actionable strategic roadmaps to executive boards and end-user enterprise decision-makers.
Investment Insights and High-Potential Areas
Strategic investment should prioritize niche boutiques specializing in digital transformation, ESG compliance, and advanced analytics. Our analysis indicates that merging traditional management consulting with deep technological implementation capabilities yields the highest enterprise valuation multiples and sustainable client retention rates over the forecast period.
Conclusion and Key Takeaways
The Corporate Strategy Market represents a vital growth engine for global enterprises navigating unprecedented volatility. With a projected valuation of 56.34 Billion by 2033, organizations that successfully integrate agile growth strategies, robust cost reduction frameworks, and advanced technological consulting will capture disproportionate market share and long-term resilience.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining exhaustive trade registry data, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators from global financial bodies. This multi-layered approach ensures high fidelity in market sizing, growth rate calculations, and competitive landscape assessments across all evaluated industry verticals.
Scope of the Report and Coverage Parameters
This report covers global market dynamics from 2026 through 2033, evaluating comprehensive breakdowns across consulting service types, enterprise scales, and industry verticals including Banking, Financial Services, Insurance, Healthcare, IT, Telecommunications, Manufacturing, and Retail. Macroeconomic variables impacting regional exchange rates and cross-border trade policies are integrated within defined analytical boundaries.
Recent Developments in the Consulting Ecosystem
Recent strategic moves feature aggressive cross-border acquisitions and technology partnerships aimed at bolstering AI and ESG advisory capabilities. Firms like Alvarez & Marsal Holdings LLC and AlixPartners LLP have expanded their restructuring footprints, while institutions like KPMG International Cooperative and Ernst & Young Global Limited scale proprietary digital platforms to streamline client service delivery.