What is the market overview of the Insoluble Sulfur Market?
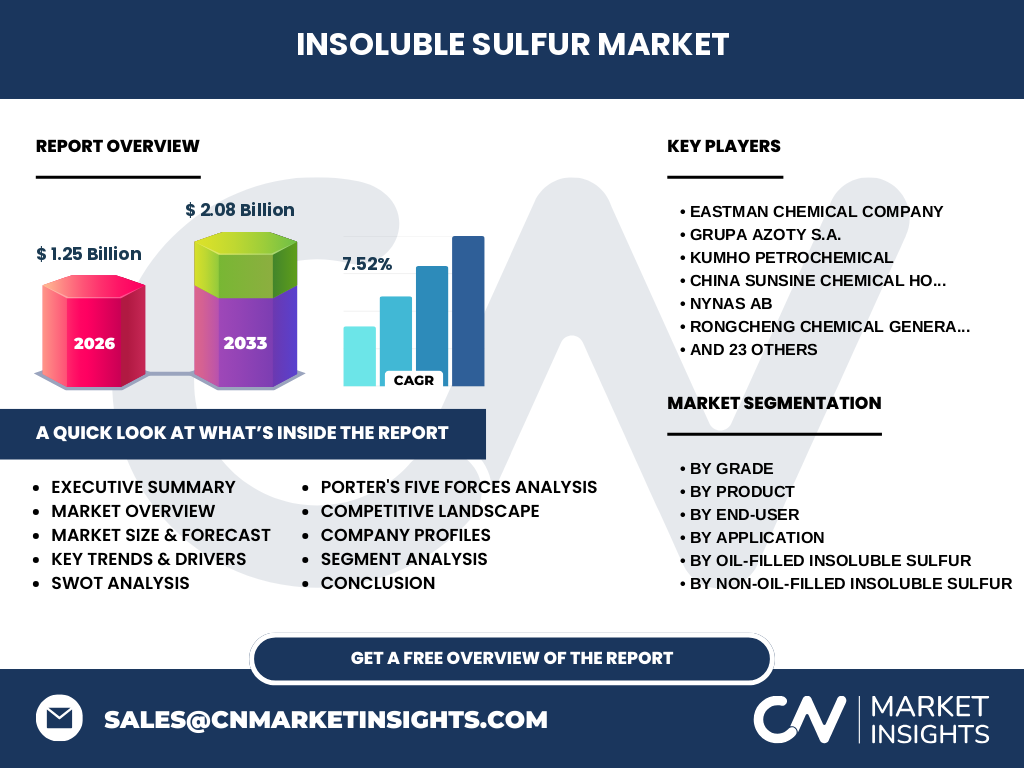
Our research indicates that the Insoluble Sulfur Market represents a critical segment in advanced rubber compounding, valued at 1.25 Billion in 2026. This polymeric form of sulfur prevents premature vulcanization and rubber blooming in high-performance radial tires, serving as an indispensable crosslinking agent for industry leaders like Eastman Chemical Company and China Sunsine Chemical Holdings Limited.
Structural Growth Drivers and Market Restraints
The market is propelled by expanding radial tire production across automotive hubs, offset by strict environmental regulations regarding carbon disulfide emissions during production. Eastman Chemical Company and Grupa Azoty S.A. navigate these hurdles through proprietary stabilization technologies, ensuring thermal stability during intense mixing cycles.
Emerging Trends in the Insoluble Sulfur Industry
A definitive shift toward High Dispersion Grades is transforming manufacturing floors, as Tier-1 automotive suppliers demand superior compound homogeneity. Companies like KUMHO PETROCHEMICAL and Oriental Carbon and Chemicals Limited are capturing share by engineering products that eliminate agglomeration issues in complex silica tread formulations.
Pandemic Disruption and Post-COVID Recovery
The COVID-19 pandemic caused severe supply chain contractions across maritime logistics and raw material sourcing, temporarily depressing demand from automotive end-users. Recovery has been robust, driven by localized supply chain investments by regional producers such as Henan Kailun Chemical Co. Ltd. and Shikoku Chemical Industry Co. Ltd. to insulate against future shocks.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains moderate to high, dominated by global giants alongside aggressive regional players like Tianjin Kemai Chemical Co. Ltd. and Sennics Co. Ltd. Strategic positioning relies on backward integration into raw materials and localized warehousing near major port facilities to guarantee uninterrupted supply to multinational tire manufacturers.
Executive Summary: Insoluble Sulfur Market Overview
Our analysis projects the Insoluble Sulfur Market to expand from 1.25 Billion in 2026 to 2.08 Billion by 2033, achieving a robust CAGR of 7.52%. Accelerated adoption in electric vehicle tire manufacturing and stringent performance specifications are the primary catalysts for this sustained multi-year expansion.
Long-Term Market Forecast (2027 to 2033)
Driven by compounding demand in Asia-Pacific and European mobility sectors, the market will scale steadily to reach 2.08 Billion by 2033 at a 7.52% CAGR. Capital expenditure is shifting toward capacity expansions by Willing New Materials Technology Co. Ltd. and Nynas AB to capture upcoming volume demands.
Segmentation Analysis Across Grades and Applications
Segmentation spans Regular Grades, High Dispersion Grades, High Stability Grades, and Special Grades, categorized further by Non-Oil-Filled and Oil-Filled variants. Tire manufacturing commands the lion share, while cable and wire applications leverage specialized non-oil-filled types to prevent blooming and maintain electrical insulation properties.
Geographic Distribution and Regional Performance
Regional consumption patterns heavily mirror domestic automotive manufacturing output and synthetic rubber processing infrastructure. Asia-Pacific leads consumption due to dense manufacturing clusters in China and Southeast Asia, while European markets prioritize high-stability grades to meet stringent REACH chemical compliance standards set by the European Chemicals Agency.
In-Depth Regional Review: Growth Hotspots
China remains the dominant regional manufacturing base, supported by domestic feedstock availability for players like Rongcheng Chemical General Factory and Hebei Hengli Chemical Co. Ltd. Meanwhile, North American demand centers on replacement tire durability, favoring advanced oil-filled grades supplied through established regional distribution networks.
Company Profiles and Strategic Positioning
Industry leaders like Eastman Chemical Company leverage global supply networks and intellectual property, while regional powerhouses such as China Sunsine Chemical Holdings Limited compete on cost efficiency and massive production scale. Specialty innovators like Ningbo Actmix Rubber Chemicals Co. Ltd. focus on customized masterbatch delivery formats.
Porter's Five Forces Analysis
Supplier power is moderate due to upstream sulfur availability, whereas buyer power remains high among major tire conglomerates capable of switching vendors. Threat of substitutes is low because insoluble sulfur remains chemically unique in preventing premature vulcanization during high-temperature rubber compounding operations.
SWOT Analysis of the Global Sector
Strengths lie in essential elastomer crosslinking performance and thermal stability. Weaknesses involve hazardous manufacturing processes requiring strict safety controls. Opportunities emerge in electric vehicle tire lightweighting, while threats include volatile raw material sulfur pricing and stringent environmental compliance mandates from regulatory bodies.
Value Chain Analysis: From Raw Material to End-User
The value chain originates with petroleum refining and natural gas processing yielding elemental sulfur, which is subsequently polymerized under controlled thermal conditions. Intermediaries process this into Oil-Filled and Non-Oil-Filled variants before specialized logistics providers deliver the material to Tier-1 automotive rubber fabricators.
Investment Insights and High-Potential Areas
Investors should target manufacturers specializing in High Dispersion Grades, as these command premium margins driven by stringent silica tire requirements. Strategic partnerships with regional players like Jining Fortune Biotech Co. Ltd. or Jiangxi Shengchang Technology Co. Ltd. offer high-growth exposure in emerging Asian markets.
Conclusion and Strategic Takeaways
The Insoluble Sulfur Market offers compelling growth, moving from 1.25 Billion to 2.08 Billion at a 7.52% CAGR. Success hinges on technological adaptation, environmental compliance, and deep integration with global tire manufacturers transitioning toward sustainable, high-performance compounds.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with c-suite executives across Eastman Chemical Company and Sennics Co. Ltd., and secondary macroeconomic indicators tracking global automotive tire production volumes and synthetic rubber consumption rates.
Scope of the Report and Coverage Parameters
This report covers the global Insoluble Sulfur Market analysis across all defined grades, product types, and end-user applications from 2026 to 2033. Limitations include localized pricing fluctuations and unrecorded domestic consumption within emerging economies not captured by official export registries.
Recent Developments and Strategic Moves
Recent industry activity features capacity expansion announcements and greenfield facility investments by firms such as Oriental Carbon and Chemicals Limited and Puyang Willing Chemicals Co. Ltd. These strategic maneuvers aim to secure long-term supply agreements with multinational tire brands seeking supply chain diversification.