Market Overview and Industry Significance of the Shale Gas Market
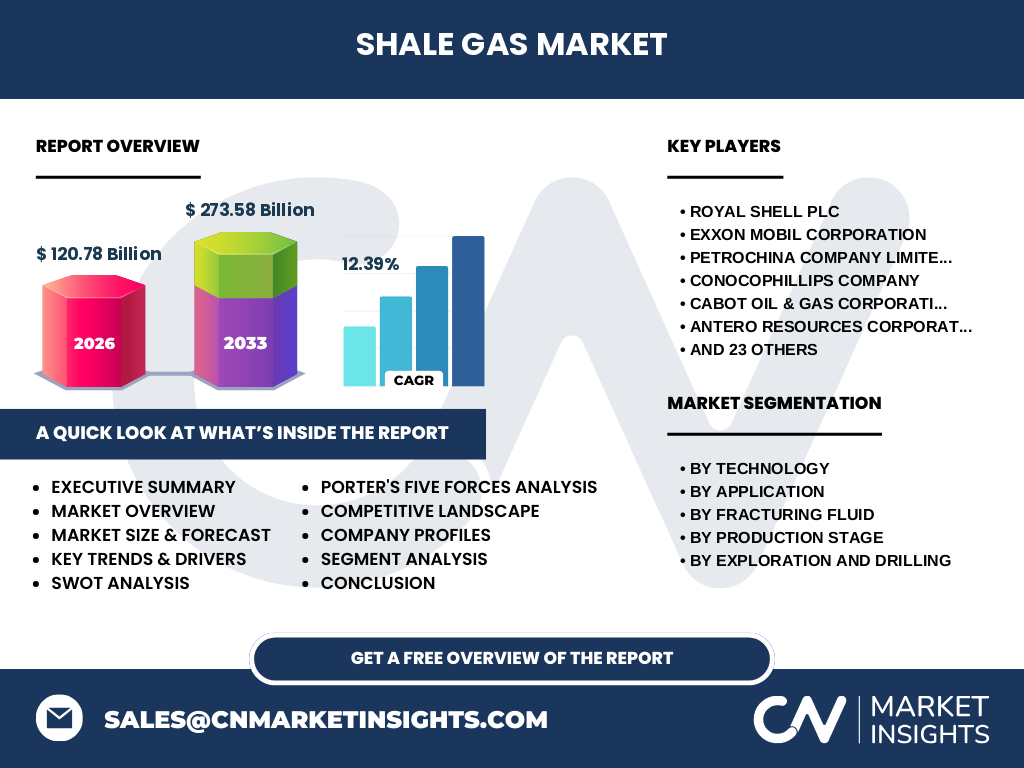
Our analysis indicates that the Shale Gas Market market size reaches USD 120.78 Billion in 2026. This sector encompasses unconventional natural gas extraction from impermeable sedimentary rock formations utilizing advanced hydraulic fracturing and horizontal drilling. Regulatory frameworks enforced by bodies like the EPA dictate fluid management, making technological efficiency paramount for operators.
Structural Growth Drivers and Market Restraints
The primary catalyst is surging global energy demand coupled with technological refinements in multi-stage fracking. Conversely, strict environmental compliance regarding flowback water disposal and pipeline bottlenecks in key basins act as significant market restraints. Companies must navigate these hurdles to capture expanding margins.
Emerging Trends in Shale Gas Industry Trends
The shift toward digital oilfield integration and data-driven reservoir characterization is revolutionizing output efficiency. Operators are increasingly adopting recycled water solutions in water-based fracturing fluids to mitigate ESG pressures and lower operating expenditures across major North American plays.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic triggered an unprecedented contraction in energy consumption, forcing widespread shut-ins and capital expenditure cuts. However, the post-pandemic recovery trajectory proved robust, driven by rebounding industrial activity and liquefied natural gas export demands, steering the sector toward rapid valuation expansion.
Competitive Benchmarking and Market Concentration
The landscape is characterized by high consolidation among supermajors and focused independents. Industry leaders like Exxon Mobil Corporation and ConocoPhillips Company leverage economies of scale and proprietary subsurface analytics to optimize well performance and maintain dominance over smaller regional players.
Executive Summary of the Shale Gas Market Analysis
Our comprehensive research projects the Shale Gas Market analysis to surge from USD 120.78 Billion in 2026 to USD 273.58 Billion by 2033, exhibiting a stellar 12.39% CAGR. Rapid technological adoption and expanding applications in power generation underpin this multi-fold expansion.
Market Forecast and Long-Term Projections (2027-2033)
Driven by sustained macroeconomic growth and infrastructural build-out, the market is poised to achieve USD 273.58 Billion by 2033. Achieving a 12.39% CAGR from 2027 onward, the sector offers lucrative entry points for investors prioritizing high-yield energy assets.
Segmentation Breakdown: Technology, Application, and Fluid Types
The market segments into exploration and drilling, fracturing fluid, application, production stage, and fluid categories. Key sub-segments include power generation, horizontal drilling, and water-based fracturing fluids. Each category plays a critical role in determining well productivity and environmental footprint.
Regional Market Performance and Geographic Distribution
North America commands the largest share due to mature shale basins like the Permian and Marcellus. Meanwhile, Asia-Pacific exhibits the fastest regional growth, propelled by aggressive exploration initiatives by PetroChina Company Limited and China Petroleum & Chemical Corporation (SINOPEC) to secure domestic energy independence.
In-Depth Regional Review of Core Production Basins
Regional dynamics heavily favor areas with established pipeline networks and pro-business regulatory climates. While North American basins focus on efficiency gains, emerging shale plays in China face unique geological complexities that require specialized horizontal drilling techniques and customized fracturing fluid additives.
Strategic Company Profiles and Market Positioning
Leading entities such as EOG Resources Inc., Devon Energy Corporation, and Baker Hughes Incorporation employ aggressive asset portfolio optimization. Their strategic focus on tier-one acreage acquisition and proprietary drilling technologies secures sustainable competitive advantages in a high-cost environment.
Porter's Five Forces Analysis of the Shale Gas Sector
Bargaining power of suppliers remains moderate due to specialized oilfield service requirements, while threat of substitutes is buffered by natural gas's baseload reliability. High capital requirements and stringent environmental permits effectively keep the threat of new entrants relatively low.
SWOT Analysis: Strategic Strengths, Weaknesses, Opportunities, and Threats
Strengths include advanced drilling efficiency; weaknesses involve high initial capital expenditure. Opportunities lie in international expansion into untapped basins, whereas threats stem from stringent carbon emission policies and volatile commodity price fluctuations dictated by geopolitical events.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from upstream seismic surveying and raw material extraction (sand, chemical additives) through midstream pipeline transport to downstream power generation and industrial end-users. Efficiency at each node directly dictates overall operational profitability for producers.
Investment Insights and High-Potential Areas
Investors should target technological innovators specializing in ESG-compliant fracturing fluid additives and well automation. Companies demonstrating disciplined capital allocation in Tier-1 acreage offer superior risk-adjusted returns throughout the forecast period.
Conclusion and Strategic Takeaways
The market presents exceptional growth, advancing at a 12.39% CAGR toward USD 273.58 Billion by 2033. Stakeholders must embrace digital transformation and stringent environmental stewardship to capitalize on expanding global energy needs.
Research Methodology and Baseline Triangulation
Our baseline estimates are triangulated by synthesizing official trade registry data, primary stakeholder interviews with industry executives, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of the Shale Gas Market market size.
Scope of the Report and Coverage Parameters
This report covers global shale gas dynamics across all major segments from 2026 to 2033. Limitations include unforeseen geopolitical disruptions and sudden macroeconomic shifts that could temporarily alter baseline production forecasts.
Recent Industry Developments, Partnerships, and Strategic Moves
Recent developments feature strategic mergers among Permian basin operators and technological joint ventures aimed at reducing water consumption. Companies like Chevron Corporation continue to invest heavily in low-carbon extraction tech, aligning with tightening global emissions mandates.