What is the market overview and industry significance of the Jet Skis Market?
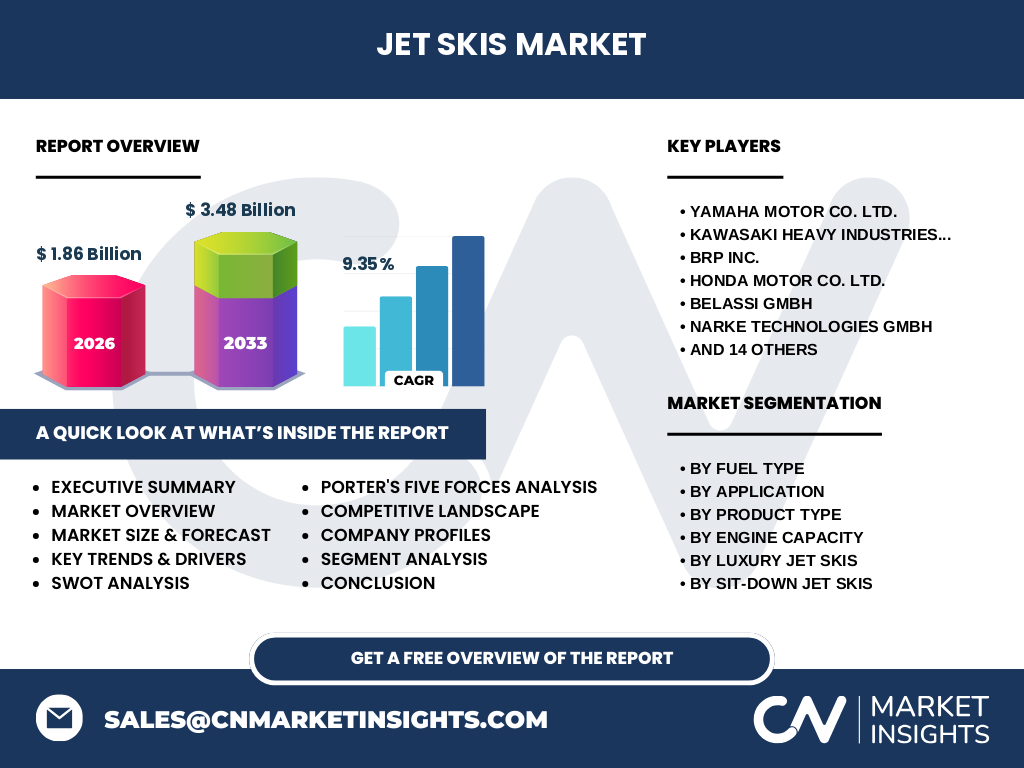
Our analysis indicates that the Jet Skis Market is valued at 1.86 Billion in 2026, driven by rising disposable incomes and expanding coastal tourism. This sector encompasses personal watercraft used for leisure and rescue operations. Manufacturers rely heavily on fiberglass composite raw materials and advanced marine propulsion systems to meet stringent environmental standards enforced by the EPA and European Union Recreational Craft Directive.
Key market drivers, restraints, challenges, and opportunities shaping Jet Skis Market
Growth is propelled by expanding waterfront infrastructure and adventure tourism. However, strict environmental regulations regarding two-stroke engine emissions act as key restraints. Supply chain bottlenecks for lithium-ion batteries present operational challenges. The primary opportunity lies in developing zero-emission electric propulsion models to capture eco-conscious consumer segments.
The Shift Toward Electric Propulsion and Smart Marine Technology
The industry is experiencing a rapid pivot toward sustainability, led by pioneers like Taiga Motors Corporation and Mako Electric LLC. Consumers increasingly demand quieter, zero-emission watercraft. This trend forces traditional manufacturers to integrate smart telematics, GPS geofencing, and digital helm displays, redefining the modern personal watercraft experience.
COVID-19 impact analysis and recovery trajectory
The pandemic initially disrupted global supply chains originating from major manufacturing hubs in China and North America, halting component shipments for companies like Yamaha Motor Co. Ltd. and BRP Inc.. However, post-lockdown demand surged as consumers sought socially distanced outdoor recreation, accelerating market recovery and expanding retail backlogs significantly.
Competitive benchmarking and strategic dynamics in the Jet Skis Market
Market concentration is high, dominated by established multinational powers like Yamaha Motor Co. Ltd., Kawasaki Heavy Industries Ltd., and BRP Inc.. These industry leaders maintain formidable distribution networks and massive R&D budgets. Meanwhile, niche innovators such as Belassi GmbH and Taiga Motors Corporation carve out profitable segments through bespoke luxury crafting and electric powertrain exclusivity.
Executive Summary: High-Level Synthesis of Key Findings
The Jet Skis Market is poised for robust expansion, projected to reach 3.48 Billion by 2033 at a CAGR of 9.35%. Our research highlights that shifting consumer preferences toward luxury models and electric variants are reshaping product portfolios. Strategic consolidation and supply chain localization will define the next phase of industry profitability.
Market Forecast for the Jet Skis Market from 2027 to 2033
Based on our econometric modeling, the market will scale from its 2026 baseline to hit 3.48 Billion by 2033, expanding at a steady CAGR of 9.35%. Accelerated adoption of high-end tech-integrated watercraft and commercial rescue applications in Asia-Pacific and North American coastal regions will anchor this upward trajectory.
Segmentation analysis of the Jet Skis Market
Our taxonomy divides the market across multiple dimensions: By Fuel Type (Gasoline, Electric), By Application (Recreational, Commercial), By Product Type (Stand-Up, Sit-Down, Luxury, Performance), By Engine Capacity (Below 800 cc up to Above 1500 cc), and By Distribution Channel (Online, Offline). Each segment addresses distinct consumer utility profiles.
Geographic distribution and regional market performance
Regional performance varies based on coastline availability, disposable income, and local maritime laws. North America and Europe represent mature markets with high demand for luxury and high-performance models. Meanwhile, the Asia-Pacific region, anchored by manufacturers like Jiujiang Hison Motor Boat Manufacturing Co. Ltd., exhibits the fastest growth due to expanding tourism infrastructure.
In-depth regional review of key markets
North America dominates revenue generation, driven by massive domestic uptake in coastal states and freshwater lake districts. Europe enforces stringent noise and emissions caps under the EU RCD, favoring advanced four-stroke and electric models. Emerging markets in Latin America and Asia-Pacific display high elasticity, driven by resort developments and commercial rental fleet expansions.
Strategic positioning of leading companies in the industry
Industry giants like Yamaha Motor Co. Ltd. and BRP Inc. leverage global dealer networks and brand equity to maintain leadership. High-end specialists like Belassi GmbH target ultra-wealthy consumers with handcrafted luxury watercraft. Electric disruptors like Taiga Motors Corporation focus on eco-tourism operators seeking sustainable fleet upgrades.
Porter's Five Forces analysis of competitive intensity
Competitive rivalry is fierce among top-tier brands holding patents on hull designs and engine tuning. Bargaining power of suppliers is moderate, constrained by specialized marine fiberglass and battery vendors. Threat of substitutes remains low due to the unique recreational value proposition of personal watercraft over standard boats.
SWOT analysis of the global sector
Key strengths include strong brand loyalty and advanced hydrodynamic engineering. Weaknesses involve high maintenance costs and seasonal demand fluctuations. Opportunities lie in emerging electric mobility subsidies and untapped eco-tourism markets. Threats stem from tightening coastal emissions regulations and rising raw material costs for aluminum and resins.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material sourcing—primarily fiberglass, carbon fiber, and lithium-ion cells. Tier-1 component manufacturers supply precision fuel-injection and jet-pump assemblies to OEMs like Kawasaki Heavy Industries Ltd. and Honda Motor Co. Ltd.. Final distribution occurs via authorized dealer networks and online platforms to end-users.
Investment insights and high-potential areas
Investors should direct capital toward electric propulsion technology and lightweight composite manufacturing. Companies prioritizing modular battery swapping and smart geofencing software represent prime acquisition targets. High-growth resort regions in Southeast Asia offer lucrative opportunities for commercial fleet investment.
Conclusion and key takeaways for stakeholders
The Jet Skis Market demonstrates exceptional resilience and growth potential, heading toward 3.48 Billion by 2033. Stakeholders must embrace electrification and lightweight engineering to maintain competitive advantage. Regulatory compliance and supply chain diversification will remain critical success factors.
Research methodology for baseline estimates
Our analytical framework triangulates data from multiple authoritative sources. We combine customs trade registry statistics, primary stakeholder interviews with executives from BRP Inc. and Yamaha Motor Co. Ltd., and secondary macroeconomic indicators to build accurate market size and forecast models.
Scope of the report and coverage parameters
This comprehensive market research report covers global trends, regional deep dives, and granular segment analysis from 2026 to 2033. Excluded from this scope are commercial cargo vessels and recreational yachts, focusing strictly on personal watercraft and jet skis.
Recent developments, company announcements, and strategic moves
Recent industry activity highlights aggressive R&D investments in zero-emission propulsion. Companies like Taiga Motors Corporation have scaled production capacity for electric watercraft, while traditional players such as Zhejiang Linhai Yacht Co. Ltd. expanded export partnerships across European distribution channels to counter domestic market saturation.