What is the market overview of the Glass Tableware Market?
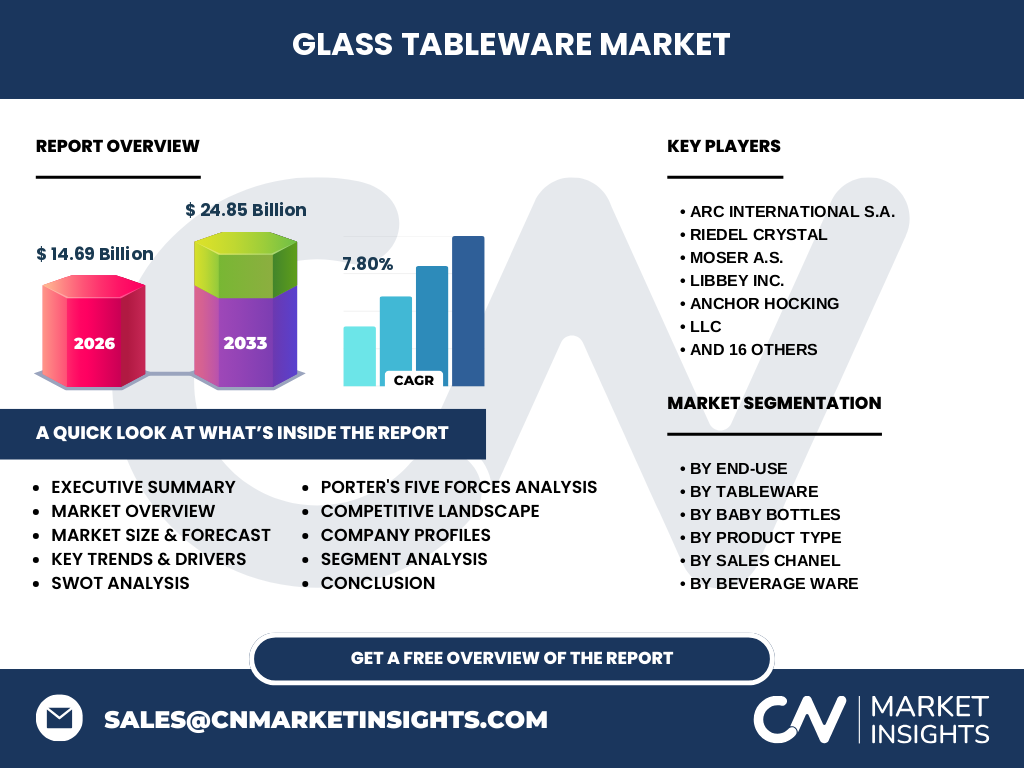
Our analysis indicates that the Glass Tableware Market valued at 14.69 Billion in 2026 is entering a transformative phase driven by consumer demand for sustainable dining solutions. The industry scope encompasses household and commercial segments utilizing advanced soda-lime and borosilicate formulations, navigating strict FDA and European Food Safety Authority regulations governing heavy metal leachates in premium glassware.
Key market drivers, restraints, challenges, and opportunities shaping the Glass Tableware Market
Growth is propelled by rising urbanization and hospitality sector expansion, while energy-intensive furnace operations present cost restraints amid volatile natural gas prices. Logistical bottlenecks at major ports like Rotterdam and Shanghai challenge international supply chains. However, expanding direct-to-consumer e-commerce channels offer lucrative opportunities for premium brands.
Emerging trends and growth patterns in the Glass Tableware Market
Consumers increasingly favor artisanal aesthetics and lightweight, thermally shock-resistant borosilicate drinkware. Sustainable manufacturing practices, including cullet recycling and hydrogen-fueled furnaces adopted by innovators like Steklarna Hrastnik, define current industry trends. This shift directly favors agile manufacturers capable of producing custom aesthetic designs rapidly.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted the commercial dining sector, halting institutional orders for high-end plates and stemware. Conversely, home-cooking surges boosted household retail sales of bakeware and tumblers. Recovery has been robust, led by hospitality reopenings and strategic digital inventory diversification by established European and North American heritage producers.
Competitive benchmarking and strategic dynamics in the Glass Tableware Market
The landscape features intense competition among legacy players like Arc International S.A., Libbey Inc., and Villeroy & Boch AG. Market concentration is moderate to high in premium segments where craftsmanship dictates pricing power, whereas commoditized beverage ware sees aggressive price competition from Asian export hubs.
Executive summary of the Glass Tableware Market overview
Driven by robust demand across household and commercial channels, the Glass Tableware Market is projected to reach 24.85 Billion by 2033, expanding at a notable CAGR of 7.80% from 2027. Strategic investments in automation, eco-friendly melting technology, and omnichannel distribution are critical for capturing market share.
Market forecast from 2027 to 2033
Based on our research, the market will expand from its 2026 baseline to achieve 24.85 Billion by 2033, maintaining a steady compound annual growth rate of 7.80%. This trajectory is underpinned by rising disposable incomes in emerging economies and ongoing replacement cycles in commercial hospitality venues worldwide.
Segmentation analysis by end-use, product type, and sales channels
The market breaks down into household and commercial end-uses, spanning product categories such as Beverage Ware, Tableware, and Baby Bottles. Sub-segments include glass plates, bowls, wine glasses, and anti-colic baby feeding bottles. Distribution occurs via hypermarkets, specialty stores, and online retailers, each fulfilling distinct consumer purchasing behaviors.
Geographic distribution and regional market performance
Regional performance varies significantly, with Europe dominating luxury glassware production via heritage hubs in France, Germany, and the Czech Republic. North America demonstrates strong institutional demand across commercial hospitality, while Asia-Pacific represents the fastest-growing manufacturing and consumer consumption base due to expanding urban middle classes.
In-depth regional review of key geographic markets
European markets prioritize artisanal heritage and stringent environmental compliance, limiting carbon footprints through localized sourcing. In contrast, the North American market favors high-volume durability and commercial-grade dishwasher resistance. The Asia-Pacific region leverages advanced manufacturing ecosystems in Taiwan and mainland China to dominate mass-market export volumes.
Company profiles and strategic positioning of leading market participants
Industry leaders maintain distinct strategic positioning. Riedel Crystal and Moser a.s. focus on varietal-specific luxury stemware and handcrafted crystal artistry. Meanwhile, mass-market giants like Anchor Hocking and Corelle Brands LLC emphasize shatter-resistant durability and widespread hypermarket availability to capture high-volume household sales.
Porter's Five Forces analysis of the industry structure
Supplier power remains moderate due to heavy reliance on silica sand and soda ash commodities. Buyer power is high given extensive retail alternatives. Threat of substitution from stainless steel and premium plastics is notable in casual outdoor settings, while industry rivalry is fierce among established global glassware conglomerates.
SWOT analysis of the Glass Tableware Market
Strengths include the infinitely recyclable nature of glass and high consumer perception of safety. Weaknesses involve high freight shipping breakage rates and brittle material characteristics. Opportunities lie in smart-glass integration and eco-certified packaging, while threats stem from surging energy tariffs and geopolitical trade tariffs.
Value chain analysis from raw materials to end-users
The value chain originates with raw material extraction—silica sand, limestone, and soda ash. Batch mixing and high-temperature furnace melting follow, executed by manufacturers like Bormioli Rocco S.p.A. or Pasabahce. Value is added through annealing, quality inspection, and logistics management before reaching wholesalers, retailers, and end consumers.
Investment insights and high-potential areas
Investors should target companies integrating energy-efficient electric melting furnaces and automated optical inspection systems. High-potential growth areas include sustainable borosilicate baby bottles and premium direct-to-consumer digital channels that bypass traditional wholesale margin compression.
Conclusion and key takeaways for industry stakeholders
The Glass Tableware Market offers compelling growth prospects, scaling from 14.69 Billion to 24.85 Billion at a 7.80% CAGR. Stakeholders must prioritize circular economy compliance, energy efficiency, and resilient omnichannel distribution to successfully navigate macroeconomic headwinds through 2033.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are triangulated by combining customs trade registry data, primary stakeholder interviews with c-suite executives across Libbey Inc. and Zwiesel Kristallglas AG, and secondary macroeconomic indicators. This rigorous validation ensures high-fidelity market sizing across all evaluated product segments.
Scope of the report and coverage parameters
This report covers global market sizing, volumetric shipment analysis, and strategic forecasting for the Glass Tableware Market from 2026 through 2033. Geographical coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East, with explicit exclusions for industrial flat glass and laboratory glassware sectors.
Recent developments, strategic partnerships, and product launches
Recent industry momentum highlights strategic moves by key players, such as Fiskars Group expanding sustainable dining portfolios and Krosno Glass S.A. investing in automated eco-crystal production lines. These initiatives reflect a broader industry commitment to reducing carbon intensity while meeting modern consumer design preferences.