What is the baseline market overview and industry significance of the Phosphate Rock Market?
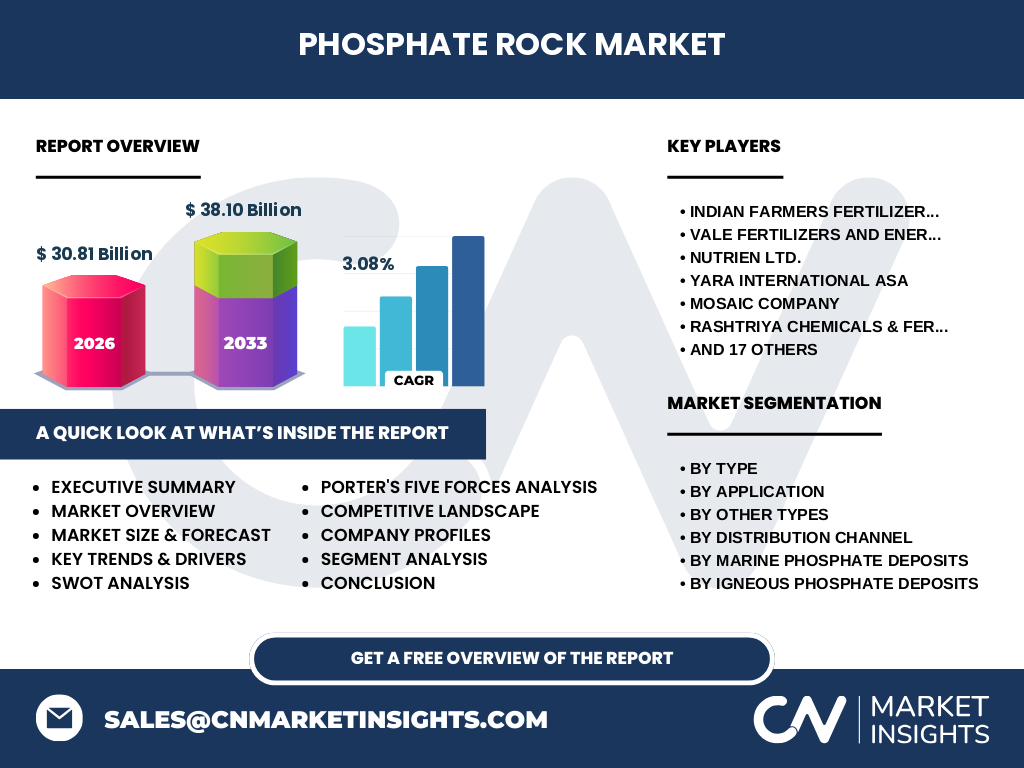
Our analysis indicates that the Phosphate Rock Market achieved a valuation of $30.81 Billion in 2026. This critical sector underpins global agricultural productivity and industrial chemistry, serving as the primary source of phosphorus for fertilizers, animal nutrition, and advanced chemical manufacturing across multiple continents.
What are the structural growth drivers, restraints, challenges, and opportunities shaping the Phosphate Rock Market?
The market is driven by escalating global food security demands and intensive agricultural practices. However, stringent environmental regulations on heavy metal impurities like cadmium constrain raw material extraction. Growth opportunities lie in beneficiation technologies that upgrade lower-grade sedimentary deposits for commercial viability.
Emerging trends and growth patterns in the Phosphate Rock Market
Industry trends highlight a decisive shift toward high-purity phosphoric acid production for lithium-ion battery cathode precursors. Major producers are investing heavily in water recycling and gypsum waste management to align with circular economy mandates and stringent ESG benchmarks.
How did the COVID-19 pandemic impact the Phosphate Rock Market and its subsequent recovery trajectory?
Pandemic-induced supply chain disruptions caused temporary port congestion and logistical bottlenecks for bulk maritime shipments. Recovery has been robust, accelerated by surging post-pandemic crop prices which incentivized aggressive fertilizer applications and restored mining output to pre-crisis levels.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics in the Phosphate Rock Market
The landscape features high market concentration led by state-backed giants and integrated multinationals. State-owned entities like OCP Group and PhosAgro dominate export volumes, while vertically integrated players like The Mosaic Company and Nutrien Ltd. control substantial captive reserves to hedge against feedstock volatility.
Executive Summary: High-level synthesis of key findings about the Phosphate Rock Market
Our comprehensive evaluation confirms the Phosphate Rock Market is poised for steady expansion, supported by agricultural necessity. Strategic consolidation, logistical optimization, and technological adaptations to declining ore grades will dictate competitive positioning through the next decade.
Market forecast trajectory from 2027 to 2033
Based on our research, the sector is projected to expand from $38.10 Billion by 2033, registering a steady compound annual growth rate of 3.08% over the forecast period, driven by sustained fertilizer consumption in emerging economies.
Segmentation analysis breakdown and market roles
The market segments by type into Marine Phosphate Deposits, Igneous Phosphate Deposits, and Other Types including sedimentary and weathered variations. Applications span Fertilizers, food and feed additives, and industrial uses, while distribution channels are divided between online and offline networks.
Geographic distribution and performance across regional territories
Regional performance varies significantly based on domestic arable land and industrial infrastructure. North America and the Middle East maintain strong production footprints, whereas Asia-Pacific dominates consumption patterns due to intensive farming practices in regional agricultural hubs.
In-depth regional review of key markets
North America benefits from highly mechanized mining operations led by major domestic enterprises. Meanwhile, North African territories anchored by Misr Phosphate and OCP Group leverage vast sedimentary reserves and strategic maritime access to supply European and Asian agricultural markets efficiently.
Strategic positioning of leading companies in the Phosphate Rock Market
Industry leaders deploy distinct strategies to maintain dominance. Yara International ASA and ICL Group focus on specialty downstream nutrient solutions, whereas Vale Fertilizers and Energy Ltd. and EuroChem Group AG leverage large-scale raw material extraction to secure low-cost feedstock advantages.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers is moderate-to-high due to the localized nature of high-grade phosphate rock reserves. Threat of new entrants remains low owing to extreme capital expenditure requirements, environmental licensing hurdles, and the specialized logistics needed for bulk raw material transport.
SWOT analysis of the sector
Strengths include irreplaceable agricultural utility and massive captive reserves among top producers. Weaknesses involve high carbon footprints and radioactive gypsum byproduct management. Opportunities exist in specialty chemical markets, while threats stem from strict environmental compliance and geopolitical trade restrictions.
Value chain analysis and industry structure
The value chain initiates with geological exploration and open-pit or underground extraction. Raw ore undergoes beneficiation—crushing, washing, and froth flotation—before reacting with sulfuric acid to produce phosphoric acid, ultimately flowing downstream to fertilizer manufacturers and industrial end-users.
Investment insights and high-potential areas
Strategic investment opportunities are concentrated in beneficiation technologies capable of upgrading low-grade ores and extracting rare earth elements as valuable byproducts. Companies investing in proprietary green-phosphoric acid production processes will capture outsized market share.
Conclusion and key takeaways for stakeholders
Stakeholders must navigate tightening environmental regulations while capitalizing on steady agricultural demand. Long-term success favors integrated operators utilizing advanced processing technologies to extract maximum value from diminishing high-grade rock deposits.
Research methodology and data triangulation
Baseline estimates are meticulously triangulated by cross-referencing global trade registry data, customs import-export logs, primary stakeholder interviews with mining executives, and secondary macroeconomic indicators regarding agricultural output and fertilizer consumption.
Scope of the report, coverage parameters, and analytical limitations
This report covers global production, trade flows, and consumption trends from historical baselines through the 2027 to 2033 forecast. Limitations include potential delays in official government mining disclosures and unannounced state-level export quota adjustments.
Recent developments, corporate announcements, and strategic partnerships
Recent industry moves feature strategic joint ventures aimed at securing green ammonia supplies for downstream fertilizer synthesis. Key players like Coromandel International Limited and Hubei Xingfa Chemicals Group Co Ltd. have expanded processing capacities to target high-margin industrial and electronic-grade phosphoric acid applications.