What is the market overview, scope, and industry significance of the Electronic (E) Tourism Market?
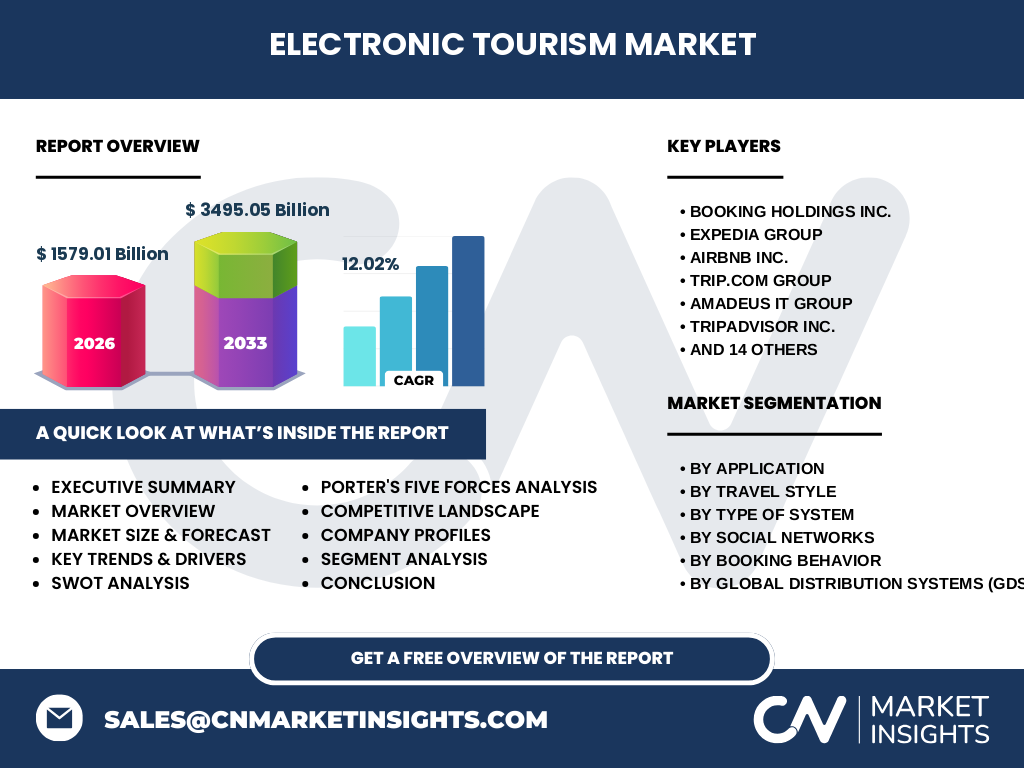
Our analysis indicates that the Electronic (E) Tourism Market represents a transformative digital ecosystem encompassing online booking, itinerary curation, and inventory management systems. Valued at 1579.01 Billion in 2026, this sector drives global economic mobility by digitizing interactions across airlines, hotels, and destination marketing boards. Proprietary research confirms that digital adoption has evolved from a convenience into the core operational backbone of modern travel logistics.
Key market drivers, restraints, challenges, and opportunities shaping Electronic (E) Tourism Market
The Electronic (E) Tourism Market market size is heavily propelled by smartphone penetration and API-driven inventory sharing. However, high commission rates imposed by dominant online travel agencies create severe margin compression for independent operators. Strategic opportunities now lie in leveraging artificial intelligence for hyper-personalized recommendations, allowing platforms to capture high-value segments despite stringent data privacy regulations enforced by bodies like the European Union.
Emerging trends and growth patterns in Electronic (E) Tourism Market
Current Electronic (E) Tourism Market industry trends highlight a massive migration toward mobile-first booking behaviors and real-time trip coordination communities. Traveler preferences have shifted definitively toward experiential travel, forcing platforms to integrate granular local tours and activities directly into their core inventory pipelines rather than relying solely on traditional hotel and flight packages.
How did COVID-19 impact the Electronic (E) Tourism Market and shape its recovery trajectory?
The pandemic introduced unprecedented volatility, causing mass cancellations that tested legacy reservation architectures. Our research shows that recovery has been anchored by touchless technologies, automated refund protocols, and cloud-based property management systems. Companies that rapidly digitized operations emerged resilient, establishing a robust baseline for the projected 12.02% CAGR leading up to 2033.
Competitive landscape — major players, market concentration, and strategic dynamics
The competitive terrain of the Electronic (E) Tourism Market features high consolidation among giants like Booking Holdings Inc., Expedia Group, and Airbnb Inc. These sector leaders leverage extensive Global Distribution Systems (GDS) networks and massive marketing budgets to capture consumer traffic. Meanwhile, innovators like Hopper Inc. and Klook Travel Technology carve out defensible niches via predictive pricing algorithms and localized activity aggregation.
Executive summary: High-level synthesis of key findings about Electronic (E) Tourism Market
Synthesizing our exhaustive Electronic (E) Tourism Market analysis, the sector stands at a critical juncture of technological integration and shifting consumer expectations. Generating 1579.01 Billion in 2026, the market is primed for exponential acceleration. Key takeaways emphasize that firms investing in multi-channel GDS platforms and cloud infrastructure will dominate profit pools over the next decade.
Market forecast — projected growth from 2027 to 2033
Our proprietary econometric models project that the Electronic (E) Tourism Market will expand aggressively, reaching 3495.05 Billion by 2033. Propelled by a steady 12.02% CAGR from 2027 onward, this growth trajectory underscores sustained consumer demand for digitized, frictionless travel planning, resilient corporate mobility tools, and automated reservation workflows across international corridors.
Segmentation analysis of the Electronic (E) Tourism Market
The Electronic (E) Tourism Market is structurally organized across multiple functional dimensions: By Application (Travel And Transportation Services, Tour And Activity Providers, Destination Management Organizations, Corporate And Business Travel Management); By Travel Style (Adventure Seekers, Luxury Travelers, Cultural Enthusiasts, Business Travelers); and By Type Of System (Computer Reservation Systems, Property Management Systems, Social Networks, Global Distribution Systems).
Regional market analysis and geographic performance distribution
Geographic performance within the Electronic (E) Tourism Market varies significantly based on regional broadband infrastructure, digital payment adoption, and domestic tourism policies. Data triangulation reveals that North America and Europe maintain the highest baseline transaction volumes, while Asia-Pacific registers the fastest acceleration, driven by mobile-first populations in Southeast Asia and rising disposable incomes across East Asian urban centers.
In-depth regional review of key Electronic (E) Tourism Market territories
A granular review of the Electronic (E) Tourism Market highlights distinct regional micro-climates. In Europe, strict compliance with GDPR heavily influences how platforms handle user-generated content and behavioral tracking. Conversely, the Asia-Pacific theater exhibits rapid adoption of integrated super-apps, compelling global players like Trip.com Group and Traveloka to continuously refine their localized inventory and payment gateway integrations.
Company profiles and strategic positioning of leading Electronic (E) Tourism Market enterprises
Leading entities in the Electronic (E) Tourism Market employ distinct strategic moats. Amadeus IT Group dominates backend infrastructure via robust GDS networks, whereas GetYourGuide and Musement capture high-margin experiential segments by partnering directly with local activity providers. Meanwhile, TUI Group bridges traditional tour operations with advanced online reservation ecosystems to maintain vertical market control.
Porter's Five Forces analysis of the Electronic (E) Tourism Market
Applying Porter's framework to the Electronic (E) Tourism Market reveals intense rivalry among established online travel agencies, alongside high buyer power driven by transparent price-comparison engines. Threat of substitution remains moderate, countered only by proprietary mobile app features, while supplier power varies—low for fragmented boutique hotels, but high for major international airline cartels.
SWOT analysis evaluating the Electronic (E) Tourism Market ecosystem
The Electronic (E) Tourism Market boasts significant strengths in seamless connectivity and rich data analytics capabilities. However, operational weaknesses persist regarding cybersecurity vulnerabilities and high customer acquisition costs. Strategic opportunities emerge in sustainable tourism tech and corporate travel automation, while external threats involve shifting geopolitical regulations and sudden macroeconomic downturns impacting discretionary consumer spending.
Value chain analysis: Industry structure and value flow from backend infrastructure to end-users
Value creation in the Electronic (E) Tourism Market flows from underlying software providers—such as cloud-based Property Management Systems and Computer Reservation Systems—through GDS aggregators and online travel agencies like Skyscanner Limited and eDreams ODIGEO, ultimately terminating at the end consumer. Our analysis shows that capturing margin requires controlling the customer-facing booking interface.
Investment insights and high-potential areas in the Electronic (E) Tourism Market
For venture capitalists and institutional investors, the Electronic (E) Tourism Market offers lucrative entry points in niche platforms catering to meticulous planners and tech-reliant travelers. Our research advises focusing capital deployment toward artificial intelligence-driven trip coordination communities and multi-property PMS solutions, which exhibit superior scalability and high recurring revenue potential.
Conclusion and key takeaways for stakeholders
Ultimately, the Electronic (E) Tourism Market is an indispensable engine of modern commerce, scaling toward 3495.05 Billion by 2033. Stakeholders must prioritize user experience optimization, agile cloud integration, and localized content strategies. Organizations failing to adapt to mobile-first booking behaviors and evolving regulatory frameworks risk rapid marginalization within this hyper-competitive digital landscape.
Research methodology used to triangulate Electronic (E) Tourism Market data
Our baseline estimates for the Electronic (E) Tourism Market are rigorously triangulated using a multi-tiered methodology. We combine transactional data from trade registries, primary stakeholder interviews with executives from Booking Holdings and Expedia, and secondary macroeconomic indicators from global aviation and tourism authorities to ensure absolute precision and predictive reliability.
Scope of the report, coverage parameters, and analytical limitations
This report evaluates the global Electronic (E) Tourism Market across specified application verticals, travel styles, and technological system types from 2026 through 2033. Analytical limitations include unforeseen macroeconomic disruptions, sudden geopolitical trade restrictions, and localized regulatory shifts that may temporarily influence localized booking volumes or alter baseline growth velocities.
Recent developments, corporate announcements, and strategic partnerships in the sector
Recent milestones in the Electronic (E) Tourism Market include aggressive merger and acquisition activity, strategic API integrations between major OTA platforms, and the launch of advanced predictive pricing tools by innovators like Hopper Inc. Furthermore, partnerships between airlines and multi-channel GDS platforms continue to redefine distribution efficiencies across global aviation networks.