What is the scope and industry significance of the Crash Barrier Systems Market?
Our analysis indicates the Crash Barrier Systems Market represents a critical infrastructure safeguard valued at 7.80 Billion in 2026. This sector encompasses portable and fixed installations designed to prevent vehicular incursions into hazardous zones, leveraging heavy raw materials like high-grade steel, reinforced concrete, and advanced polymers.
What are the key market drivers, restraints, challenges, and opportunities shaping the sector?
Rapid urbanization and stringent MASH and EN 1317 roadside safety mandates act as primary market drivers. However, volatile alloy pricing for steel and concrete raw materials creates margin compression. Growth opportunities lie in integrating smart sensor technologies into median and work-zone barriers to monitor structural integrity.
Structural Growth Drivers and Emerging Trends
The shift toward energy-absorbing semi-rigid and flexible wire rope systems is redefining highway safety. State departments of transportation increasingly prioritize modular, portable water-filled and steel barriers that minimize installation downtime during heavy highway construction and bridge maintenance.
How did COVID-19 impact the Crash Barrier Systems Market and drive the recovery trajectory?
Pandemic-era supply chain disruptions and logistical bottlenecks temporarily halted major infrastructure projects. As economies rebounded, stimulus-backed highway modernization initiatives accelerated demand, propelling the industry toward its robust long-term valuation targets.
Competitive Benchmarking and Industry Concentration
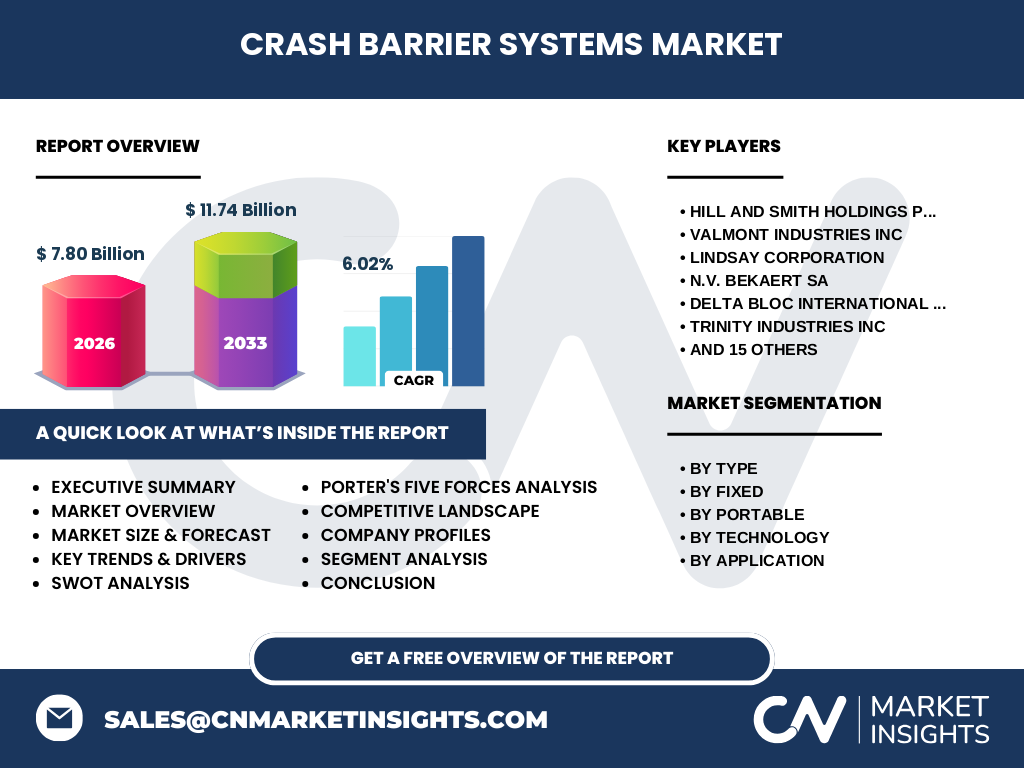
The competitive landscape features industry leaders like Hill and Smith Holdings PLC, Valmont Industries Inc, and Lindsay Corporation driving market consolidation through proprietary crash-cushion innovations and international acquisitions, maintaining high entry barriers for regional players.
Executive Summary of the Crash Barrier Systems Market
Driven by global highway expansion, our proprietary research establishes that the Crash Barrier Systems Market is poised for steady accumulation, underpinned by strict government regulations governing roadside and bridge safety applications across emerging economies.
Projected Growth Trajectory from 2027 to 2033
Based on our macroeconomic forecasting models, the market is projected to expand from 7.80 Billion in 2026 to reach 11.74 Billion by 2033. This expansion progresses at a steady 6.02% CAGR, fueled by public-private partnerships in transport infrastructure.
Segmentation Analysis of Crash Barrier Systems
The market categorizes by type into Portable (water-filled, steel, plastic) and Fixed (concrete, steel beam, wire rope) barriers. Technology segments span rigid, semi-rigid, and flexible designs deployed across roadside, median, work-zone, and bridge applications.
Geographic Distribution and Regional Performance
Regional performance varies based on local Department of Transportation spending. North America and Europe dominate through stringent safety compliance, while Asia-Pacific exhibits the fastest growth due to massive expressway construction projects in rapidly expanding urban corridors.
In-Depth Regional Review and Localized Market Constraints
In North America, federal funding acts as a key catalyst, whereas European markets focus heavily on eco-friendly, aesthetically integrated wire rope systems. Developing regions face logistical hurdles with raw material transport, favoring localized concrete barrier production.
Strategic Positioning of Leading Companies
Market participants such as Trinity Industries Inc, N.V. Bekaert SA, and DELTA BLOC International GmbH leverage specialized portfolios ranging from high-containment concrete molds to proprietary wire rope innovations, capturing high-margin municipal contracts worldwide.
Porter's Five Forces Analysis of Competitive Dynamics
Supplier power remains moderate due to standardized steel and cement inputs. However, buyer power is consolidated among state transport agencies, while the threat of substitution from autonomous vehicle sensor guidance remains low due to mandatory physical containment requirements.
SWOT Analysis: Internal Strengths and External Realities
Strengths include robust product durability and mandatory regulatory compliance. Weaknesses involve high transportation costs for heavy fixed concrete units. Opportunities emerge in smart highway integration, while threats stem from raw material price volatility impacting profit margins.
Value Chain Analysis from Raw Materials to End-Users
The value flow originates with raw alloy steel, cement, and polymer extraction. Mid-stream fabricators like Armco Barrier and A-Safe Ltd process these into certified crash-tested modules, distributed via specialized logistics networks to civil contractors and municipal highway departments.
Investment Insights and High-Potential Areas
Investors should target manufacturers specializing in modular, reusable portable steel and polymer barriers. These segments offer superior margins by reducing recurring labor and replacement costs for highway contractors managing high-frequency work-zone zones.
Conclusion and Strategic Takeaways
The Crash Barrier Systems Market offers compelling growth avenues driven by strict safety mandates and global infrastructure investments. Companies balancing technological innovation in energy absorption with localized manufacturing will capture outsized market share.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining international trade registry data, primary stakeholder interviews with civil engineering executives, and secondary macroeconomic indicators from global transport authorities to ensure absolute analytical precision.
Scope of the Report and Coverage Parameters
This report covers global revenue trends, volume shipments, and technological evaluations across fixed and portable segments from 2026 to 2033. Excluded from this scope are off-road industrial guardrails utilized exclusively within private manufacturing warehouse perimeters.
Recent Industry Developments and Strategic Moves
Recent strategic moves include Valmont Industries Inc acquiring regional distribution channels and Lindsay Corporation launching advanced MASH-compliant gating systems, reflecting an industry-wide push toward enhanced vehicular redirection efficiency and modular adaptability.