What is the scope and industry significance of the Apparel Re-Commerce Market?
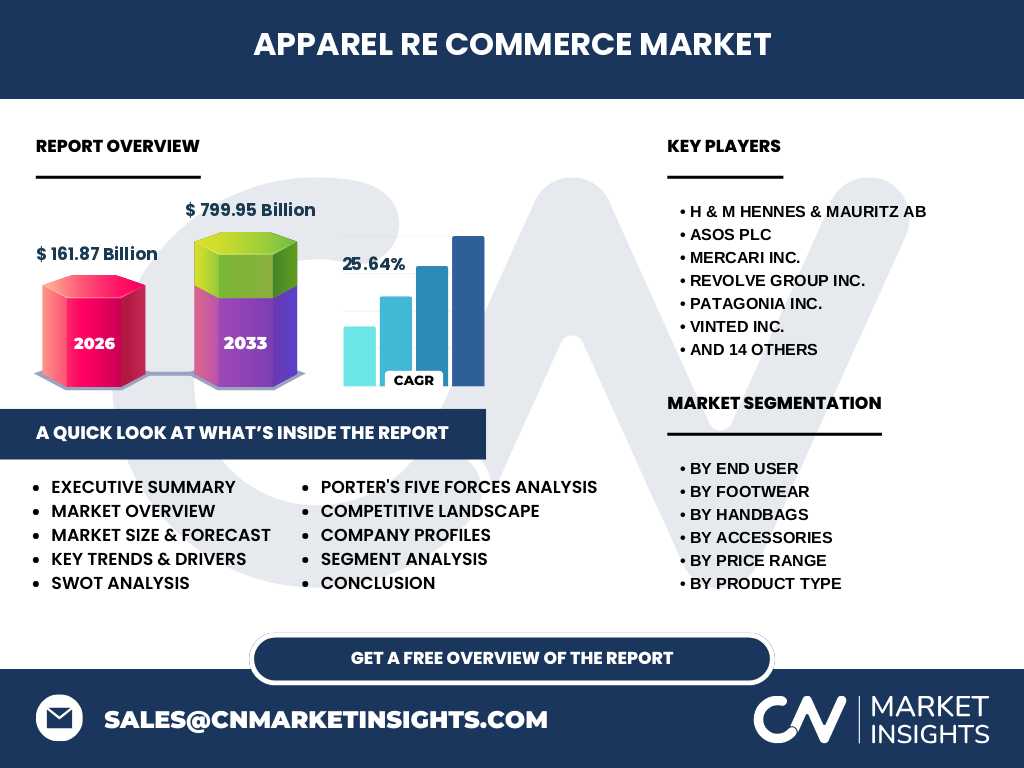
Our analysis indicates that the Apparel Re-Commerce Market market size reaches 161.87 Billion in 2026. This sector encompasses the secondary trade of pre-owned garments, footwear, and accessories, driven by circular economy mandates and shifts in consumer spending toward sustainable luxury and value-driven wardrobes.
Key market drivers, restraints, challenges, and opportunities shaping Apparel Re-Commerce Market
Growth is accelerated by eco-conscious consumer behavior and inflation, though high logistical reverse-supply chain costs remain a key operational restraint. Companies navigating these hurdles unlock massive opportunities in authenticated luxury resale, particularly as raw material scarcity elevates primary retail pricing.
Emerging trends and growth patterns in Apparel Re-Commerce Market
The shift toward white-label resale infrastructure allows traditional brands to internalize secondary market revenue. This trend is reshaping inventory flows, favoring platforms capable of rapid authentication for luxury items and seamless trade-in mechanisms.
How did the COVID-19 pandemic affect the Apparel Re-Commerce Market and its recovery trajectory?
Lockdowns severely disrupted traditional offline thrift store operations, forcing a rapid digitization of resale channels. This catalyst permanently accelerated online platform adoption, resulting in a robust post-pandemic recovery characterized by heightened digital engagement and venture-backed consolidation.
Competitive benchmarking and strategic dynamics in the Apparel Re-Commerce Market
The market features intense competition between specialized platforms and peer-to-peer applications. Industry leaders like ThredUp Inc. and The RealReal Inc. leverage proprietary automated pricing and authentication technologies to secure defensible moats against horizontal contenders like Mercari Inc. and Poshmark Inc.
Executive summary of key findings within the Apparel Re-Commerce Market industry trends
Valued at 161.87 Billion in 2026, the Apparel Re-Commerce Market industry trends point toward exponential expansion, projected to skyrocket to 799.95 Billion by 2033 at a staggering 25.64% CAGR, upending traditional linear retail models.
Market forecast trajectory from 2027 to 2033
Based on our research, the market will scale aggressively from its 2026 baseline to reach 799.95 Billion by 2033, expanding at a compound annual growth rate of 25.64%. This trajectory is fueled by widespread demographic shifts among Gen Z and Millennial shoppers.
Segmentation analysis across product types, price ranges, and distribution channels
Segmentation spans End User (Adult, Kids), Footwear (Athletic, Casual, Formal, Boots, Sandals), Handbags (Totes, Shoulder, Crossbody, Clutches, Backpacks), Accessories, Price Range (Premium, Mid-Range, Value), and Business Models (C2C, B2C). Each segment plays a vital role in capturing distinct consumer discretionary budgets.
Geographic distribution and regional performance in the Apparel Re-Commerce Market analysis
Regional performance varies widely based on localized regulatory frameworks and logistics infrastructure. North America and Europe currently dominate transaction volumes, while Asia-Pacific emerges as the fastest-growing frontier due to expanding digital penetration and urban middle-class populations.
In-depth regional review of high-performing secondary apparel hubs
North America benefits from mature logistics networks and established consumer trust in digital secondhand platforms. Meanwhile, European markets enforce stringent environmental directives regarding textile waste, incentivizing rapid adoption of circular fashion models championed by local enterprises.
Strategic positioning of leading companies in the Apparel Re-Commerce Market
Firms like Vinted Inc. and Depop Limited dominate peer-to-peer fashion through localized community-driven apps, whereas Vestiaire Collective S.A.S. and The RealReal Inc. capture the high-end luxury segment via rigorous physical authentication protocols.
Porter's Five Forces analysis of competitive pressures
Threat of new entrants remains high due to low initial software barriers, but network effects heavily favor established giants. Bargaining power of buyers is substantial given abundant alternative platforms, while supplier power is mitigated by the massive global surplus of unutilized consumer wardrobes.
SWOT analysis highlighting internal and external strategic factors
Strengths include extensive inventory variety and asset-light models. Weaknesses involve margin compression from fulfillment costs. Opportunities lie in brand-partnered resale programs, while threats include regulatory scrutiny over counterfeit goods and cross-border shipping friction.
Value chain analysis from primary raw materials to secondary end-users
The value chain starts with surplus consumer garments, flowing through collection, sorting hubs, digital cataloging, and authentication, before reaching end-users via online platforms or offline thrift stores managed by firms like Winmark Corporation and Buffalo Exchange Inc.
Investment insights and high-potential areas for capital allocation
Investors should target B2B software enablers providing automated garment grading, image recognition, and dynamic pricing algorithms. These technological solutions directly address the labor-intensive unit economics plaguing traditional manual sorting facilities.
Conclusion and core takeaways for industry stakeholders
The trajectory toward 799.95 Billion by 2033 proves that re-commerce is a permanent structural shift. Retailers failing to integrate secondary options risk losing market share to agile platforms purpose-built for the circular economy.
Research methodology detailing data triangulation and baseline estimation
Our baseline estimates of 161.87 Billion for 2026 are triangulated by cross-referencing customs trade data, proprietary primary stakeholder interviews with executives from ThredUp Inc. and Poshmark Inc., and macroeconomic retail expenditure indicators.
Scope of the report and analytical coverage parameters
This report covers global apparel, footwear, handbag, and accessory re-commerce across C2C and B2C business models from 2026 to 2033. Excluded from this scope are raw textile manufacturing and primary-market fast-fashion retail channels.
Recent developments, strategic partnerships, and platform expansions
Recent market activities feature major fashion groups partnering directly with specialized tech enablers like LePrix Inc. to launch certified pre-owned storefronts, alongside cross-border acquisitions designed to scale logistics infrastructure across international shipping lanes.