What is the structural scope and industry significance of the Advertising, Public Relations, And Related Services Market?
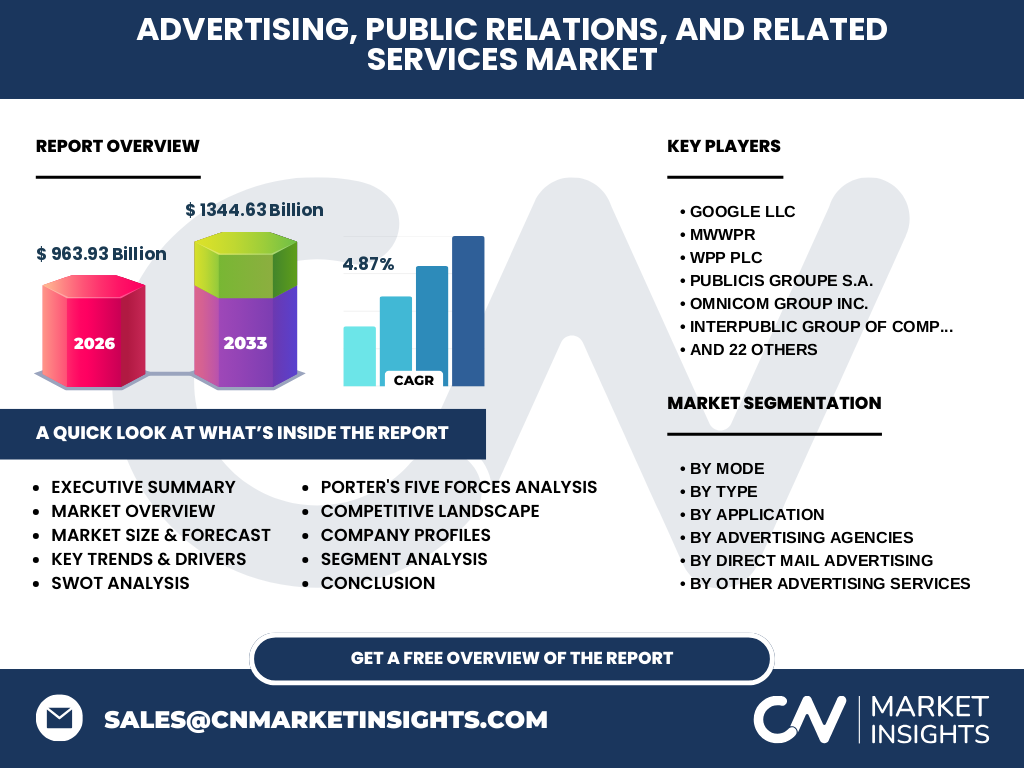
Our analysis indicates that the Advertising, Public Relations, And Related Services Market represents a foundational pillar of global commerce, valued at $963.93 Billion in 2026. This sector encompasses diverse promotional ecosystems—from digital programmatic networks managed by giants like Google LLC to specialized crisis communication firms such as FTI Consulting Inc. It bridges upstream creative capital and downstream consumer demand across BFSI, retail, and healthcare verticals.
Structural Growth Drivers and Market Restraints
The trajectory of the Advertising, Public Relations, And Related Services Market industry trends is heavily propelled by accelerated digital transformation and omnichannel media consumption. However, stringent regulatory frameworks enforced by bodies like the FTC and GDPR create logistical compliance hurdles. Privacy crackdowns restrict third-party data harvesting, forcing enterprises to rely on proprietary first-party consumer insights.
Emerging Trends Reshaping the Advertising, Public Relations, And Related Services Market
The shift toward hyper-personalized experiential marketing and AI-driven media planning is redefining agency operations. Innovators like Outbrain Inc. and Meltwater Group AS leverage machine learning for predictive sentiment analysis. Simultaneously, brands demand verifiable ROI, accelerating the migration of ad spend away from legacy print toward interactive digital and programmatic channels.
How did the COVID-19 pandemic permanently alter sector dynamics?
The pandemic triggered an unprecedented contraction in global marketing budgets during 2020, forcing rapid restructuring across traditional billboard and print distribution channels. Yet, the recovery trajectory proved robust, as remote work environments catalyzed e-commerce adoption. This accelerated digital migration permanently shifted corporate outlays toward performance-driven online advertising and agile public relations strategies.
Competitive Benchmarking and Strategic Dynamics
Industry consolidation remains intense, dominated by holding conglomerates including WPP plc, Publicis Groupe S.A., Omnicom Group Inc., and Interpublic Group of Companies Inc. These titans acquire boutique tech platforms and data analytics providers to maintain competitive advantage. Concurrently, independent agencies carve out defensible niches by offering hyper-specialized crisis management and localized cultural consulting.
Executive Summary of Key Industry Findings
Our comprehensive audit reveals an industry at a major strategic inflection point, driven by technological integration and shifting consumer habits. The global Advertising, Public Relations, And Related Services Market analysis underscores the imperative for omnichannel agility. Agencies that successfully fuse creative storytelling with robust data intelligence will capture disproportionate market share through 2033.
Market Forecast and Long-Term Projections through 2033
Based on our econometric modeling, the market is projected to expand from $963.93 Billion in 2026 to reach $1344.63 Billion by 2033. This expansion represents a steady compound annual growth rate (CAGR) of 4.87%. This consistent upward trajectory is sustained by emerging market urbanization and escalating digital ad spend across the Asia-Pacific and Latin American regions.
Comprehensive Segmentation Analysis
The market divides by mode into Online and Offline channels. By type, it spans Advertising Agencies, Billboard & Outdoor Advertising, Media Buying Agencies, Print Advertising Distribution, and Direct Mail. Application verticals include BFSI, Consumer Goods and Retail, Government, IT & Telecom, Healthcare, and Media & Entertainment, each exhibiting unique spending sensitivities.
Geographic Distribution and Regional Performance
North America retains the largest revenue share, underpinned by high digital penetration and massive corporate advertising budgets. Meanwhile, Asia-Pacific emerges as the fastest-growing regional market, fueled by rapid smartphone adoption in Southeast Asia and booming retail media networks across metropolitan hubs in India and China.
In-Depth Regional Review of Operational Constraints
Regional performance varies due to distinct logistical hurdles and localized regulatory oversight. European markets navigate strict data sovereignty laws under the European Commission, compelling agencies like Havas PR and Kreab Gavin Anderson to prioritize privacy-compliant analytics. Conversely, North American firms focus on programmatic scale and fast-paced retail media integration.
Strategic Positioning of Leading Market Participants
Major conglomerates deploy distinct plays: Dentsu Inc. and Havas PR optimize cross-border media harmonization, while specialized tech enablers like Cision AB, Agility PR Solutions, and Onalytica provide indispensable PR monitoring infrastructure. Boutique firms like Coyne PR and APCO Worldwide leverage deep sector expertise to defend client reputation amid volatile digital cycles.
Porter's Five Forces Analysis of Competitive Intensity
The threat of new entrants is moderate, balanced by high client acquisition costs and proprietary tech barriers. Rivalry among established holding groups is fierce, driving margin compression. Supplier power remains low given the abundance of media inventory, whereas buyer power is high, with enterprise clients demanding transparent, performance-based pricing models.
SWOT Analysis of the Global Industry Landscape
Key strengths include robust creative talent and deep enterprise relationships. Primary weaknesses involve vulnerability to macroeconomic downturns. Significant opportunities lie in generative AI content creation and emerging virtual reality platforms. Critical threats encompass tightening data privacy regulations and ad-blocking technologies.
Value Chain Analysis and Industry Structure
The industry value chain flows from raw intellectual capital and consumer data inputs through creative ideation and media planning stages. Execution involves distribution via transit billboards, digital networks, or direct mail catalogs, ultimately reaching end-users across diverse application verticals to drive measurable commercial conversion.
Investment Insights and High-Potential Growth Pockets
Investors should target niche martech SaaS platforms specializing in automated PR attribution and first-party data management, such as AirPR software and TrendKite. High-potential areas also include experiential marketing and digital billboard infrastructure in high-traffic urban transit corridors across developing economies.
Conclusion and Strategic Takeaways for Stakeholders
Navigating the future of the Advertising, Public Relations, And Related Services Market requires continuous adaptation to algorithmic shifts and privacy mandates. Organizations that proactively integrate advanced data analytics with resonant creative messaging will outperform peers and secure long-term profitability through the 2033 forecast horizon.
Methodological Framework for Market Sizing
Our research methodology triangulates data using a rigorous mix of primary stakeholder interviews with agency executives, secondary analysis of trade registry data, and macroeconomic indicators. Baseline estimates are continuously validated against quarterly financial disclosures from publicly traded industry leaders.
Scope of the Report and Analytical Parameters
This report evaluates global market dynamics for the Advertising, Public Relations, And Related Services Market from 2026 to 2033. Coverage parameters encompass all primary operating modes, agency classifications, and end-user application verticals, excluding informal peer-to-peer marketing initiatives and unregulated underground promotional networks.
Recent Industry Developments and Strategic Moves
Recent market activity highlights aggressive M&A maneuvers, strategic cross-border partnerships, and proprietary AI product launches. Firms like Meltwater Group AS and Cision AB continually upgrade their PR software suites, while holding groups restructure operations to streamline digital service delivery for multinational clients.