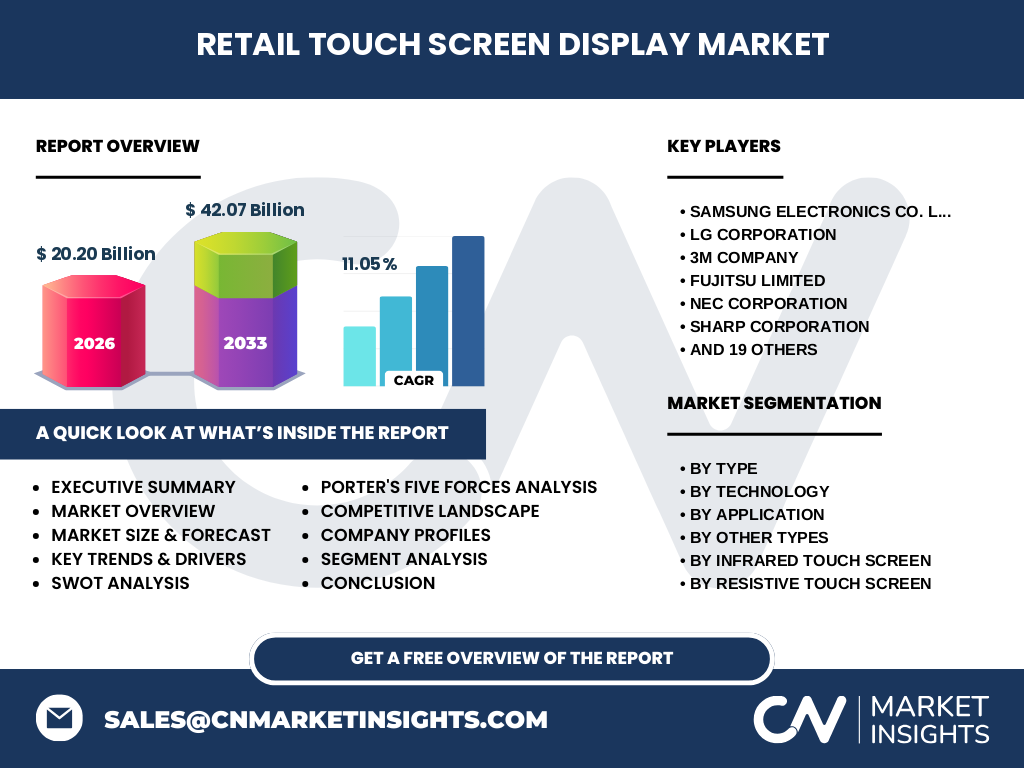
Market overview of the Retail Touch Screen Display Market
Our analysis indicates that the Retail Touch Screen Display Market represents a foundational pillar of modern commercial infrastructure, valued at $20.20 Billion in 2026. This sector encompasses advanced interactive hardware enabling seamless omnichannel consumer touchpoints. Driven by semiconductor fabrication and glass manufacturing innovations from key innovators like Corning Incorporated, the industry facilitates digitized customer engagement across global retail ecosystems.
Structural Growth Drivers and Restraints in Retail Touch Screen Display Market
The market thrives on accelerated automation and labor optimization within brick-and-mortar storefronts. However, supply chain bottlenecks for rare earth elements required in Projected Capacitive Touch Screens (PCAP) act as notable restraints. Despite logistical hurdles, rising demand for contactless shopping experiences continues to fuel robust expansion across all retail touchpoints.
Emerging trends and growth patterns in Retail Touch Screen Display Market
Industry trends highlight a decisive pivot toward organic light-emitting diode (OLED) technologies and multi-touch resistive screens. Retailers increasingly deploy Retail Brand Experience Tables and interactive point of purchase units to bridge online and physical shopping. This shift rewards agile display manufacturers capable of integrating high-durability sensors under stringent environmental standards.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically accelerated touchless retail adoption, temporarily depressing standard Point Of Sale (POS) equipment sales while spiking demand for hygienic Automated Teller Machine (ATM) interfaces. Our research confirms a V-shaped recovery trajectory as physical retail re-engineered store layouts, prioritizing robust, antimicrobial-coated touch interfaces to restore consumer confidence.
Competitive Benchmarking: Major Players and Market Concentration
The competitive landscape features high concentration among multinational conglomerates like Samsung Electronics Co. Ltd., LG Corporation, and Sharp Corporation. Strategic differentiation relies on proprietary matrix infrared touch screens and ultra-thin bezel designs. Meanwhile, specialists like Elo Touch Solutions Inc. and Planar Systems Inc. secure lucrative niches by tailoring ruggedized hardware for high-traffic retail corridors.
Executive summary of key findings for Retail Touch Screen Display Market
The data underscores exceptional growth, projecting the market to surge from $20.20 Billion in 2026 to $42.07 Billion by 2033 at a robust 11.05% CAGR. Strategic opportunities concentrate in advanced capacitive-resistive hybrid touch screens and interactive point of purchase deployments, demanding immediate capital allocation from forward-thinking retail technology stakeholders.
Market forecast trajectory from 2027 to 2033
Driven by widespread self-service checkout adoption, our forecast models explosive momentum, expanding the market from its 2026 baseline to $42.07 Billion by 2033. Achieving an 11.05% CAGR, growth will be heavily anchored by commercial rollouts of surface capacitive and active infrared touch screens across major metropolitan retail hubs.
Segmentation analysis across core architectural categories
Market segmentation spans multiple technological tiers: By Type covers Resistive, Capacitive, and Infrared Touch Screens; By Technology encompasses Liquid-Crystal Display (LCD), Light-Emitting Diode (LED), and Organic Light-Emitting Diode (OLED); By Application features Interactive Point of Purchase (IPOP), Retail Brand Experience Tables, POS Equipment, and ATMs, each serving distinct commercial requirements.
Regional market analysis and geographic distribution
Geographic performance varies significantly based on local retail automation maturity. North America and Asia-Pacific dominate consumption, fueled by dense deployments of self-service kiosks and advanced POS infrastructure. Emerging markets in Latin America and MEA display accelerating growth trajectories, underpinned by expanding organized retail networks and rising consumer digitization.
In-depth regional review of key commercial hubs
Asia-Pacific leads global manufacturing and deployment, anchored by display giants AUO Corporation and Innolux Corporation alongside major component suppliers. Concurrently, North America prioritizes software-hardware integration, demanding sophisticated Projected Capacitive Touch Screens (PCAP) to power frictionless checkout lanes and immersive retail brand experience installations.
Company profiles and strategic positioning of industry leaders
Market leaders leverage distinct competitive advantages: Advantech Co. Ltd. and Posiflex Technology Inc. dominate industrial-grade POS hardware, while Synaptics Incorporated pioneers advanced touch controller ICs. Companies like Planar Systems Inc. and ViewSonic Corporation focus on high-impact visual fidelity for retail signage, ensuring resilient positioning across diverse commercial segments.
Porter's Five Forces analysis of competitive intensity
Competitive rivalry is intense, driven by rapid technological commoditization and aggressive pricing from display manufacturers. Supplier power remains moderate, constrained by specialized glass and semiconductor availability from firms like Corning Incorporated. Meanwhile, buyer power is high, as enterprise retailers demand custom, durable configurations with stringent warranty terms.
SWOT analysis for the Retail Touch Screen Display Market
Strengths include high consumer familiarity and rapid transaction speeds. Weaknesses involve vulnerability to supply chain shocks for rare minerals. Opportunities lie in expanding interactive point of purchase displays in grocery and apparel sectors. Threats stem from macroeconomic inflationary pressures depressing discretionary commercial capital expenditures.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material extraction—including indium tin oxide and specialized glass substrates—followed by touch sensor fabrication, module assembly by firms like Amongo Display Technology (Shenzhen) Co. Ltd., and final system integration for deployment in retail point of sale terminals and automated teller machines.
Investment insights and strategic high-potential areas
Investors should target developers of flexible resistive screens and projected capacitive touch screens (PCAP), as these technologies address durability and multi-touch precision demands. Partnerships with established integrators like Elo Touch Solutions Inc. or Posiflex Technology Inc. offer optimal pathways to capture high-margin retail enterprise contracts.
Conclusion and key takeaways for industry stakeholders
The Retail Touch Screen Display Market offers exceptional expansion potential, scaling to $42.07 Billion by 2033 at an 11.05% CAGR. Success requires continuous innovation in OLED and interactive display technologies, aligning hardware durability with evolving omnichannel retail strategies to capture sustainable market share.
Research methodology utilizing triangulation and primary validation
Our research methodology combines exhaustive bottom-up and top-down data triangulation. Baseline estimates derive from trade registry data, customs import-export logs across major shipping ports, and primary stakeholder interviews with executives at Zytronic PLC, UICO LLC, and Fujitsu Limited, cross-referenced against macroeconomic indicators.
Scope of the report and analytical boundaries
This report covers global deployment parameters for the Retail Touch Screen Display Market across 2026 to 2033. Analysis is strictly bounded by commercial retail applications, excluding consumer electronics like smartphones and tablets, while evaluating hardware types, technology variations, and regional performance constraints.
Recent developments, strategic partnerships, and product launches
Recent industry momentum is defined by strategic alliances and technological rollouts. Companies like AOPEN Inc., Avalue Technology Inc., and Waveshare Electronics Ltd. have introduced modular touch displays optimized for harsh retail environments, while major players leverage joint ventures to secure resilient semiconductor supply chains for advanced PCAP manufacturing.