What is the Light Gauge Steel Framing Market overview, scope, and industry significance?
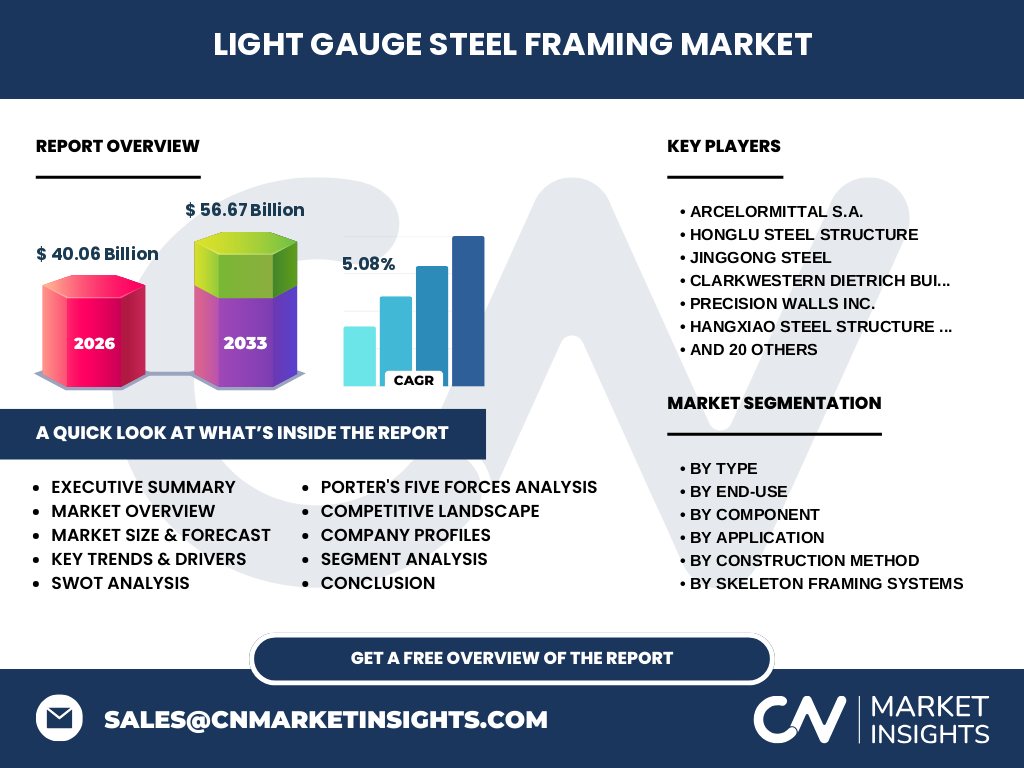
Our analysis indicates that the Light Gauge Steel Framing Market is valued at $40.06 Billion in 2026, underpinning modern sustainable construction. This sector utilizes cold-formed steel profiles like Steel Studs And Tracks and Trusses to replace timber, driven by stringent Eurocodes and IBC standards. Industry stalwarts such as ArcelorMittal S.A. and Tata BlueScope Steel Limited supply high-tensile coils processed through specialized roll-forming lines to ensure structural precision.
Key market drivers, restraints, challenges, and opportunities shaping Light Gauge Steel Framing Market
Structural growth is propelled by rapid urbanization and the scarcity of traditional lumber, yet volatile hot-rolled coil prices pose severe margin restraints. Compliance with OSHA and ISO standards creates logistical hurdles for on-site execution. However, massive opportunities lie in off-site prefabrication, where innovators like FRAMECAD Ltd. and Arkitech Advanced Construction Technologies leverage automated software-driven machinery to bypass skilled labor shortages.
Emerging trends and growth patterns in Light Gauge Steel Framing Market
The shift toward Modular Light Gauge Steel Construction is revolutionizing project delivery timelines across dense urban hubs. Contractors increasingly adopt Hybrid Skeleton Systems (LGSF with Secondary Structural Supports) to optimize seismic resistance and acoustic insulation. Intelligent Steel Solutions Ltd. and The Steel Network Inc. lead this trend by integrating BIM-enabled digital twins directly into automated cold-formed steel manufacturing ecosystems.
COVID-19 impact analysis on Light Gauge Steel Framing Market and the recovery trajectory
The pandemic severely fractured global supply chains, disrupting primary slab zinc and hot-rolled coil inputs essential for corrosion-resistant Galvanized Steel Studs. Despite initial jobsite shutdowns enforced by local health mandates, the recovery trajectory surged past pre-pandemic baselines. This rebound was accelerated by government-backed infrastructure stimulus packages favoring sustainable, low-carbon, and highly recyclable structural steel assemblies over traditional carbon-heavy concrete.
Competitive landscape — major players, market concentration, and strategic dynamics
The market features a moderately consolidated landscape where multinational giants compete alongside specialized regional roll-formers. Clarkwestern Dietrich Building Systems Ltd. and CEMCO-California Expanded Metal Products Inc. dominate North American distribution, while HONGLU STEEL STRUCTURE and HangXiao Steel Structure Co Ltd. command massive Asian fabrication footprints. Strategic dynamics center on localized supply chain integration and proprietary software-hardware ecosystems.
Executive summary of key findings about Light Gauge Steel Framing Market
Our comprehensive research forecasts the Light Gauge Steel Framing Market to reach $56.67 Billion by 2033, expanding at a robust 5.08% CAGR from 2027. Demand is overwhelmingly concentrated in commercial and multi-storey residential applications utilizing off-site prefabrication. Market leaders must focus on digital integration and strategic raw material sourcing to navigate fluctuating commodity tariffs and secure long-term profitability.
Market forecast and projected growth trajectory from 2027 to 2033
Growing at a steady 5.08% CAGR, the market will climb from its 2026 baseline to $56.67 Billion by 2033. This expansion is heavily anchored by the rapid adoption of Load- Bearing Steel Stud Systems in multi-storey residential developments. Regional growth will peak in developing economies where rapid urbanization demands scalable, fire-resistant, and termite-proof building alternatives to conventional masonry and timber.
Segmentation analysis of the Light Gauge Steel Framing Market
Market segmentation spans multiple categories designed to meet precise architectural demands. Skeleton Framing Systems and Load- Bearing Steel Stud Systems form the core structural backbone, while Long-Span Light Gauge Steel Systems address large open spaces. Components range from Joists And Beams to Panels And Frames, deployed across Wall Systems and Roof Systems via Off-Site Prefabricated LGSF methods.
Regional market analysis and geographic performance distribution
Geographic performance varies significantly due to local building codes, seismic activity, and timber availability. North America leads in adoption of panelized load-bearing systems, supported by rigorous ASTM standards. Meanwhile, Asia-Pacific represents the fastest-growing regional market, propelled by massive state-sponsored urban housing initiatives in countries like China and India, where companies such as Jinggong Steel scale production.
In-depth regional review of key markets in the Light Gauge Steel Framing Market
North America and Europe prioritize energy-efficient thermal break designs to comply with stringent LEED and nearly Zero-Energy Building mandates. In contrast, the Middle East market, supported by regional players like Genesis Manazil Steel Framing LLC, focuses on rapid, thermally resistant villa construction. Asia-Pacific leverages its vast manufacturing ecosystems, anchored by ports in Shanghai and Mumbai, to export prefabricated framing modules globally.
Company profiles and strategic positioning of leading industry participants
Market leaders utilize distinct competitive moats to capture share. Hadley Industries Ltd. and Metek plc focus on advanced roll-forming engineering for complex architectural geometries. In North America, Super Stud Building Products Inc. and MRI Steel Framing LLC leverage expansive distribution networks to serve commercial contractors efficiently, while Precision Walls Inc. excels in turnkey installation services.
Porter's Five Forces analysis of the Light Gauge Steel Framing Market
Bargaining power of suppliers is moderately high due to reliance on primary steel mills like ArcelorMittal S.A. Threat of substitutes remains low against timber in fire-prone regions, but high against concrete in low-rise structures. Competitive rivalry is intense among regional roll-formers, pushing firms to innovate in prefabrication software. Buyer power is mitigated by the specialized engineering expertise required for complex Cold-Formed Steel Truss Systems.
SWOT analysis highlighting strengths, weaknesses, opportunities, and threats
Strengths include exceptional strength-to-weight ratios and 100% recyclability. Weaknesses involve high initial tooling costs for bespoke profiles and thermal bridging issues. Opportunities abound in modular healthcare and educational facilities. Threats stem from macroeconomic steel tariff volatility and stringent local building code approval processes that delay commercial project deployment across municipal jurisdictions.
Value chain analysis from raw materials to end-users
The value chain initiates with primary steel producers supplying galvanized coils, which are processed by roll-formers into Steel Studs And Tracks or Joists And Beams. Fabricators then assemble these into Panels And Frames using Connectors And Fasteners. Distributors supply general contractors and real estate developers operating within the residential, commercial, and industrial end-use verticals.
Investment insights and high-potential areas in the industry
High-potential investment avenues center on automated off-site manufacturing plants and proprietary BIM design software integrations. Venture capital and private equity firms should target mid-tier fabricators adopting Modular Light Gauge Steel Construction technologies. Strategic partnerships with firms like The Steel Network Inc. offer superior risk-adjusted returns by capturing the high-margin pre-engineered construction segment.
Conclusion and key takeaways for stakeholders
Surpassing $56.67 Billion by 2033, the industry offers compelling growth for forward-thinking stakeholders. Success depends on embracing Off-Site Prefabricated LGSF and mastering complex regulatory compliance. Firms that integrate automated software with robust supply chain logistics will successfully outmaneuver raw material volatility and capture expanding commercial market share.
Research methodology used to triangulate baseline estimates and forecasts
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with executives from CEMCO and FRAMECAD, and secondary macroeconomic indicators from global construction bodies. We cross-reference cold-formed steel shipment volumes with regional building permit issuances to ensure absolute econometric accuracy.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics from 2026 through 2033, evaluating structural systems, components, applications, and construction methods. Limitations include unforeseen geopolitical trade restrictions on galvanized steel coils and sudden macroeconomic shifts impacting global commercial real estate investment flows and municipal zoning approvals.
Recent developments, company announcements, partnerships, and strategic moves
Recent industry momentum highlights aggressive capacity expansions and technological alliances. Companies such as Arkitech Advanced Construction Technologies have rolled out next-generation roll-forming machinery, while firms like E PACK Prefabricated Buildings Co Ltd. formed strategic partnerships to supply rapid-deployment modular camps across emerging infrastructure corridors in developing economies.