What is the scope and industry significance of the Non-Fungible Token (NFT) Gaming Market?
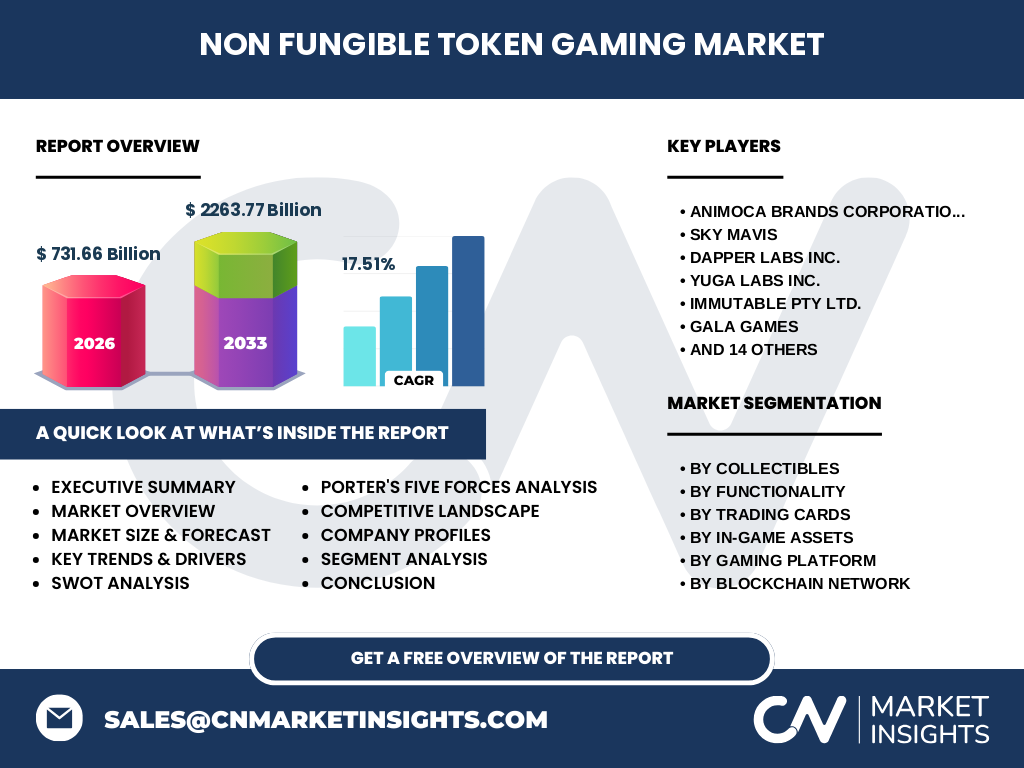
Our analysis indicates that the Non-Fungible Token (NFT) Gaming Market represents a paradigm shift in digital ownership, decentralizing asset control from centralized publishers to players. Valued at 731.66 Billion in 2026, this sector integrates blockchain rails with interactive entertainment, enabling true player-driven economies where virtual assets hold verifiable, real-world economic utility across global digital ecosystems.
Structural Growth Drivers and Restraints in the Non-Fungible Token (NFT) Gaming Market
The market is propelled by the integration of play-to-earn mechanics and interoperable digital assets, contrasted against regulatory friction from bodies like the SEC and fluctuating cryptocurrency valuations. Scalability bottlenecks on networks like Ethereum constrain transactional throughput, yet layer-2 scaling protocols are actively mitigating these infrastructural hurdles to sustain long-term enterprise expansion.
Emerging trends and growth patterns in Non-Fungible Token (NFT) Gaming Market industry trends
Recent Non-Fungible Token (NFT) Gaming Market industry trends highlight a decisive pivot toward utility-driven assets over speculative collectibles. Publishers increasingly deploy advanced in-game assets like weapons, armor, and virtual land parcels that offer cross-game functionality, heavily favored by innovators such as Animoca Brands and Gala Games.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically accelerated digital consumption, serving as a massive catalyst for virtual economies. While subsequent macroeconomic tightening induced a market correction, the recovery trajectory showcases robust institutional backing and sustained user engagement, cementing decentralized gaming as a permanent pillar of the interactive entertainment landscape.
Competitive Benchmarking: Major players and strategic dynamics
The competitive landscape features high concentration among pioneering studios like Sky Mavis, Dapper Labs Inc., and Yuga Labs Inc. Strategic dynamics revolve around proprietary blockchain integration, ecosystem lock-in, and cross-platform partnerships. Companies leveraging scalable networks like Polygon and Solana are rapidly gaining market share over legacy single-chain operators.
Executive Summary of the Non-Fungible Token (NFT) Gaming Market
Our research forecasts the Non-Fungible Token (NFT) Gaming Market to reach 2263.77 Billion by 2033, expanding at a robust 17.51% CAGR from 2027. This hyper-growth is driven by mainstream gaming adoption, institutional venture capital inflows, and the maturation of infrastructure layers developed by market leaders like Immutable Pty Ltd.
Non-Fungible Token (NFT) Gaming Market market size and forecast trajectory through 2033
Projected to scale from 731.66 Billion in 2026 to 2263.77 Billion by 2033, the Non-Fungible Token (NFT) Gaming Market demonstrates exceptional compounding. This trajectory is underpinned by rising AR/VR integration, expanding virtual real estate valuations, and widespread consumer adoption of digital trading cards and tokenized collectibles.
Segmentation Analysis: Categorization and Market Roles
Our comprehensive Non-Fungible Token (NFT) Gaming Market analysis segments the industry across multiple critical dimensions:
- Collectibles: Digital artworks and virtual memorabilia driving emotional engagement.
- Functionality: Reward tokens and utility-based access passes.
- Trading Cards: Sports and fantasy game cards.
- In-Game Assets: Weapons, armor, skins, and avatars.
- Gaming Platform: PC, mobile, AR/VR, and web-based games.
- Blockchain Network: Ethereum, Binance Smart Chain, Flow, Polygon, and Solana.
- Virtual Real Estate: Land parcels and commercial event venues.
Geographic Distribution and Regional Market Performance
Regional performance varies significantly, with the Asia-Pacific region leading in mobile game adoption and player density, while North America dominates in venture capital deployment and intellectual property development. European markets maintain steady growth, tempered by stringent compliance frameworks enforced by regional financial watchdogs.
In-Depth Regional Review of Key Markets
Asia-Pacific remains the epicentre of user acquisition, driven by high mobile penetration and active communities around publishers like Wemade Co. Ltd. and Netmarble Corporation. Meanwhile, North America excels in high-end PC and Web3 infrastructure development, anchored by key innovators operating out of major technology hubs in the United States and Canada.
Strategic Positioning of Leading Companies
Market leaders utilize distinct competitive moats. Mythical Games and Illuvium focus on AAA-quality gameplay to attract traditional gamers, whereas Decentraland Foundation and Uplandme Inc. dominate virtual real estate economies. Sorare SAS captures niche sports verticals through official league licensing partnerships.
Porter's Five Forces Analysis of the Sector
The industry exhibits high threat of new entrants due to low initial software barriers, offset by high customer switching costs within established ecosystems. Bargaining power of buyers is moderate to high, as players demand true ownership and liquidity, while supplier power rests heavily on foundational blockchain protocol developers.
SWOT Analysis of the Non-Fungible Token (NFT) Gaming Market
Key strengths include immutable digital ownership and vibrant player-driven economies. Weaknesses involve user experience friction and gas fee volatility. Opportunities abound in cross-game asset interoperability and AR/VR integration, while threats persist in regulatory uncertainty and persistent cybersecurity vulnerabilities across smart contract implementations.
Value Chain Analysis from Development to End-Users
The value flow originates with raw foundational code and smart contract protocols, moving through game development studios and blockchain infrastructure providers (such as Enjin Pte. Ltd. and Horizon Blockchain Games Inc.), culminating in secondary marketplaces and end-users trading assets like limited edition cards and virtual land parcels.
Investment Insights and High-Potential Areas
Our analysis indicates that high-potential investment areas center around interoperable middleware, zero-knowledge scaling solutions, and studios successfully bridging casual mobile gameplay with tokenized asset economies. Investors should prioritize platforms demonstrating resilient tokenomics and robust regulatory compliance.
Conclusion and Strategic Takeaways
The Non-Fungible Token (NFT) Gaming Market is transitioning from speculative frenzy to sustainable, utility-driven expansion. With a projected market size of 2263.77 Billion by 2033, stakeholders must prioritize user experience, regulatory alignment, and genuine in-game utility to capture long-term value in this evolving digital frontier.
Research Methodology and Baseline Triangulation
Our baseline estimates are triangulated using a rigorous mix of trade registry data, primary stakeholder interviews with executives from organizations like the Blockchain Game Alliance, and secondary macroeconomic indicators. This ensures high-fidelity forecasting of the 17.51% CAGR through 2033.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for the Non-Fungible Token (NFT) Gaming Market from 2026 through 2033. Parameters encompass all major asset types—including in-game assets, collectibles, trading cards, and virtual real estate—across prominent blockchain networks such as Ethereum, Polygon, and Solana, while excluding unregulated underground grey-market platforms.
Recent Developments in the Industry Landscape
Recent strategic moves include major product launches, cross-chain expansions, and high-profile brand partnerships by market makers like Splinterlands, PlayDapp, and Ultra.io. These developments underscore an industry-wide push toward multi-chain accessibility, enhanced game engine integration, and institutional-grade compliance frameworks.