Market overview and structural significance of the Wellbore Cleaning Tool Market
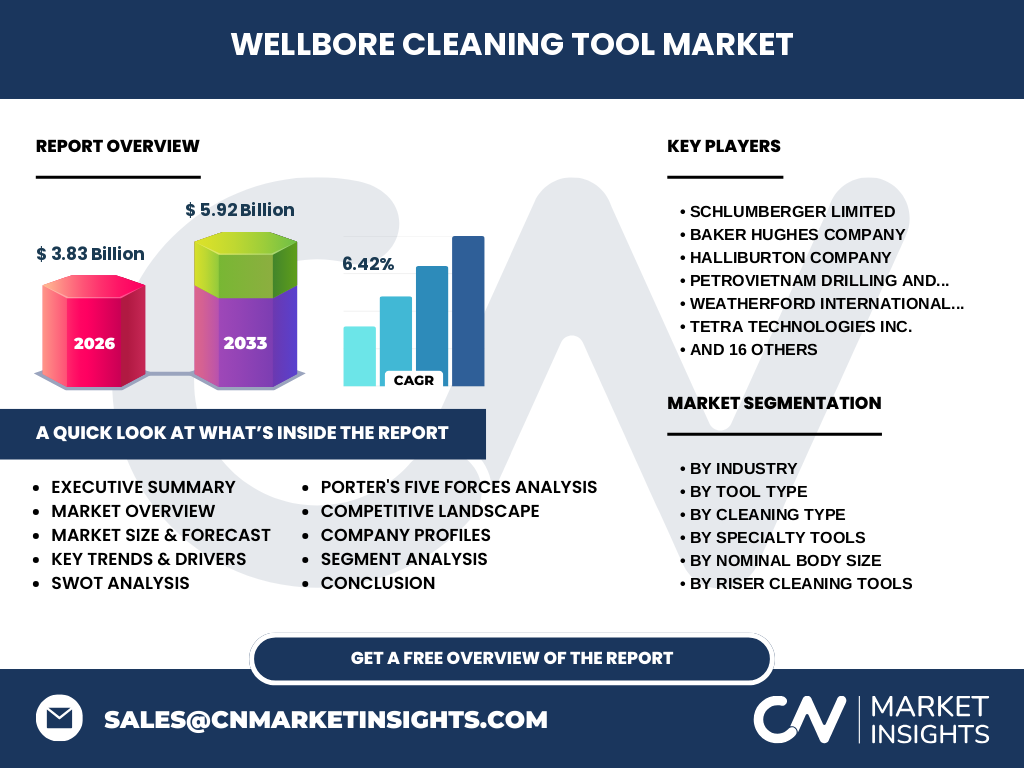
Our analysis indicates that the Wellbore Cleaning Tool Market is valued at $3.83 Billion in 2026. This foundational sector provides essential mechanical and hydraulic devices—such as scrapers, brushes, and magnetic extractors—required to purge drilling waste, metal shavings, and elastomers from wellbores prior to completion, cementing, and intervention operations across harsh offshore and onshore basins.
What core drivers, restraints, and opportunities shape the Wellbore Cleaning Tool Market?
Market expansion is primarily propelled by complex multi-lateral drilling and stringent BSEE and API compliance mandates requiring absolute debris-free wellbore integrity. Conversely, high capital expenditure volatility in deepwater plays acts as a restraint. However, rising brownfield revitalization projects offer substantial opportunities for advanced wellbore cleanup technologies providers.
Structural Growth Drivers and Emerging Industry Trends
The shift toward extended-reach drilling (ERD) and ultra-deepwater exploration has accelerated adoption of specialized multi-stage cleaning systems. Operators increasingly demand integrated bypass tools and high-pressure jetting assemblies to reduce non-productive time (NPT) during critical displacement phases, fundamentally altering operational efficiency benchmarks across global oilfields.
How did the COVID-19 pandemic reshape the Wellbore Cleaning Tool Market trajectory?
The pandemic triggered severe supply chain disruptions and rig count contractions, sharply depressing demand throughout 2020 and 2021. Nevertheless, the post-pandemic recovery trajectory has been robust, fueled by aggressive upstream capital reallocation toward deferred maintenance and wellbore remediation, laying the groundwork for sustained expansion toward 2033.
Competitive Benchmarking and Strategic Dynamics in the Industry
The competitive landscape features a mix of multinational oilfield service giants and specialized independents. Industry leaders like Schlumberger Limited, Baker Hughes Company, and Halliburton Company leverage extensive global footprints and proprietary tool designs, while niche players such as Coretrax Technology Limited and Odfjell Well Services compete through agile, high-margin technological differentiation.
Executive Summary of the Wellbore Cleaning Tool Market
Our comprehensive assessment highlights that the Wellbore Cleaning Tool Market is on a steep upward trajectory, projected to surge from $3.83 Billion in 2026 to $5.92 Billion by 2033, exhibiting a robust CAGR of 6.42%. This momentum underscores the critical role of advanced debris extraction and riser cleaning systems in mitigating catastrophic completion failures.
Market Forecast and Long-Term Valuation Dynamics from 2027 to 2033
Driven by accelerating offshore activity in the Gulf of Mexico, North Sea, and offshore West Africa, the market is forecasted to scale reliably from 2027 through 2033, achieving a total valuation of $5.92 Billion by the end of the period at a steady 6.42% CAGR.
Segmentation Analysis across Tool Types, Cleaning Stages, and End-Use Industries
The market is segmented by industry (Oil And Gas, Mining, Geothermal, Water Well), tool type (Riser, Casing, Jetting, Debris Extraction, Specialty), and cleaning type (Single Stage, Multi-Stage). Oil and gas applications dominate consumption, while Geothermal energy projects represent a high-growth frontier demanding acid-resistant specialty milling tools and robust packer cleanup solutions.
Geographic Distribution and Regional Performance Analysis
Regional performance varies significantly, dictated by basin maturity and regulatory stringency. North America commands significant market share due to aggressive shale basin remediation, while the Middle East and Asia-Pacific exhibit accelerated growth driven by mega-project offshore developments in shallow and deepwater carbonate reservoirs.
In-Depth Regional Review of High-Growth Basins
In the North Sea, strict environmental protocols by OSPAR heavily favor advanced closed-loop riser suction tools and zero-discharge debris baskets. Meanwhile, onshore Permian Basin operations in North America prioritize rapid single-stage casing cleaning tools to maximize operational velocity and minimize completion turnaround times.
Company Profiles and Strategic Positioning of Market Leaders
Major industry participants maintain distinct strategic moats. Weatherford International plc and TETRA Technologies Inc. focus on integrated fluid and mechanical cleaning packages. Concurrently, innovators like Wellbore Integrity Solutions and Reservoir Group deploy specialized proprietary milling and underreaming technologies to address complex wellbore geometry challenges.
Porter's Five Forces Assessment of the Wellbore Cleaning Tool Market
Industry rivalry is intense, driven by continuous patent races in debris extraction technology. Supplier power remains moderate due to specialized raw material requirements like high-grade alloy steels, whereas buyer power is counterbalanced by the high cost of failure, compelling operators to prioritize tool reliability over initial price points.
SWOT Analysis of the Global Wellbore Cleaning Tool Sector
Key strengths include high intellectual property moats and mission-critical utility in well completions. Weaknesses involve vulnerability to upstream capex cycles. Opportunities lie in geothermal energy expansion, while threats stem from accelerating regulatory pushes toward low-carbon alternatives and alternative energy transition funding.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with specialty alloy and elastomer procurement, flows through precision CNC machining and proprietary carbide-facing manufacturing, and extends to service-company deployment fleets. End-users—primarily major E&P operators—rely on these integrated logistics chains to execute flawless displacement and completion operations.
Strategic Investment Insights and High-Potential Areas
Investors should target developers of automated, telemetry-enabled debris extraction tools and magnetic junk catchers. These technologies offer exceptional margin potential as operators increasingly demand real-time verification of wellbore cleanliness to protect expensive downhole electronics and inflow control devices.
Conclusion and Strategic Takeaways for Industry Stakeholders
The data confirms that mastering technological integration and regional compliance is paramount. Companies aligning product portfolios with multi-stage cleaning demands and automated extraction mechanisms will capture disproportionate share as the market expands toward its $5.92 Billion valuation target.
Research Methodology and Baseline Triangulation Techniques
Our findings are derived from a rigorous triangulation methodology, combining primary interviews with drilling superintendents and completion engineers, exhaustive analysis of regulatory filings from bodies like the API and BSEE, and secondary macroeconomic indicators tracking global rig counts and offshore capital expenditure flows.
Scope of the Report and Analytical Coverage Parameters
This report encompasses global deployment dynamics of wellbore cleaning technologies across nominal body sizes ranging from 4-inch to above 16-inch geometries. Limitations exclude localized grey-market manufacturing operations not captured within verified trade registries and national customs databases.
Recent Developments, Strategic Partnerships, and Technological Innovations
Recent market activity highlights aggressive M&A and strategic alliances aimed at expanding proprietary portfolios. Firms like Coretrax and Archer Limited have recently introduced advanced intelligent bypass and magnetic filtration systems, reflecting an industry-wide push toward automated, high-efficiency wellbore remediation solutions.