What is the scope and industry significance of the Smart Education And Learning Market?
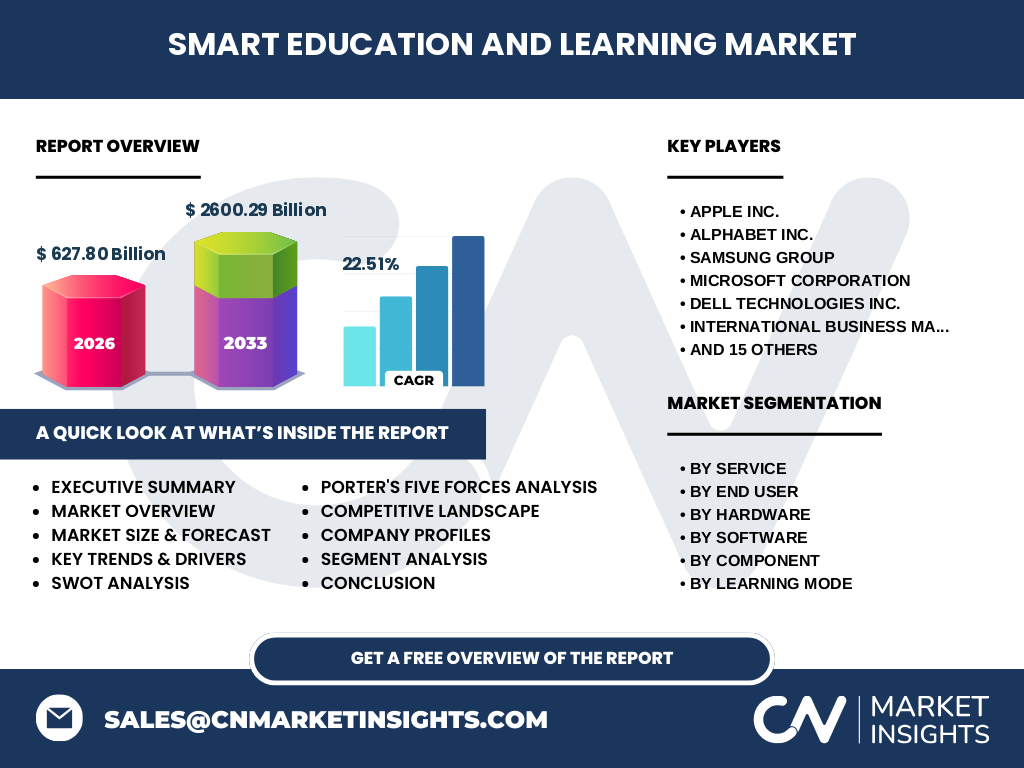
Our analysis indicates that the Smart Education And Learning Market market size reaches 627.80 Billion in 2026. This sector transforms global educational infrastructure by integrating digital hardware, cloud infrastructure, and immersive software to modernize institutional and enterprise knowledge delivery.
What are the structural growth drivers, restraints, challenges, and opportunities shaping the industry?
Growth is propelled by surging demand for personalized instruction and ubiquitous broadband access. However, tight data privacy mandates from bodies like the FTC and high upfront hardware costs create deployment barriers. Opportunities abound in emerging economies adopting cloud-based architectures.
Emerging trends and growth patterns in the sector
The market experiences an accelerated shift toward AI-driven adaptive curricula and immersive mixed-reality instructional environments. These technological shifts favor vendors capable of fusing Learning Management Systems (LMS) with advanced analytics to track learner progression in real time.
How did the COVID-19 pandemic impact the market and shape the recovery trajectory?
The pandemic served as an unprecedented catalyst, forcing educational institutions and corporate entities to rapidly deploy remote learning tools. This emergency transition permanently altered the baseline for digital adoption, accelerating long-term market valuations toward the forecasted 2600.29 Billion.
Competitive Benchmarking and Strategic Dynamics
The industry features a mix of multinational tech giants and specialized EdTech providers. Companies like Apple Inc. and Alphabet Inc. dominate hardware ecosystems, while specialized software providers focus on proprietary pedagogical tools, driving high market concentration across enterprise verticals.
Executive Summary of Key Findings
Our research underscores a phenomenal projected expansion at a 22.51% CAGR from 2027 to 2033, culminating in a 2600.29 Billion valuation by 2033. Stakeholders must prioritize cloud scalability and localized compliance to capture expanding market share.
Market Forecast Analysis from 2027 to 2033
Driven by compounding investments in digital transformation and AI integration, the sector scales rapidly from its 2026 baseline. Our forecasts show that the market will achieve a robust 22.51% CAGR, reaching 2600.29 Billion by 2033 as corporate training budgets shift entirely online.
Segmentation Analysis across Services, End Users, Hardware, Software, Components, and Learning Modes
Market architecture spans multiple vectors: By Service includes System Integration, Cloud-based, Content Development, Training, Support, and Licensing. By End User covers Academics and Corporate. By Hardware features Interactive Whiteboards, VR/AR Devices, and Tablets. By Software encompasses LMS, Virtual Classrooms, and Adaptive Learning. By Component breaks down into Hardware, Software, and Service. By Learning Mode highlights Virtual Instructor-Led Training, Simulation, and Blended Learning.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, with North America leading due to mature cloud infrastructure and high enterprise tech spending. Meanwhile, Asia-Pacific demonstrates the fastest relative growth, spurred by government-backed digital literacy initiatives and massive student demographics.
In-Depth Regional Review
North America remains the revenue stronghold, anchored by robust corporate training investments and institutional tech upgrades. Conversely, the European market prioritizes stringent data sovereignty regulations, directing regional buyers toward secure, locally hosted cloud-based services and proprietary compliance frameworks.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct competitive moats. Microsoft Corporation and Cisco Systems Inc. leverage enterprise collaboration suites, while Pearson PLC and McGraw-Hill Inc. dominate content licensing. Meanwhile, specialized platforms like Coursera Inc. and Udemy Inc. capture the direct-to-consumer and corporate upskilling markets.
Porter's Five Forces Analysis
Competitive rivalry remains intense as tech conglomerates cross-pollinate consumer tech into classrooms. Buyer power is moderate to high, tempered by high switching costs once an institutional Learning Management System (LMS) is deeply embedded into school or corporate workflows.
SWOT Analysis of the Global Ecosystem
Strengths include scalable digital content delivery and advanced analytics. Weaknesses involve high initial capital expenditure for Virtual Reality (VR) And Augmented Reality (AR) Devices. Opportunities lie in emerging corporate upskilling, while threats center on cybersecurity vulnerabilities and strict regulatory compliance penalties.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with silicon and raw hardware components sourced globally, transforming into specialized devices manufactured in key Asian hubs. These are integrated with software applications and educational content before final deployment across academic institutions and corporate training departments.
Investment Insights and Strategic Recommendations
Investors should target developers of adaptive learning software and immersive simulation platforms. High-potential areas include enterprise compliance training and K-12 hybrid infrastructure, where recurring SaaS revenue models provide exceptional insulation against economic volatility.
Conclusion and Key Takeaways
The trajectory toward 2600.29 Billion by 2033 confirms that digital learning tools are no longer supplemental, but foundational. Organizations that successfully integrate cloud agility with stringent data security will dominate this high-growth ecosystem.
Research Methodology
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators from global educational bodies to ensure absolute market accuracy.
Scope of the Report
This report evaluates the global landscape from 2026 through 2033, analyzing hardware, software, services, and end-user segments across major geographic regions. Limitations include unpredicted macroeconomic shocks and shifting regional regulatory frameworks.
Recent Developments in the Industry
Recent strategic moves feature major technology partnerships between cloud providers and publishing houses to embed generative AI directly into e-books. Furthermore, hardware manufacturers have unveiled lightweight smart glasses tailored for immersive classroom collaboration.