Market Overview of the Coal, Lignite, And Anthracite Market
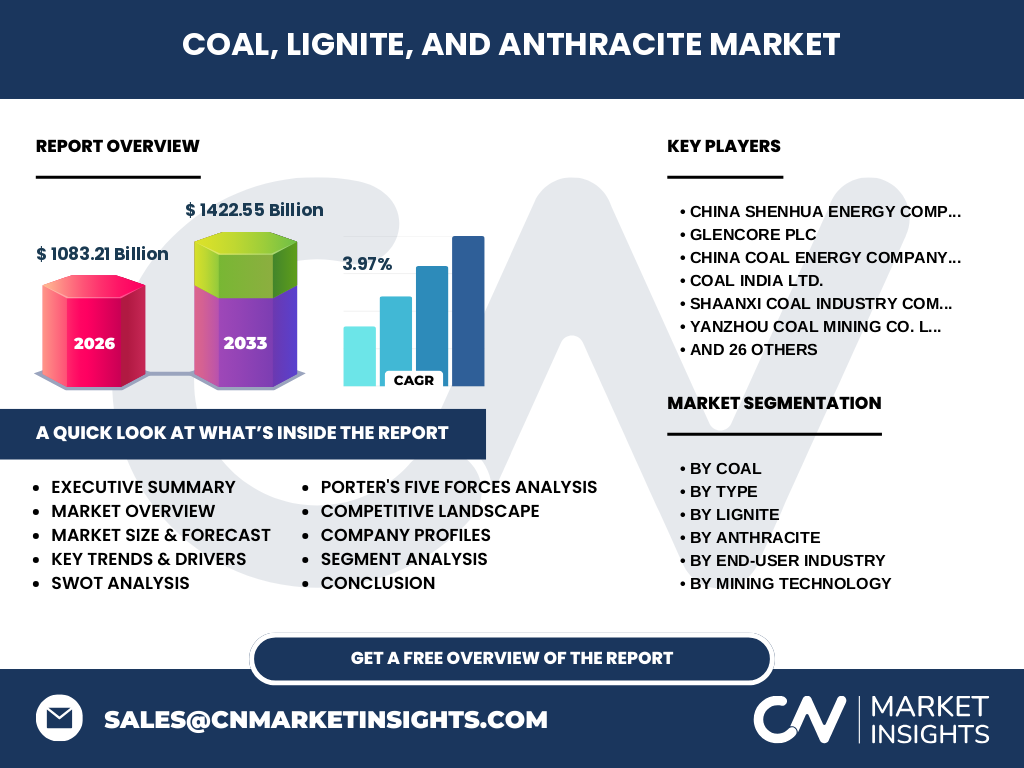
Our analysis indicates that the Coal, Lignite, And Anthracite Market encompasses the global extraction, processing, and distribution of solid fossil fuels powering heavy industry and baseload power generation. Reaching 1083.21 Billion in 2026, this sector serves as the primary energy backbone for emerging economies, navigating complex regulatory shifts and tightening environmental mandates enforced by bodies like the IPCC and regional energy ministries.
Structural Growth Drivers and Market Restraints
The market is propelled by surging electricity demands in developing Asian industrial corridors, contrasted against severe decarbonization restraints and stringent ESG financing hurdles. Thermal coal and metallurgical coking coal face logistical bottlenecks at major export terminals like Newcastle and Richards Bay, while rising carbon pricing schemes challenge traditional heavy-emitting end-user operations across cement and steel manufacturing.
Emerging Trends and Technological Transformation
Industry participants are aggressively adopting advanced surface and underground automated mining technologies to optimize extraction yields and mitigate labor safety risks. Digital twin simulations and AI-driven fleet management systems are reshaping operational efficiencies for major producers like Coal India Ltd. and China Shenhua Energy Company Limited, reducing carbon intensity per ton extracted.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
The pandemic severely disrupted global supply chains, causing temporary demand contraction followed by a sharp, post-lockdown energy crunch that drove historical pricing highs. Our research shows that government stimulus packages prioritizing infrastructure revitalization rapidly accelerated the recovery trajectory, pushing valuations toward the projected 1422.55 Billion milestone by 2033.
Competitive Benchmarking and Industry Consolidation
The landscape features a mix of massive state-owned enterprises and agile private operators, with high market concentration among giants like Glencore plc, BHP Group, and China Coal Energy Company Limited. Strategic positioning heavily favors companies diversifying into high-grade metallurgical coal assets to capture premium steel-manufacturing margins amid tightening thermal coal regulations.
Executive Summary of Coal, Lignite, And Anthracite Market Dynamics
Valued at 1083.21 Billion in 2026, the Coal, Lignite, And Anthracite Market industry trends reflect a resilient sector expanding at a steady 3.97% CAGR through 2033. Despite accelerating green energy transitions, foundational steel and electricity sectors guarantee sustained demand, rewarding well-capitalized firms capable of balancing regulatory compliance with high-volume extraction efficiencies.
Long-Term Market Forecast from 2027 to 2033
Driven by robust urbanization across the Global South, the sector is projected to expand from its 2026 baseline to reach 1422.55 Billion by 2033 at a compound annual growth rate of 3.97%. Data suggests that while thermal applications face long-term headwinds, metallurgical grades will maintain resilient pricing power due to irreplaceable roles in blast-furnace steel production.
Comprehensive Segmentation Analysis
The market is segmented by product into Coal, Lignite (Brown and Black variants), and Anthracite (Hard and Semi-Hard types), alongside Bituminous, Sub-Bituminous, Thermal, and Metallurgical (Coking) grades. End-user applications span Electricity, Steel, and Cement, operated primarily through Surface and Underground mining technologies across Large Enterprises and SMEs.
Geographic Distribution and Regional Performance
Asia-Pacific dominates global consumption, underpinned by massive coal-fired power infrastructure in China and India, whereas North America and Europe experience gradual structural declines under stringent environmental directives. Regional performance heavily mirrors domestic energy security policies, with emerging markets prioritizing affordable baseload power over rapid fossil fuel divestment.
In-Depth Regional Review of Key Markets
China and India remain the undisputed epicenters of demand, supported by domestic mega-producers like Shaanxi Coal Industry and Yanzhou Coal Mining. Conversely, Australian exporters like Whitehaven Coal and Coronado Global Resources capitalize on Asian import dependencies, navigating localized rail bottlenecks and port congestion to service high-grade metallurgical coal contracts.
Strategic Company Profiles and Market Positioning
Industry leaders deploy distinct strategies: Peabody Energy Corporation and Arch Resources optimize thermal and metallurgical asset portfolios for cash generation, while diversified miners like Anglo American plc and Rio Tinto Group balance coal exposure with transition minerals. State-backed entities like China Shenhua Energy emphasize domestic energy security and integrated supply chain efficiencies.
Porter's Five Forces Assessment
The threat of substitutes is rising due to renewable energy expansion, yet supplier power remains moderate given high capital barriers to new reserve acquisition. Buyer power is concentrated among major utilities and steel mills, while competitive rivalry is intense among dominant global players vying for long-term export quotas and rail capacity rights.
SWOT Analysis of the Global Sector
Key strengths lie in vast established reserves and high energy density, offset by significant environmental weaknesses and carbon liabilities. Opportunities abound in clean-coal technology adoption and emerging market industrialization, while major threats include aggressive carbon taxation, stringent ESG divestment policies, and volatile regulatory interventions.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with geological prospecting and capital-intensive surface or underground extraction, followed by washing, crushing, and beneficiation to meet grade specifications. Logistics form a critical midstream node utilizing heavy rail networks and bulk carriers before delivery to power utilities, coking plants, and cement manufacturers.
High-Potential Investment Insights and Opportunities
Investors should focus on high-grade metallurgical coal assets and companies integrating carbon capture, utilization, and storage (CCUS) technologies to future-proof operations. Strategic opportunities also exist in acquiring distressed thermal assets in developing regions where baseload coal dependency will persist well into the next decade.
Conclusion and Definitive Industry Takeaways
The Coal, Lignite, And Anthracite Market market size of 1083.21 Billion in 2026 evolving to 1422.55 Billion by 2033 underscores a resilient industry defying rapid obsolescence. Success belongs to agile producers leveraging advanced mining automation, disciplined capital allocation, and strategic alignment with non-discretionary industrial steel and power requirements.
Rigorous Research Methodology and Data Triangulation
Our baseline estimates are derived by triangulating primary stakeholder interviews with C-suite mining executives, secondary macroeconomic indicators from the IEA and World Steel Association, and proprietary trade registry data. This multi-tiered approach reconciles export-import customs logs with localized production reporting to ensure absolute forecast accuracy.
Scope of the Report and Analytical Parameters
This report covers global revenue estimations, volume shipments, and pricing trends across all specified coal types, mining technologies, and end-user verticals from 2027 through 2033. Exclusions involve unregistered informal artisanal mining operations and localized non-commercial domestic usage not captured by official national energy statistics.
Recent Developments, Partnerships, and Strategic Moves
Recent market activity highlights increased merger and acquisition maneuvers among mid-tier producers, alongside joint ventures focused on emissions-reduction technologies. Major miners are actively divesting peripheral thermal assets to streamline operations while securing long-term supply agreements with Asian steel conglomerates and state-owned power generators.