What is the scope and industry significance of the Gaming Accessories Market?
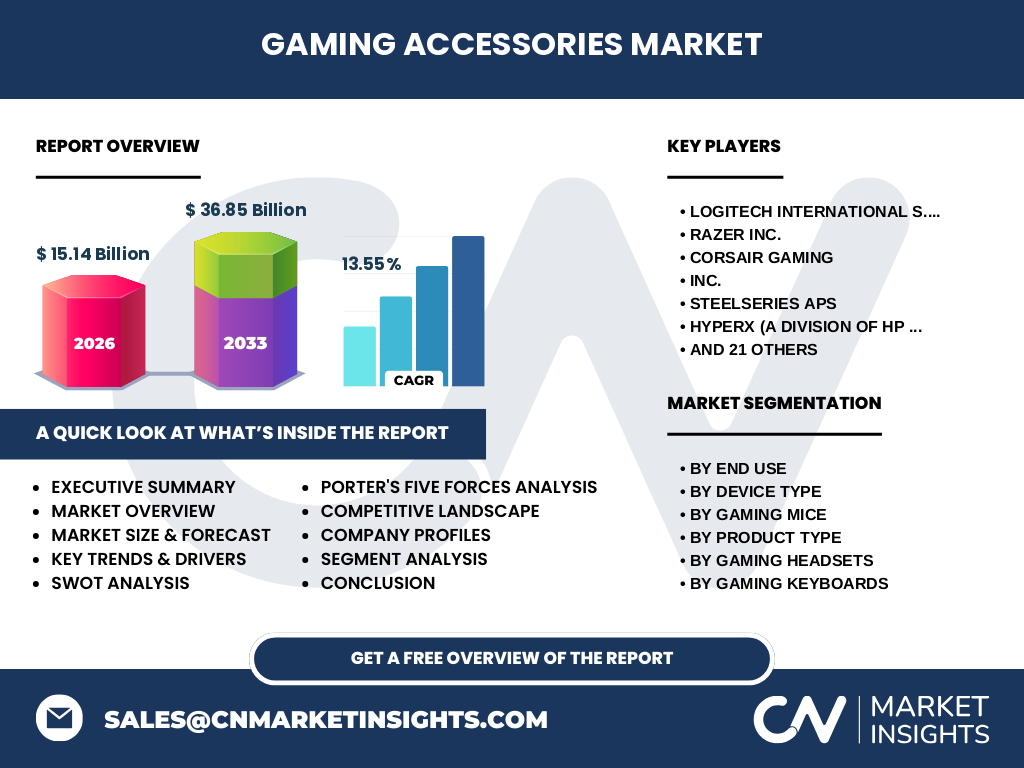
Our analysis indicates the Gaming Accessories Market reaches a valuation of 15.14 Billion in 2026. This sector encompasses hardware peripherals like mechanical keyboards, wireless headsets, and specialized controllers that elevate user performance across PCs, smartphones, and consoles.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising eSports adoption and ergonomic demands, though supply chain bottlenecks for rare earth elements used in haptic feedback devices act as notable restraints. Compliance with strict FCC and CE regulatory bodies also adds overhead.
The Shift Toward Wireless and Ergonomic Peripherals
The Gaming Accessories Market industry trends reveal a massive pivot toward ultra-low latency wireless connectivity and specialized ergonomic mice. Consumers increasingly prioritize desk minimalism without sacrificing polling rates or battery longevity during extended competitive sessions.
Pandemic Impact and Post-COVID Recovery Trajectory
The COVID-19 pandemic triggered unprecedented demand surges for home-entertainment hardware. Supply chain disruptions at major Asian ports initially stalled manufacturing, but the recovery trajectory has firmly stabilized logistical pipelines across global distribution channels.
Competitive Benchmarking and Industry Concentration
The market features intense rivalry among specialized hardware giants like Logitech International S.A., Razer Inc., and Corsair Gaming, Inc. Market concentration is moderate-to-high, forcing mid-tier brands to innovate rapidly in sensor accuracy and switch modularity.
Executive Summary of the Gaming Accessories Market Analysis
Based on our research, the Gaming Accessories Market analysis projects expansion from 2026 figures to 36.85 Billion by 2033. Driven by a robust 13.55% CAGR, premium customization options represent the primary profit engine.
Market Forecast and Long-Term Valuation Trajectory
The data suggests sustained acceleration from 2027 to 2033, culminating in a 36.85 Billion market valuation. This expansion outpaces general consumer electronics, fueled by rising disposable incomes and professionalization of competitive gaming.
Comprehensive Segmentation Analysis
Our breakdown of the Gaming Accessories Market size spans multiple dimensions:
- End Use: Professional and Casual Gamers
- Device Type: PCs, Smartphones, Consoles
- Product Type: Gamepads, Keyboards, Mice, Headsets, VR Devices
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America and Asia-Pacific leading consumption due to high dense urban internet infrastructure and established eSports leagues. Localized regulatory constraints regarding battery safety standards dictate regional product adaptations.
In-Depth Regional Review of Key Markets
Asia-Pacific dominates volume production and consumption, anchored by manufacturing hubs in Taiwan and China. Meanwhile, North America demonstrates higher average revenue per user, favoring premium wireless headsets and mechanical keyboards equipped with customizable RGB backlighting.
Strategic Positioning of Leading Companies
Industry leaders carve out distinct moats: SteelSeries ApS and HyperX focus on acoustic fidelity, while ASUSTeK Computer Inc. and Micro-Star International Co., Ltd. leverage their motherboard ecosystems to bundle cohesive desktop peripheral packages.
Porter's Five Forces Competitive Intensity Assessment
Supplier power remains moderate due to specialized microswitch manufacturing, whereas competitive rivalry is exceptionally fierce. Threat of substitutes is low because standard office peripherals cannot match the polling rates and macro-programming required by enthusiasts.
SWOT Analysis of the Gaming Accessories Ecosystem
Key strengths include strong brand loyalty and rapid technological iteration. Weaknesses involve vulnerability to component cost inflation. Opportunities lie in haptic VR gloves, while threats stem from counterfeit peripherals flooding e-commerce platforms.
Value Chain Analysis from Raw Materials to End-Users
The value flow begins with raw silicon and polymer procurement, moves through precision SMT assembly in Shenzhen factories, passes via containerized shipping through ports like Los Angeles and Rotterdam, and terminates at specialized retail and direct-to-consumer e-commerce portals.
Strategic Investment Insights and High-Potential Areas
Investors should target brands specializing in wireless latency reduction technologies and ergonomic vertical mice. Companies integrating proprietary software suites for macro customization exhibit superior customer lifetime value metrics.
Conclusion and Strategic Takeaways
Surpassing 36.85 Billion by 2033 at a 13.55% CAGR, the ecosystem rewards differentiation. Organizations focusing on modularity, durability, and software synergy will capture outsized market share.
Rigorous Research Methodology for Baseline Estimates
Our findings combine triangulation of customs trade registry data, primary executive stakeholder interviews across key manufacturing hubs, and secondary macroeconomic indicators regarding global discretionary spending on consumer technology.
Scope of the Report and Coverage Parameters
This report evaluates global revenue streams for hardware peripherals spanning 2026 through 2033. Limitations exclude purely software-based gaming enhancements and non-gaming standard office peripherals lacking gaming-specific certifications.
Recent Industry Developments, Partnerships, and Product Launches
Recent milestones include strategic acquisitions by Turtle Beach Corporation and groundbreaking haptic patent filings by Sony Interactive Entertainment LLC and Microsoft Corporation, signaling an aggressive push into immersive, multi-sensory accessory integration.