What is the scope of the Nonmetallic Minerals Mining Support Activities Market?
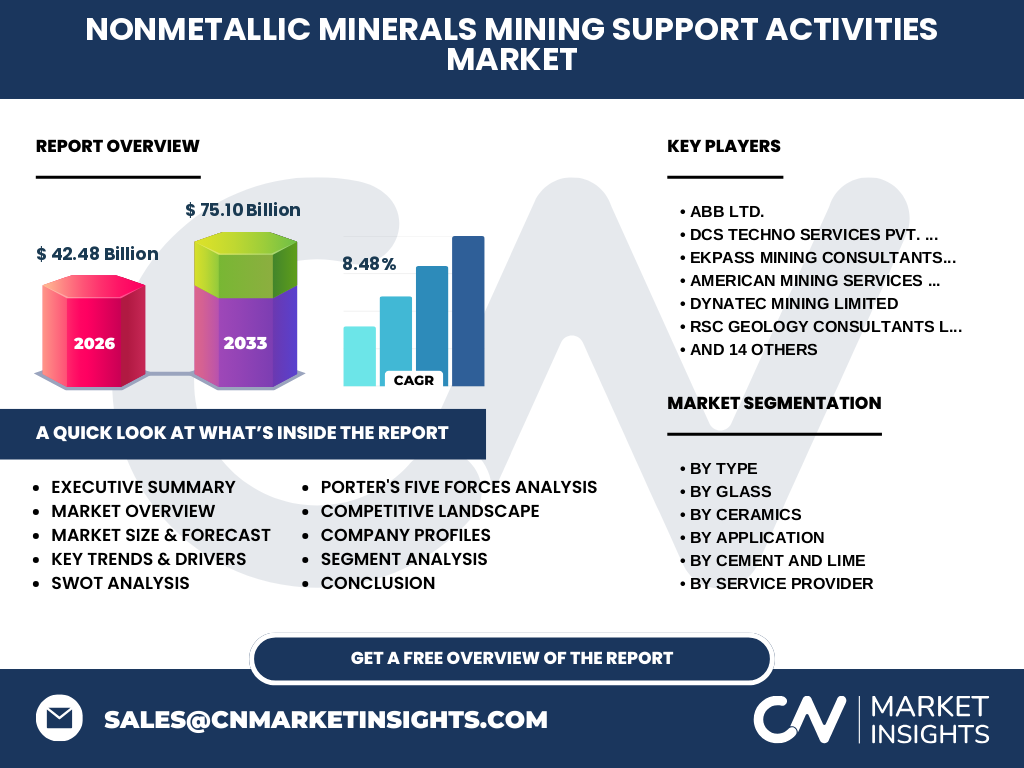
Our analysis indicates that the Nonmetallic Minerals Mining Support Activities Market reaches a valuation of $42.48 Billion in 2026, establishing a critical foundation for industrial mineral extraction. This sector encompasses specialized drilling, site preparation, and exploratory services tailored for non-fuel minerals. Industry participants like Boart Longyear Ltd. and Major Drilling Group International Inc. provide essential technical oversight, ensuring regulatory compliance with bodies such as the Mine Safety and Health Administration (MSHA) during extraction phases for essential inputs.
Key market drivers, restraints, challenges, and opportunities shaping the Nonmetallic Minerals Mining Support Activities Market
Structural growth is heavily propelled by urban infrastructure expansion demanding robust Portland Cement and aggregate supplies. However, stringent environmental mandates from the EPA regarding dust suppression and tailing management act as operational restraints. Market opportunities lie in deploying advanced automated telemetry systems provided by innovators like ABB Ltd., mitigating skilled labor shortages and reducing operational downtime across remote quarrying sites.
Emerging trends and growth patterns in the Nonmetallic Minerals Mining Support Activities Market
The sector is experiencing a definitive shift toward electrification and digital twin modeling. Major contractors are adopting low-emission drilling fleets to meet corporate ESG targets. Energy efficiency optimization is rewriting operational protocols, favoring agile independent contractors who can rapidly integrate IoT-enabled sensor diagnostics into legacy limestone and clay extraction workflows.
COVID-19 impact analysis on the Nonmetallic Minerals Mining Support Activities Market
Pandemic-induced supply chain fractures and mandatory lockdowns initially depressed demand for container glass and ceramic inputs, temporarily stalling exploration projects. The post-pandemic recovery trajectory has been robust, catalyzed by fiscal stimulus packages targeting public works. Pent-up infrastructure demand accelerated contract renewals for key service providers, swiftly returning operational output to pre-crisis trajectories.
Competitive landscape and strategic dynamics in the Nonmetallic Minerals Mining Support Activities Market
The market exhibits moderate fragmentation at regional levels while maintaining high consolidation among tier-one global conglomerates. Industry leaders like CIMIC Group Limited and Hochtief AG leverage balance-sheet strength to secure long-term service contracts. Strategic mergers and acquisitions remain the primary vehicle for acquiring proprietary geotechnological assets and expanding geographic footprints across high-yield mineral deposits.
Executive summary of the Nonmetallic Minerals Mining Support Activities Market
This comprehensive report highlights a projected market expansion to $75.10 Billion by 2033, expanding at a robust CAGR of 8.48% from 2027. Our research demonstrates that surging consumption of specialty glass, structural ceramics, and lime-based binders will anchor demand for specialized exploration and site support services over the forecast horizon.
Market forecast from 2027 to 2033 for Nonmetallic Minerals Mining Support Activities
Driven by a steady CAGR of 8.48%, the market is poised to scale from its 2026 baseline to reach $75.10 Billion by 2033. This trajectory reflects sustained capital expenditure in emerging economies prioritizing domestic raw material security, coupled with technological upgrades in specialized drilling and strata control services.
Segmentation analysis of the Nonmetallic Minerals Mining Support Activities Market
Segmentation is categorized by type, glass, ceramics, application, cement and lime, and service provider. By Type, the market covers Cement And Lime, Ceramics, and Glass. Glass is further split into flat glass, container glass, and fiberglass. Ceramics comprises clay, porcelain, and stoneware. Applications span jewelry, construction, and others. Cement and lime includes Portland cement and lime. Service providers feature independent contractors and companies.
Regional market analysis and geographic performance
Geographic performance is heavily weighted toward regions with active construction booms and extensive mining infrastructure. Asia-Pacific dominates consumption share due to rapid urbanization in developing economies, whereas North America maintains high demand for sophisticated technical support services provided by firms like American Mining Services LLC.
In-depth regional review of key operational hubs
A granular review indicates that regulatory frameworks in Western markets necessitate high compliance expenditures, favoring well-capitalized firms. Conversely, Southeast Asian corridors—supported by entities such as PT United Tractors Tbk—experience rapid expansion driven by localized aggregate demand, limestone quarrying, and favorable foreign investment policies in mining infrastructure.
Company profiles and strategic positioning of leading market players
Leading entities exhibit distinct strategic moats. The Weir Group plc focuses on advanced slurry pumping and mineral processing technology, while Foraco International SA and Dynatec Mining Limited specialize in deep-hole mineral exploration drilling. Market positioning relies heavily on proprietary technological integration and localized fleet availability to minimize mobilization friction.
Porter's Five Forces analysis of the Nonmetallic Minerals Mining Support Activities Market
Bargaining power of buyers remains moderate due to the essential nature of specialized mining support. Threat of new entrants is constrained by high capital expenditure requirements for specialized drilling rigs and stringent environmental safety certifications. Competitive rivalry is intense among established tier-one contractors vying for long-term quarry management agreements.
SWOT analysis of the Nonmetallic Minerals Mining Support Activities Market
Key strengths include deep technical expertise and entrenched client relationships with major cement producers. Weaknesses involve high sensitivity to macroeconomic construction cycles. Opportunities center on automation and green mining initiatives, while threats encompass volatile regulatory compliance costs and geopolitical trade tensions affecting heavy equipment imports.
Value chain analysis from raw materials to end-users
The value chain initiates with geological surveying and exploratory drilling by specialists like RSC Geology Consultants Ltd., progressing to site preparation and overburden removal. The chain culminates in contracted operational support for extracting raw limestone, clay, and silica sand, which ultimately feed downstream manufacturing facilities for fiberglass and Portland Cement.
Investment insights and high-potential areas in Nonmetallic Minerals Mining Support Activities
High-potential capital allocation targets automated drilling systems and predictive maintenance software. Investors should prioritize service providers exhibiting robust ESG credentials and strong multi-year contracts with major industrial mineral producers. Strategic investments in localized supply chain nodes will capture disproportionate upside as regional infrastructure spending accelerates.
Conclusion and key takeaways for industry stakeholders
The market presents compelling growth dynamics, underpinned by a projected valuation of $75.10 Billion by 2033. Success in this sector requires continuous technological adaptation, stringent safety adherence, and strategic alignment with green building trends favoring low-carbon Portland Cement and specialized ceramic inputs.
Research methodology for baseline estimates and data triangulation
Our research methodology employs a rigorous triangulation model combining primary stakeholder interviews with mining executives, secondary macroeconomic indicators from global trade registries, and proprietary financial filings. Baseline estimates are cross-verified against regional regulatory filings to ensure absolute accuracy in market sizing and CAGR projections.
Scope of the report, coverage parameters, and analytical limitations
This report covers global nonmetallic minerals mining support activities across specified service provider types, application verticals, and material segments from 2026 through 2033. Analytical limitations include potential unforeseen macroeconomic disruptions and localized policy shifts that could alter regional extraction quotas and environmental compliance timelines.
Recent developments, strategic moves, and industry partnerships
Recent market dynamism is highlighted by aggressive fleet electrification initiatives by firms like Perenti Global Ltd. and strategic service partnerships formed by NRW Holdings Limited. Industry consolidation continues as major players acquire niche geotechnical consultancy firms to bolster their proprietary exploration capabilities and expand their service offerings.