Market Overview and Industry Significance of the Perforating Gun Market
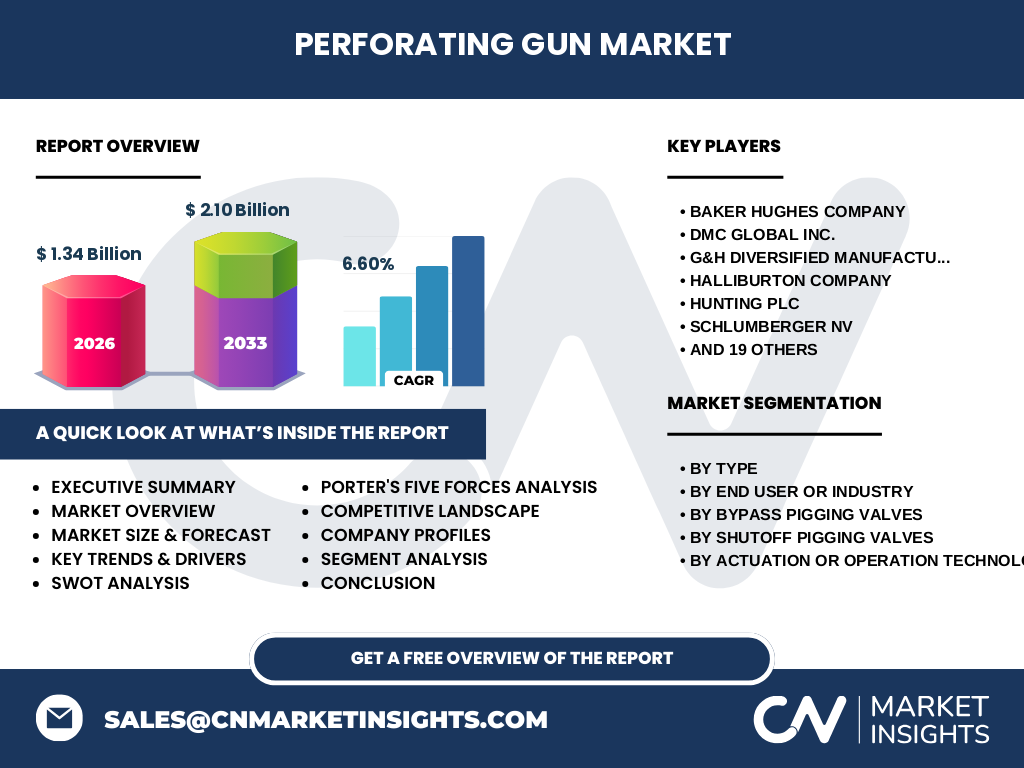
Our analysis indicates that the Perforating Gun Market is valued at 1.34 Billion in 2026, serving as a critical upstream asset in well completion operations. These precision tools establish communication between the wellbore and hydrocarbon-bearing rock formations. Navigating stringent API specifications and stringent environmental compliance, the sector underpins global oil and gas extraction efficiency.
Structural Growth Drivers, Restraints, and Opportunities
Growth in the Perforating Gun Market is accelerated by rising demand for multi-stage fracturing in unconventional shale plays. However, supply chain bottlenecks for high-grade steel and stringent regulatory hurdles by bodies like the EPA pose restraints. Significant opportunities lie in integrating energetic components with dissolvable plug technologies to reduce post-fracking intervention costs.
The Shift Toward Advanced Downhole Technologies
Industry trends reveal an aggressive migration toward smart detonators and directional perforating systems. Operators increasingly demand integrated solutions from innovators like Dyna-energetics GmbH & Co. KG and Halliburton Company to maximize reservoir contact. This shift favors suppliers capable of delivering high-temperature survivability and extreme pressure tolerance in deepwater environments.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
The pandemic caused an unprecedented contraction in upstream capital expenditures, temporarily disrupting supply chains across major manufacturing hubs in North America and Asia. Recovery has been robust, propelled by rebounding crude prices and operators prioritizing brownfield optimization. Companies leveraging automated manufacturing lines adapted faster to labor shortages during this volatile period.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is moderately consolidated, dominated by Tier-1 oilfield service giants such as Schlumberger NV, Baker Hughes Company, and Weatherford International Ltd. These industry leaders maintain market share through proprietary energetic formulations and global distribution networks, continuously pressing smaller regional players on price and technological integration.
Executive Summary of the Perforating Gun Market Analysis
Driven by rising global energy demand and technological sophistication, the Perforating Gun Market is poised for steady expansion. Our proprietary research highlights a robust expansion trajectory from 2027 to 2033. Strategic consolidation and R&D investments in environmentally resilient energetic systems remain the primary avenues for long-term margin preservation.
Market Forecast and Long-Term Valuation (2027-2033)
The data projects that the Perforating Gun Market will reach 2.10 Billion by 2033, expanding at a steady 6.60% CAGR from 2027. This growth reflects sustained drilling activity in the Permian Basin, offshore Latin Arabia, and emerging deepwater blocks requiring high-precision shaped charges.
Segmentation Analysis by Type and Application
Segmentation spans critical categories including Bypass Pigging Valves (Manual, Pneumatic, Automated) and Shutoff Pigging Valves (Manual, Pneumatic, Electric). End-user verticals range from the Oil and Gas Industry to Refining, Petrochemical, and Chemical sectors. Actuation technologies further divide into manual, pneumatic, and electric systems, tailoring tools to specific onshore and offshore operational constraints.
Geographic Distribution and Regional Market Performance
North America dominates regional consumption due to extensive shale fracking operations, followed by the Middle East and Africa, where massive onshore conventional projects drive high-volume deployments. Asia-Pacific demonstrates the fastest relative growth, spurred by offshore exploration concessions in Southeast Asia and rising domestic energy demands in India and China.
In-Depth Regional Review of High-Growth Zones
In North America, strict regulatory oversight by OSHA and environmental agencies dictates equipment safety standards for explosive handling. Meanwhile, Middle Eastern markets prioritize extreme temperature resilience, requiring specialized metallurgical compositions. Logistical hurdles in remote Siberian and Latin American basins further necessitate robust local supply chain partnerships.
Strategic Positioning of Leading Market Participants
Key market participants such as Hunting PLC, NOV Inc., and Core Laboratories N. V. differentiate themselves through specialized engineering and localized service hubs. Firms like Shaanxi FYPE Rigid Machinery Co. Ltd. and Zao NTF Perfotech capture regional market share by offering cost-competitive alternatives tailored to specific domestic drilling standards.
Porter's Five Forces Assessment of Competitive Pressures
Bargaining power of buyers is moderate to high due to consolidated E&P operators demanding cost concessions. Threat of substitutes remains low given the irreplaceable physics of explosive rock fracturing. Supplier power is constrained by abundant raw material availability, though specialized energetic chemical sourcing introduces localized pricing pressures.
SWOT Analysis of the Perforating Gun Market
Strengths include high operational reliability and advanced energetic formulations. Weaknesses involve complex logistics and regulatory compliance costs for explosives. Opportunities abound in automated gun systems and eco-friendly degradable materials. Threats stem from macroeconomic volatility and aggressive substitution by alternative well stimulation techniques.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material extraction—primarily high-strength alloy steel and explosive chemicals like HMX and HNS. Midstream manufacturing involves precision machining, energetic loading, and rigorous quality testing. Downstream distribution relies on specialized oilfield service providers delivering fully assembled gun systems to E&P operating sites.
Strategic Investment Insights and High-Potential Areas
Investors should target niche innovators developing wireless detonator technology and eco-friendly degradable charge cases. Our analysis indicates that companies investing in digital twins for perforating string simulation will capture outsized market share as operators increasingly demand predictive modeling to mitigate costly downhole failures.
Conclusion and Strategic Key Takeaways
The Perforating Gun Market presents compelling long-term fundamentals anchored by a 6.60% CAGR through 2033. Success in this sector requires continuous R&D investment, adherence to evolving environmental regulations, and strategic alignment with major service providers capable of navigating complex global logistics.
Research Methodology and Baseline Estimation Triangulation
Baseline estimates are synthesized by triangulating trade registry data, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators. We cross-reference rig count data, customs export logs for energetic materials, and corporate financial disclosures to ensure high-fidelity market sizing and predictive accuracy.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for the Perforating Gun Market across all major geographic regions, segmented by valve types, actuation technologies, and end-user industries. Limitations include trade confidentiality in certain state-owned enterprises and unrecorded domestic transactions in fragmented regional markets.
Recent Industry Developments and Strategic Corporate Moves
Recent strategic actions include major cross-border acquisitions and partnerships aimed at expanding proprietary gun string portfolios. Companies are actively launching digital integration platforms to monitor real-time downhole telemetry during perforation, reducing non-productive time for E&P operators worldwide.