Shape Memory Alloys Market market size and industry significance
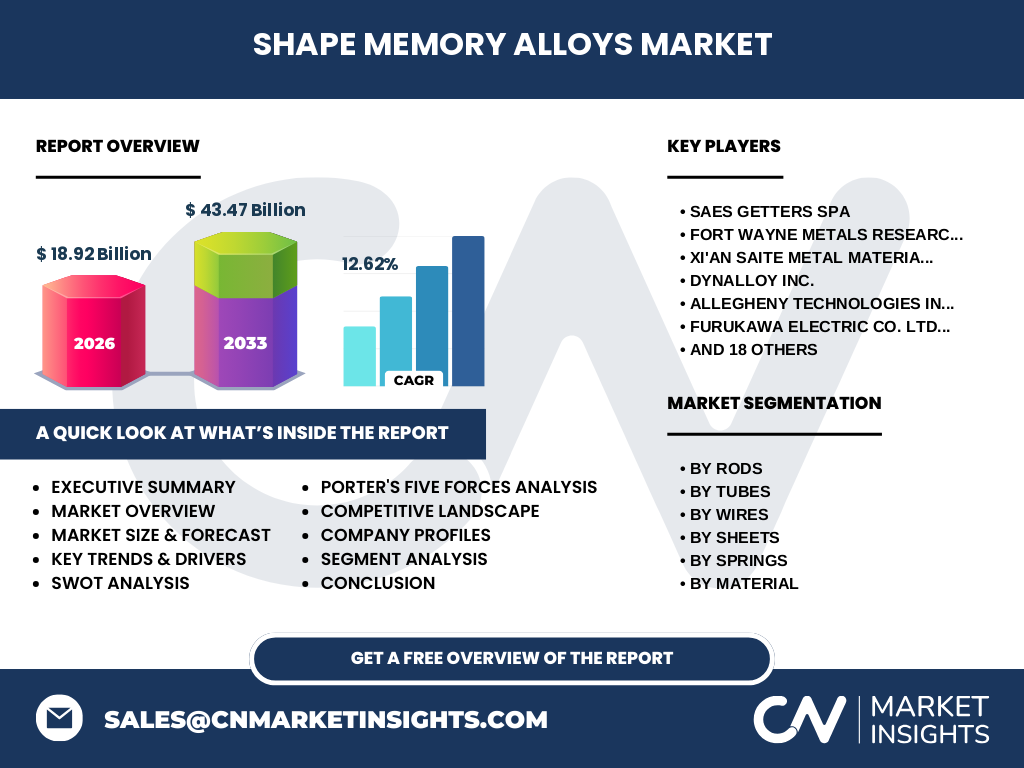
Our analysis indicates that the Shape Memory Alloys Market commands a valuation of 18.92 Billion in 2026. These advanced metallic materials, capable of recovering their original shape upon thermal or mechanical stimulus, are critical for high-precision engineering in aerospace actuators and minimally invasive surgical tools.
Structural Growth Drivers and Market Restraints
Growth is propelled by surging demand for miniaturized biomedical stents and aerospace deployment mechanisms. However, stringent FDA and ISO biocompatibility standards create severe regulatory compliance costs, while volatile nickel and titanium raw material costs constrain operating margins across tier-one manufacturers.
Emerging Trends in the Shape Memory Alloys Market
The shift toward magnetic-driven shape memory alloys and additive manufacturing is redefining product capabilities. Innovators are leveraging 3D printing to fabricate complex lattice structures, reducing component weight for aerospace giants like Allegheny Technologies Incorporated and Confluent Medical Technologies India Pvt. Ltd.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted elective surgeries and global aerospace supply chains, suppressing near-term revenues. Recovery has been robustly steered by elective procedure backlogs and heightened government spending on defense electronics, allowing key players to rebuild order backlogs rapidly.
Competitive Landscape and Strategic Dynamics
The market features moderate consolidation, dominated by specialized metallurgy leaders. Firms like SAES Getters SpA, Fort Wayne Metals Research Products Corp., and Furukawa Electric Co. Ltd. maintain strong competitive moats through proprietary thermomechanical processing and extensive patent portfolios.
Executive Summary of the Shape Memory Alloys Market
Our comprehensive evaluation confirms that the Shape Memory Alloys Market industry trends point toward exponential expansion, driven by biomedical advancements and automotive actuator integration. Strategic investments in continuous vacuum melting will dictate market leadership over the next decade.
Market Forecast from 2027 to 2033
The data projects the market to reach 43.47 Billion by 2033, expanding at a robust 12.62% CAGR. This accelerated trajectory reflects widespread commercial adoption across consumer electronics and smart home appliances demanding high actuation fatigue life.
Segmentation Analysis of Product and Material Categories
Segmentation spans Rods (solid/hollow), Tubes (straight/coiled), Wires (standard/specialty), Sheets, and Springs, alongside Nickel-Titanium and Copper-Based materials. Nitinol-based wires dominate biomedical catheters, while iron-based alloys gain traction in cost-sensitive automotive actuation.
Regional Market Analysis and Geographic Distribution
North America leads consumption due to advanced aerospace hubs and stringent FDA medical device approvals. Meanwhile, the Asia-Pacific region exhibits the fastest regional growth rate, propelled by expanding automotive manufacturing centers in Japan and South Korea.
In-Depth Regional Review
European markets focus heavily on high-end industrial automation and luxury automotive applications, regulated by stringent REACH directives. Conversely, North American growth concentrates on defense contracting through firms like Dynalloy Inc. and specialized biomedical clusters in California and Minnesota.
Company Profiles and Market Positioning
Leading entities such as Admedes Schuessler GmbH and Memry Corporation focus on medical-grade Nitinol processing. Meanwhile, industrial conglomerates like Mitsubishi Materials Corporation and Alcoa Corporation leverage extensive distribution networks to supply bulk sheets and rods globally.
Porter's Five Forces Analysis
Supplier power is moderately high due to the specialized sourcing of high-purity titanium sponge. Threat of substitutes remains low given the unique superelasticity and biocompatibility profiles that conventional engineering plastics and stainless steels simply cannot replicate.
SWOT Analysis of the Industry
Core strengths include exceptional fatigue resistance and shape recovery. Weaknesses involve complex machining requirements. Opportunities lie in smart wearable technology, while primary threats stem from geopolitical trade tariffs impacting critical raw material imports.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with vacuum induction melting of raw elements, proceeding through precision wire drawing by Boston Centerless Inc. and tube manufacturing by Memry Corporation, culminating in final integration by device OEMs in biomedical and aerospace sectors.
Investment Insights and Strategic Recommendations
High-potential areas include scaling laser-powder-bed fusion for custom cranial plates and investing in proprietary surface modification techniques to prevent nickel ion leaching in long-term implants. Venture capital should target early-stage developers specializing in magnetic shape memory actuators.
Conclusion and Key Takeaways
The Shape Memory Alloys Market analysis demonstrates that technological mastery in thermomechanical tuning is the ultimate differentiator. Companies failing to adopt advanced precision drawing risk margin erosion in high-value medical applications.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with chief metallurgists, and secondary macroeconomic indicators from industrial manufacturing associations across North America, Europe, and Asia-Pacific.
Scope of the Report and Coverage Parameters
This report covers global revenue estimations from 2026 to 2033 across five primary end-use industries and six distinct product configurations. Limitations exclude uncommercialized laboratory-scale alloy compositions lacking verified industrial durability metrics.
Recent Developments and Strategic Moves
Recent industry momentum features strategic facility expansions by Confluent Medical Technologies and joint ventures focused on scaling continuous casting lines for Nitinol tubing. These moves aim to eliminate supply bottlenecks for cardiovascular stent manufacturers worldwide.