Executive summary of the Gear Oil Market
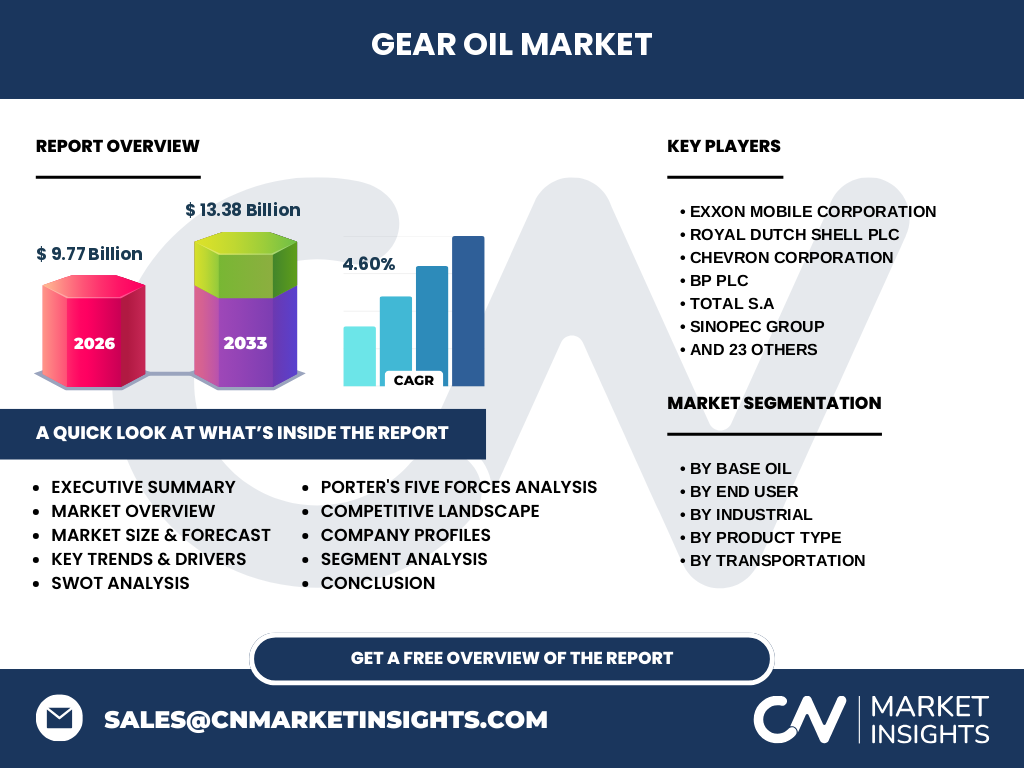
Our analysis indicates that the Gear Oil Market is poised for robust expansion, scaling from a baseline of 9.77 Billion to reach 13.38 Billion by 2033. Achieving a steady CAGR of 4.60%, this trajectory is underpinned by rising industrialization, heavy machinery utilization, and a global shift toward high-performance synthetic lubricants managed by major enterprise players.
What is the scope and significance of the Gear Oil Market?
The Gear Oil Market governs high-viscosity lubricants formulated specifically for transmissions, transfer cases, and differentials in automotive and industrial machinery. Its industry significance lies in reducing friction and thermal degradation across severe operating conditions, directly impacting equipment uptime for heavy-duty manufacturing and mining infrastructure worldwide.
Structural Growth Drivers and Restraints
Growth is heavily propelled by expanding manufacturing output and construction activities demanding durable industrial gear oils. However, the market faces restraints from volatile raw material prices for base oils and stringent environmental compliance mandates from regulatory bodies like the EPA, which challenge traditional formulation margins.
Emerging Industry Trends in the Gear Oil Market
A definitive trend is the rapid adoption of bio-based oil and synthetic formulations designed to extend drain intervals and reduce carbon footprints. Industry pioneers are increasingly investing in eco-friendly biodegradable gear oils to comply with stricter ISO standards and cater to environmentally sensitive forestry and agriculture sectors.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains and temporarily stalled manufacturing and automotive production lines, depressing short-term demand. The subsequent recovery trajectory has been robust, driven by stimulus-backed infrastructure projects and a pent-up industrial demand surge that accelerated modernization initiatives across global supply networks.
Competitive Benchmarking and Market Concentration
The Gear Oil Market industry trends reveal high market concentration among multinational energy conglomerates and specialty chemical producers. Industry leaders like Exxon Mobil Corporation, Royal Dutch Shell PLC, and Chevron Corporation leverage proprietary additive packages and extensive global distribution networks to maintain formidable competitive moats against regional competitors.
Gear Oil Market Forecast from 2027 to 2033
Driven by compounding industrial demand, our research forecasts the market to expand from its 2026 foundation through 2033 at a steady 4.60% CAGR. This expansion will steadily close the gap toward the 13.38 Billion valuation mark, heavily favored by technological upgrades in heavy-duty machinery.
Segmentation Analysis by Base Oil and End User
Segmentation spans base oils including Mineral Oil, Synthetic Oil, Semi Synthetic Oil, and Bio Based Oil, serving end-users across manufacturing, construction, agriculture, oil and gas, and mining. Synthetic variants capture premium margins due to superior thermal stability in extreme industrial applications.
Regional Market Analysis and Geographic Distribution
Geographic performance is heavily anchored by industrial output concentrations in Asia-Pacific, North America, and Europe. Rapid urbanization and mining expansions drive exceptional regional volume consumption, while mature European markets prioritize advanced synthetic and biodegradable formulations to meet strict environmental mandates.
In-Depth Regional Review of High-Growth Zones
Asia-Pacific dominates volume consumption due to massive manufacturing hubs in China and India, supported by entities like Sinopec Group and Petrochina Company Limited. Meanwhile, North American demand centers on heavy-duty transportation and shale oil extraction, heavily serviced by regional leaders like Phillips 66 Company and Valvoline Inc.
Strategic Positioning of Leading Companies
Industry giants such as Total S.A., BP PLC, and Idemitsu Kosan Company Ltd. focus heavily on co-engineering lubricants with original equipment manufacturers. This strategic positioning ensures proprietary lubricant specs for high-precision industrial machinery and specialized automotive transmissions, driving long-term customer retention.
Porter's Five Forces Analysis of the Industry
Supplier power remains moderate due to commodity base oil price fluctuations, while buyer power is high given the presence of major fleet operators and manufacturing conglomerates. Threat of substitutes is mitigated by specialized OEM specifications, though rising bio-based alternatives introduce dynamic competitive pressures.
SWOT Analysis of the Gear Oil Market
Key strengths include robust product necessity in heavy industries and high switching costs for specialized synthetics. Weaknesses involve sensitivity to crude oil pricing. Opportunities lie in biodegradable formulations for emerging markets, while threats include aggressive environmental regulations targeting petroleum-based lubricant disposal.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with crude oil refiners and chemical additive manufacturers supplying base stocks and performance packages. Formulators like Castrol Limited and Fuchs Petrolub SE blend these inputs into branded gear oils, distributing them via maritime ports and logistics hubs directly to industrial end-users.
Investment Insights and High-Potential Areas
High-potential investment avenues lie in synthetic and bio-based industrial gear oils that cater to strict sustainability mandates. Investors should target portfolios aligned with electric vehicle transmission fluids and specialized lubricants designed for high-stress renewable energy infrastructure like wind turbine gearboxes.
Conclusion and Key Takeaways for Stakeholders
The Gear Oil Market market size is firmly anchored on a path to reach 13.38 Billion by 2033, underpinned by a 4.60% CAGR. Success in this sector requires continuous R&D investment in synthetic and eco-friendly formulations to capture high-margin opportunities across shifting industrial landscapes.
Research Methodology and Data Triangulation
Our proprietary market estimation triangulates data by synthesizing customs trade registries, primary stakeholder interviews with lubricant formulators, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of the 9.77 Billion baseline and forecasts through rigorous cross-validation.
Scope of the Report and Coverage Parameters
This report evaluates the global Gear Oil Market analysis across comprehensive parameters, including base oil types, end-user verticals, and transportation applications. Limitations include unforeseen macroeconomic policy shifts and sudden geopolitical disruptions affecting global lubricant feedstock logistics.
Recent Developments and Strategic Industry Moves
Recent market activities feature strategic mergers, eco-friendly product launches, and long-term supply partnerships. Companies like Lukoil Oil Company and Liqui Moly GmbH have accelerated investments in low-viscosity, fuel-efficient gear formulations, aligning with global automotive decarbonization goals and stringent industrial efficiency standards.