Market overview of the Lubricant Filtration Market
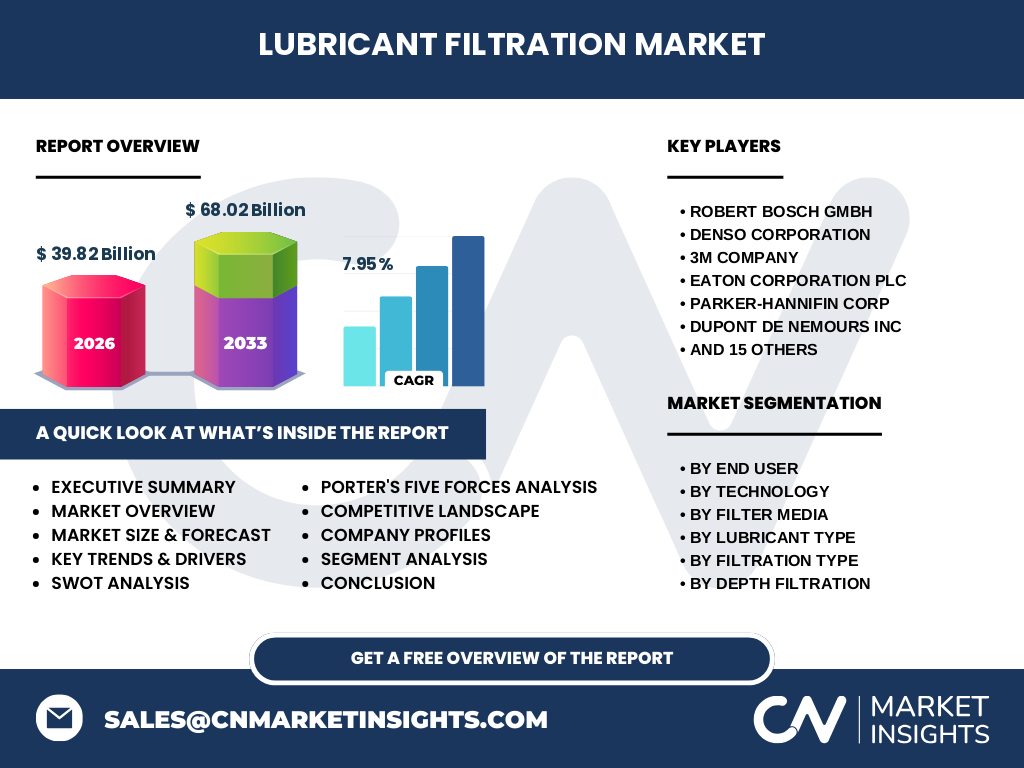
Our analysis indicates that the Lubricant Filtration Market market size stands at 39.82 Billion in 2026. This sector encompasses critical purification technologies safeguarding rotating machinery, internal combustion engines, and hydraulic systems across heavy industries by eliminating particulate contaminants and varnish.
Structural Growth Drivers and Restraints
Stringent ISO cleanliness standards mandated by bodies like OSHA and the EPA act as primary catalysts. Conversely, high capital expenditures for synthetic media upgrades and supply chain bottlenecks for specialty cellulose pose significant operational hurdles for system manufacturers.
Emerging industry trends in the Lubricant Filtration Market
The market is witnessing a rapid pivot toward integrated condition monitoring sensors embedded directly into housing units. This shift favors innovators capable of pairing traditional cellulose or synthetic depth media with real-time oil degradation telemetry.
COVID-19 impact and recovery trajectory
Pandemic-era supply chain disruptions temporarily depressed original equipment manufacturing output across marine and aviation sectors. However, accelerated post-pandemic automation investments in industrial machinery catalyzed a robust rebound, steering the industry toward its 2027-2033 expansion phase.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features intense rivalry among filtration giants such as Parker-Hannifin Corp, Donaldson Company Inc, and Pall Corporation. These market leaders maintain dominance through proprietary synthetic fiber patents and aggressive aftermarket distribution networks.
Executive Summary of the Lubricant Filtration Market
Driven by rising automation across industrial machinery, the Lubricant Filtration Market industry trends point to sustained multi-sector expansion. Strategic investments in high-capacity depth filters will dictate market leadership through the next decade.
Market Forecast for 2027 to 2033
The data suggests the market will surge to 68.02 Billion by 2033, expanding at a robust CAGR of 7.95% starting from 2027. This growth trajectory underscores surging industrial demand for extended fluid lifecycles and reduced maintenance downtime.
Segmentation Analysis by Technology and Media
Our research segments the market by End User, Technology (Centrifugal, Pressure, Vacuum), Filter Media (Cellulose, Synthetic, Blend), Lubricant Type, and Filtration Type. Synthetic-based media dominate high-stress hydraulic and aviation applications due to superior thermal stability.
Regional Market Distribution and Performance
Geographic performance varies significantly, with North America and Europe leading in adoption of advanced synthetic and electrostatic filtration systems. Meanwhile, Asia-Pacific exhibits the fastest regional acceleration, propelled by rapid manufacturing automation and expanding commercial fleets.
In-Depth Regional Review
Industrial hubs across Germany, China, and the United States anchor regional demand. Strict environmental regulations in Europe compel OEMs to adopt high-efficiency membrane surface filtration, while industrial expansion in developing Asian economies prioritizes cost-effective cellulose blend filters.
Company Profiles and Market Positioning
Industry stalwarts like Mann+Hummel GmbH and Alfa Laval AB leverage localized manufacturing to mitigate logistical risks. Concurrently, specialized innovators such as Filtrox AG carve out lucrative niches in high-purity pharmaceutical and heavy industrial depth filtration applications.
Porter's Five Forces Analysis
Supplier power remains moderate due to raw material dependencies for synthetic resins and cellulose fibers. Buyer power is high, as major automotive and industrial conglomerates demand custom filtration specifications at competitive price points.
SWOT Analysis of the Industry
Key strengths include robust patent portfolios held by 3M Company and EATON CORPORATION plc. Primary threats involve raw material price volatility and the long-term electrification trend reducing internal combustion engine oil filtration requirements.
Value Chain Analysis
The value flow initiates with petrochemical and cellulose raw material suppliers, progressing to specialized media converters like Hollingsworth & Vose. Finished filtration assemblies then flow through tier-one suppliers to heavy machinery OEMs and maintenance aftermarket channels.
Investment Insights and Strategic Opportunities
High-potential capital allocation centers on smart filtration IoT integration and eco-friendly biodegradable filter media. Investors should target mid-tier European and North American manufacturers possessing proprietary microfilter surface filtration patents.
Conclusion and Key Takeaways
The Lubricant Filtration Market industry analysis confirms that technological convergence between mechanical filtration and digital monitoring is reshaping competitive boundaries, ensuring resilient expansion toward the 2033 valuation milestone.
Research Methodology
Baseline estimates are meticulously triangulated by combining proprietary customs trade registries, primary qualitative interviews with engineering executives at Mahle GmbH and Hengst SE & Co. KG, and secondary macroeconomic indicators from global manufacturing indices.
Scope of the Report
This report covers global revenue estimations and volume shipments from 2026 through 2033. Analysis parameters encompass primary end-user verticals, regional manufacturing outputs, and regulatory compliance frameworks governing industrial lubrication standards.
Recent Developments and Strategic Moves
Recent industry momentum highlights strategic joint ventures and eco-friendly product launches. For instance, Freudenberg Filtration Technologies SE & Co. KG recently expanded its sustainable media portfolio, aligning with global corporate decarbonization mandates.