What is the scope and industry significance of the Filament Tapes Market?
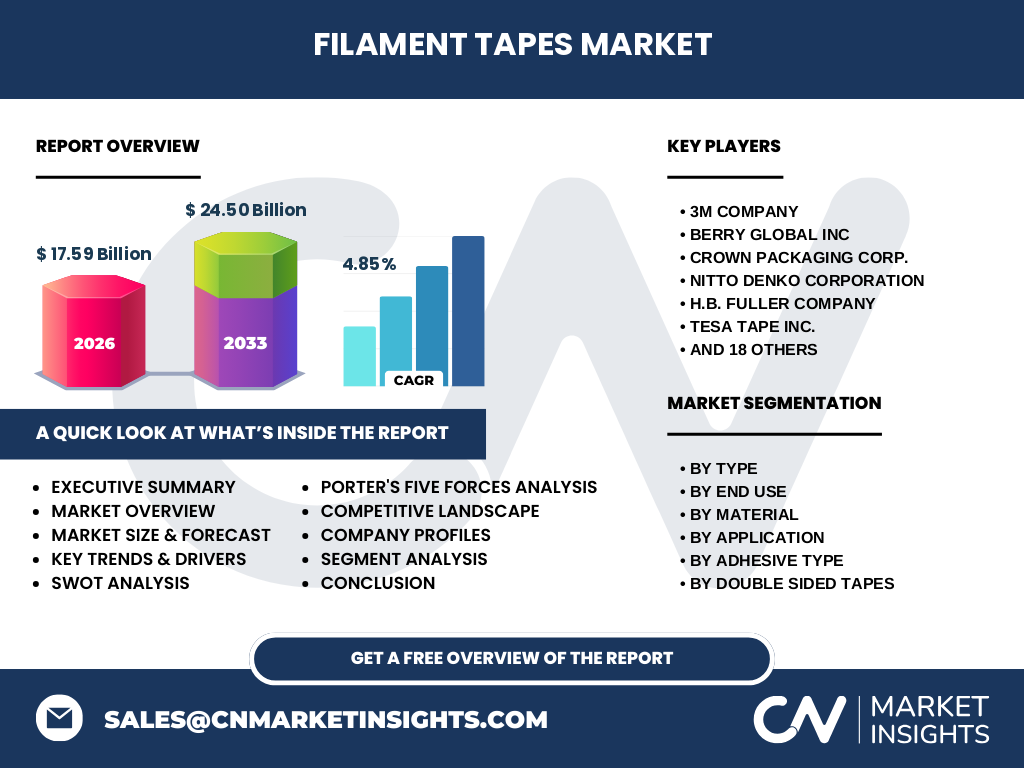
Our analysis indicates that the Filament Tapes Market represents a critical pillar in heavy-duty packaging and industrial bundling, valued at 17.59 Billion in 2026. This sector encompasses high-tensile fiberglass and polyester-reinforced solutions governed by ASTM standards, serving demanding logistical corridors globally.
Structural Growth Drivers and Restraints in the Filament Tapes Industry
The market is propelled by robust e-commerce logistics and heavy manufacturing expansion, yet constrained by volatile petrochemical feedstock costs such as polypropylene and rubber. Regulatory pressures from OSHA compliance regarding workplace safety further dictate adhesive formulations.
Emerging Trends and Growth Patterns in Filament Tapes Market
Industry trends highlight a decisive shift toward eco-friendly backing materials and water-activated adhesives to meet stringent EU packaging directives. Sustainable innovation is reshaping product development across major manufacturing hubs.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains for raw fiberglass and synthetic rubber, causing temporary manufacturing bottlenecks. However, accelerated e-commerce demand fueled a rapid post-pandemic recovery, stabilizing operational output across primary industrial sectors.
Competitive Landscape and Strategic Dynamics
Market concentration remains moderately high, with industry leaders like 3M Company, Nitto Denko Corporation, and Tesa Tape Inc. dominating through proprietary adhesive technologies. Strategic mergers and localized manufacturing expansions serve as primary competitive differentiators.
Executive Summary of the Filament Tapes Market Report
Our research projects the Filament Tapes Market to expand from 17.59 Billion in 2026 to 24.50 Billion by 2033, registering a steady CAGR of 4.85%. Growth is heavily concentrated in heavy-duty shipping, automotive, and construction end-uses.
Market Forecast and Valuation Trajectory through 2033
Driven by robust industrial demand across Asia-Pacific and North America, the market valuation is set to scale significantly. Reaching 24.50 Billion by 2033 at a 4.85% CAGR underscores long-term sectoral resilience.
Comprehensive Segmentation Analysis of Filament Tapes Market
The market is segmented by type into Single Sided Tapes and Double Sided Tapes, utilizing materials like paper, foam, fabric, polyester, and mesh fiber glass. End-uses span shipping and logistics, electrical and electronics, automotive, and building and construction.
Regional Market Analysis and Geographic Distribution
Geographic performance highlights North America and Asia-Pacific as primary revenue generators, supported by dense manufacturing ecosystems and major container ports. Localized environmental regulations significantly influence regional adhesive preferences.
In-Depth Regional Review of High-Growth Industrial Corridors
Asia-Pacific dominates volume consumption due to sprawling electronics manufacturing in China and Taiwan, alongside booming automotive production in India. Meanwhile, North America emphasizes high-performance acrylic and rubber-based solutions complying with FDA and ASTM standards.
Company Profiles and Strategic Positioning of Leading Market Players
Key industry participants such as Berry Global Inc, H.B. Fuller Company, and Shurtape Technologies LLC leverage extensive global distribution networks. Meanwhile, regional players like Viraj Industries Limited and Ajit Industries Private Limited capture domestic market share through cost-optimized manufacturing.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power remains moderate due to consolidated chemical feedstock providers, whereas buyer power is high given the commoditized nature of standard carton sealing applications. Threat of substitutes is mitigated by the unmatched tensile strength of reinforced filament designs.
SWOT Analysis of the Global Filament Tapes Sector
Strengths include exceptional tensile strength and load containment capabilities. Weaknesses involve sensitivity to raw material price fluctuations. Opportunities lie in biodegradable backing materials, while threats stem from aggressive pricing pressures by unbranded regional manufacturers.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with petrochemical refiners supplying base films and rubber resins, progressing through specialized coating and slitting by converters like Saint-Gobain Performance Plastics Corporation, and concluding with industrial end-users via tier-one distributors.
Investment Insights and High-Potential Areas
Strategic investments should target bio-based adhesive formulations and high-tack double-sided tapes for electronics assembly. Capitalizing on localized manufacturing in emerging Southeast Asian economies offers superior margin expansion opportunities.
Conclusion and Strategic Takeaways for Industry Stakeholders
Sustained growth through 2033 rewards companies that successfully balance cost-efficiency with sustainable product innovation. Stakeholders must prioritize R&D in eco-friendly reinforcements to future-proof their portfolios against tightening global regulations.
Research Methodology and Data Triangulation Process
Baseline estimates are triangulated by cross-referencing international trade registry data, primary executive interviews with supply chain leaders, and secondary macroeconomic indicators from industrial associations to ensure absolute market accuracy.
Scope of the Report and Coverage Parameters
This report covers global revenue estimations from 2026 to 2033, analyzing detailed breakdowns across adhesive types, backing materials, and end-use verticals. Limitations include unforeseen geopolitical trade disruptions and rapid macroeconomic shifts.
Recent Developments, Partnerships, and Product Launches
Recent strategic moves feature major capacity expansions by Nitto Denko Corporation and new sustainable product rollouts by 3M Company. These initiatives target carbon-neutral packaging mandates and enhanced high-temperature resistance for industrial applications.