Market overview and structural scope of the Managed Print Services Market
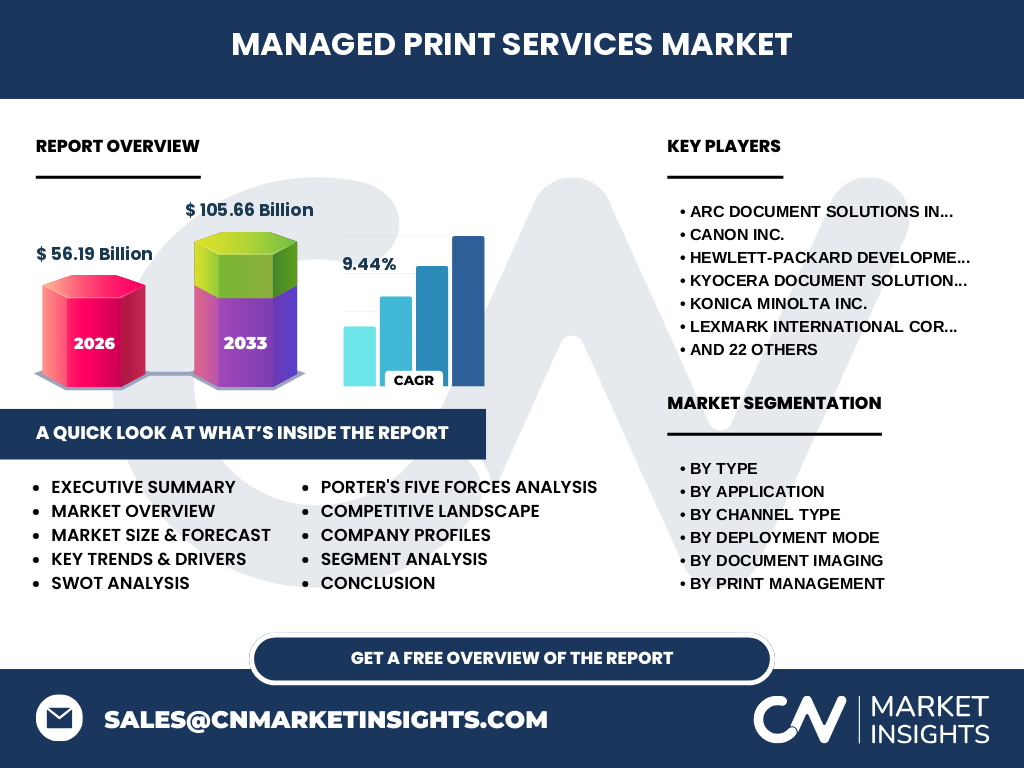
Our analysis indicates that the Managed Print Services Market represents a critical enterprise optimization tier, valued at 56.19 Billion in 2026. This sector encompasses outsourced administration of hardcopy output infrastructure, spanning Print Management and Device Management. By streamlining fleet utilization, organizations mitigate supply chain friction involving paper pulp and toner chemicals while adhering to stringent compliance mandates like GDPR.
Structural Growth Drivers and Market Restraints
Growth is heavily propelled by enterprise transition toward hybrid work models, yet restrained by lingering supply chain bottlenecks in semiconductor components essential for multi-function printers. Opportunities flourish within Workflow Automation and cloud deployments, allowing firms to bypass legacy on-premise hardware constraints while optimizing operating expenditures across distributed office topologies.
The Shift Toward Advanced Digital Transformation
Industry trends reveal an aggressive pivot from basic print output reduction to comprehensive Digital Document Management and Document Scanning Services. Enterprises increasingly demand intelligent data capture solutions that interface directly with enterprise resource planning systems, reducing manual processing overhead and transforming static paper archives into searchable, actionable digital assets.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
The pandemic drastically compressed print volumes as corporate offices shuttered, forcing a structural migration toward Cloud-Based fleet management. The recovery trajectory is characterized by resilient expansion at a 9.44% CAGR through 2033, driven by distributed workforce support requirements and heightened enterprise focus on secure, zero-trust remote printing architectures.
Competitive Benchmarking and Market Concentration
The competitive landscape features intense rivalry among hardware titans and independent software vendors. Industry leaders such as Hewlett-Packard Development Company L.P., Xerox Corporation, and Canon Inc. leverage proprietary fleet intelligence tools. Meanwhile, specialized challengers like PrintFleet and Print Audit carve out profitable niches via device-agnostic monitoring software.
Executive Summary of the Managed Print Services Market
Our research forecasts the Managed Print Services Market to expand from 56.19 Billion in 2026 to 105.66 Billion by 2033, achieving a robust 9.44% CAGR. Strategic adoption of Discovery And Design assessments combined with automated Supply Management remains vital for enterprise cost containment and sustainability compliance.
Market Forecast and Long-Term Valuation (2027-2033)
Based on our econometric modeling, the market trajectory from 2027 to 2033 will nearly double industry valuation, culminating at 105.66 Billion. This expansion is sustained by continuous enterprise upgrades across Large Enterprises and Small And Medium Enterprises (SMEs) seeking outsourced vendor expertise to manage complex, multi-vendor print ecosystems.
Granular Segmentation Analysis
Segmentation spans multiple dimensions: by type, covering Print Management and Document Imaging; by channel, including System Integrators Or Resellers; and by deployment, balancing On-premise against Cloud-Based and Hybrid architectures. Each segment serves specific operational needs, from Print Policy Development to advanced Workflow Analysis.
Geographic Distribution and Regional Performance
Regional performance varies due to regulatory maturity and digital infrastructure readiness. North America maintains dominant market share driven by early cloud adoption in the BFSI and Government sectors, whereas Asia-Pacific demonstrates the fastest growth acceleration fueled by rapid manufacturing expansion and expanding IT infrastructure.
In-Depth Regional Review and Localized Constraints
In European markets, strict environmental regulations enforced by the European Union compel providers to emphasize sustainable toner recycling and energy-efficient Printer And Copier Management. Conversely, North American adoption focuses heavily on strict data security protocols within Healthcare and Legal verticals to safeguard confidential client documents.
Strategic Positioning of Leading Enterprise Providers
Market participants like Ricoh Company Ltd., Konica Minolta Inc., and Kyocera Document Solutions Inc. differentiate through proprietary enterprise software suites and robust global service networks. Firms such as Lexmark International Corporation focus on specialized fleet security, while service aggregators like Staples Managed Print Services capture SMB demand.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of buyers remains high due to fierce vendor competition and standardized hardware offerings. Threat of substitutes is moderate to high, accelerated by paperless office initiatives. However, high switching costs associated with integrated Custom Print Solutions Design help established providers retain enterprise accounts over multi-year contract cycles.
SWOT Analysis of the Managed Print Services Sector
Key strengths include predictable recurring revenue models and deep enterprise client integration. Weaknesses involve high initial onboarding complexity. Opportunities lie in expanding Workflow Automation capabilities, while primary threats stem from ongoing cyber threats targeting connected multi-function peripherals and aggressive enterprise paper-reduction mandates.
Value Chain Analysis and Industry Structure
The value chain initiates with raw material sourcing for paper and chemical colorants, moving through original equipment manufacturing by firms like Sharp Corporation and Toshiba Corporation. Value flows through Independent Software Vendors (ISVs) and channel partners before delivering optimized print environments to end-user verticals like Telecom And IT.
Investment Insights and High-Potential Growth Pockets
Investors should direct capital toward cloud-native service platforms and AI-driven Device Monitoring And Maintenance capabilities. High-potential opportunities exist in underserved Small And Medium Enterprises (SMEs) transitioning to hybrid operational structures, favoring scalable software subscription models over traditional hardware-tethered service agreements.
Conclusion and Strategic Industry Takeaways
The Managed Print Services Market is transitioning from a hardware-centric maintenance model into a sophisticated document workflow optimization discipline. Reaching 105.66 Billion by 2033 requires providers to pivot toward advanced security integration, cloud orchestration, and automated supply chain replenishment to secure long-term enterprise contracts.
Proprietary Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by synthesizing trade registry statistics, primary stakeholder interviews with c-level executives across leading firms like Fujitsu Limited and Unisys Corporation, and secondary macroeconomic indicators. This multi-tiered validation guarantees precise quantification of market segments and regional growth trajectories.
Scope of the Report and Analytical Parameters
This report covers global deployment parameters across eight core industry verticals and three primary channel types. Limitations exclude localized regional print shops operating outside formal enterprise managed contracts, focusing exclusively on structured enterprise-grade managed print engagements spanning Small And Medium Enterprises (SMEs) and Large Enterprises.
Recent Industry Developments and Strategic Corporate Moves
Recent strategic activity highlights aggressive portfolio diversification. Industry participants including Novatech Inc. and Comarch SA have forged strategic partnerships to integrate advanced cybersecurity protocols directly into device firmware. Concurrently, product launches from Brother UK Ltd. emphasize compact, eco-friendly devices tailored for decentralized hybrid work environments.