Market overview and structural significance of the Tennis Market
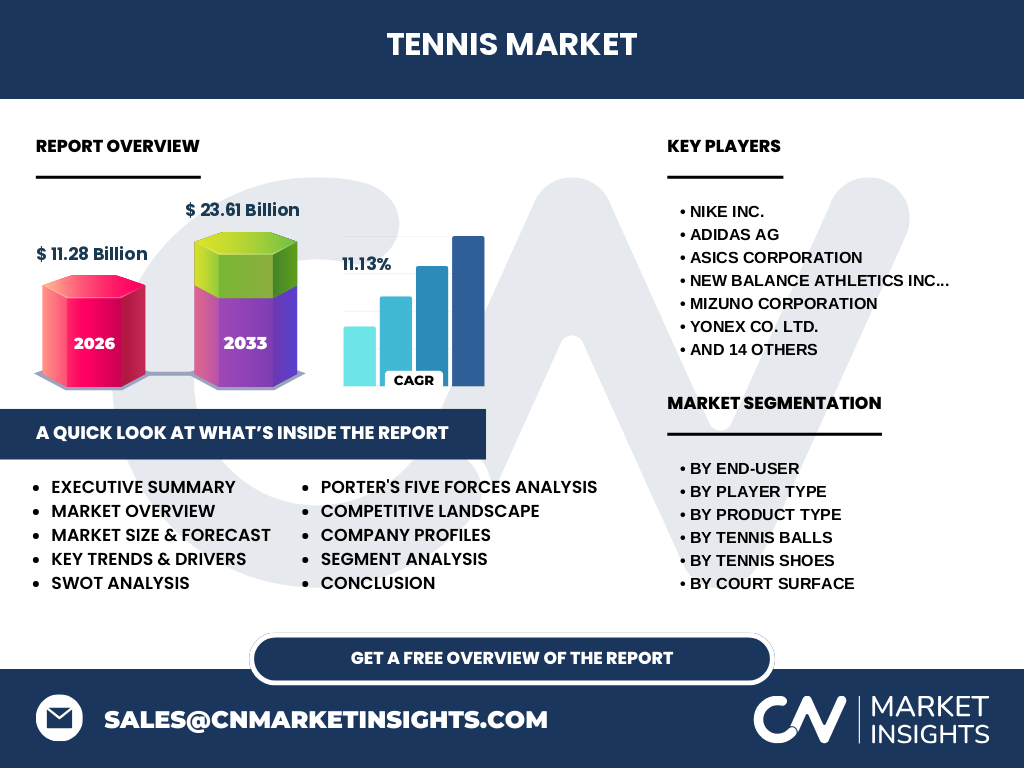
The Tennis Market represents a robust global sector valued at 11.28 Billion in 2026, encompassing specialized manufacturing of racquets, strings, footwear, and court infrastructure. Our analysis indicates the industry underpins a vast ecosystem of professional tours, localized clubs, and retail channels, governed by stringent regulatory standards from bodies like the International Tennis Federation.
What key market drivers, restraints, challenges, and opportunities shape the Tennis Market?
Growth is propelled by rising disposable incomes and televised tournament viewership, while supply chain bottlenecks for raw graphite and natural rubber act as restraints. High equipment import tariffs in developing economies present persistent challenges, yet direct-to-consumer digital expansion opens lucrative cross-border opportunities for agility-focused brands.
Emerging trends and growth patterns in the Tennis Market
The industry is witnessing an accelerated pivot toward eco-friendly manufacturing, utilizing recycled polymers for Pressurized Balls and biodegradable packaging. Advanced sensor-embedded racquets are gaining traction among competitive players, transforming traditional gear into data-driven performance tools monitored via proprietary mobile applications.
COVID-19 impact analysis and recovery trajectory
Pandemic-era social distancing restrictions initially paralyzed club operations and supply chains across major manufacturing hubs, yet outdoor socially distanced play sparked a massive recreational participation surge. The recovery trajectory has been exceptionally strong, driven by localized infrastructure investments and unprecedented equipment restocking cycles globally.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of multinational athletic giants and specialized heritage brands. Firms like Nike Inc. and Adidas AG dominate apparel and footwear, while technical specialists such as Head Sport GmbH and Babolat control professional racquet and string segments through aggressive athlete endorsements.
Executive summary of key findings
Our comprehensive evaluation confirms the Tennis Market is poised for unprecedented expansion, driven by technological integration and broadening demographic appeal. Key stakeholders must prioritize digital retail agility and sustainable material sourcing to capture maximum value from the projected high-growth trajectory ahead.
Market forecast trajectory from 2027 to 2033
Our forecast models project the market to surge from its baseline toward an impressive valuation of 23.61 Billion by 2033, expanding at a robust CAGR of 11.13%. This accelerated expansion reflects sustained participation rates, premiumization of gear, and surging demand across emerging economies.
Segmentation analysis across product, player, and surface categories
The market is comprehensively segmented by End-User (Men, Women, Kids), Player Type (Professional, Recreational, Beginner, Intermediate, Advanced), Product Type (Racquets, Balls, Shoes, Strings), and Court Surface (Hard, Clay, Grass, Carpet, Indoor). Each tier addresses specific biomechanical needs, with Hard Court Shoes and Graphite Racquets commanding significant revenue shares.
Regional market analysis and geographic performance
Geographic performance highlights North America and Europe as dominant revenue generators due to dense club infrastructure and high disposable incomes. Meanwhile, the Asia-Pacific region exhibits the fastest-growing adoption rate, fueled by expanding middle-class demographics and prominent tournament expansions in nations like China and Japan.
In-depth regional review of key markets
North America remains anchored by vast municipal court networks and robust retail channels, whereas Europe benefits from deeply entrenched tennis club traditions and stringent ITF surface compliance standards. Emerging Asia-Pacific markets demonstrate localized preferences for multi-purpose All-Court Shoes and durable synthetic strings suited for hard court surfaces.
Strategic positioning of leading company profiles
Industry leaders deploy distinct positioning strategies: Yonex Co. Ltd. and Amer Sports Inc. leverage cutting-edge material science for elite racquets, while ASICS Corporation and New Balance Athletics Inc. capture market share through specialized podiatric engineering in tennis footwear for Clay Court and hard court play.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to specialized carbon fiber and natural rubber sourcing requirements, whereas buyer power is high given the abundance of alternative retail brands. Competitive rivalry is intensely fierce among established racquet innovators, while the threat of new entrants is mitigated by high R&D and patent barriers.
SWOT analysis of the Tennis Market
Core strengths include strong brand heritage and high consumer loyalty, balanced against weaknesses like vulnerability to raw material price volatility. Opportunities lie in digital coaching platforms and expanding youth programs, while threats involve counterfeit equipment proliferation and macroeconomic inflation dampening discretionary spending.
Value chain analysis from raw materials to end-users
The value flow initiates with petrochemical refiners and raw graphite suppliers, transitioning through specialized manufacturing facilities in Asia before reaching distribution hubs via major global ports. The chain concludes through Online Retail, specialized offline sporting goods stores, and exclusive club pro shops.
Investment insights and high-potential areas
Strategic capital should target sustainable manufacturing innovations, particularly recyclable Pressurized Balls and bio-based Natural Gut Strings alternatives. Investors should also evaluate direct-to-consumer digital platforms and smart-court sensor technologies as high-margin growth vectors over the forecast window.
Conclusion and key strategic takeaways
The data confirms that navigating the evolving tennis landscape requires balancing heritage brand trust with aggressive digital and sustainable transformation. Companies that align product portfolios with the surging demand for specialized footwear and advanced graphite racquets will capture disproportionate market gains.
Research methodology for baseline estimation
Our baseline estimates are rigorously triangulated by combining customs trade registry datasets, primary stakeholder interviews with sporting goods executives, and secondary macroeconomic indicators. This multi-tiered approach ensures granular accuracy across all regional and product segment valuations.
Scope of the report and coverage parameters
This report evaluates the global Tennis Market across established geographic zones, analyzing all primary product tiers, distribution channels, and player demographics from 2026 to 2033. Exclusions involve unorganized local grey-market apparatus and non-tennis racquet sports such as pickleball or badminton.
Recent developments in company announcements and partnerships
Recent industry moves highlight major players like Fila Holdings Corp. and Sumitomo Rubber Industries Ltd. securing multi-year tournament sponsorships and launching eco-conscious product lines. Strategic mergers among independent string manufacturers and footwear innovators continue to reshape the competitive landscape.