What is the scope and industry significance of the Sheet Metal Market?
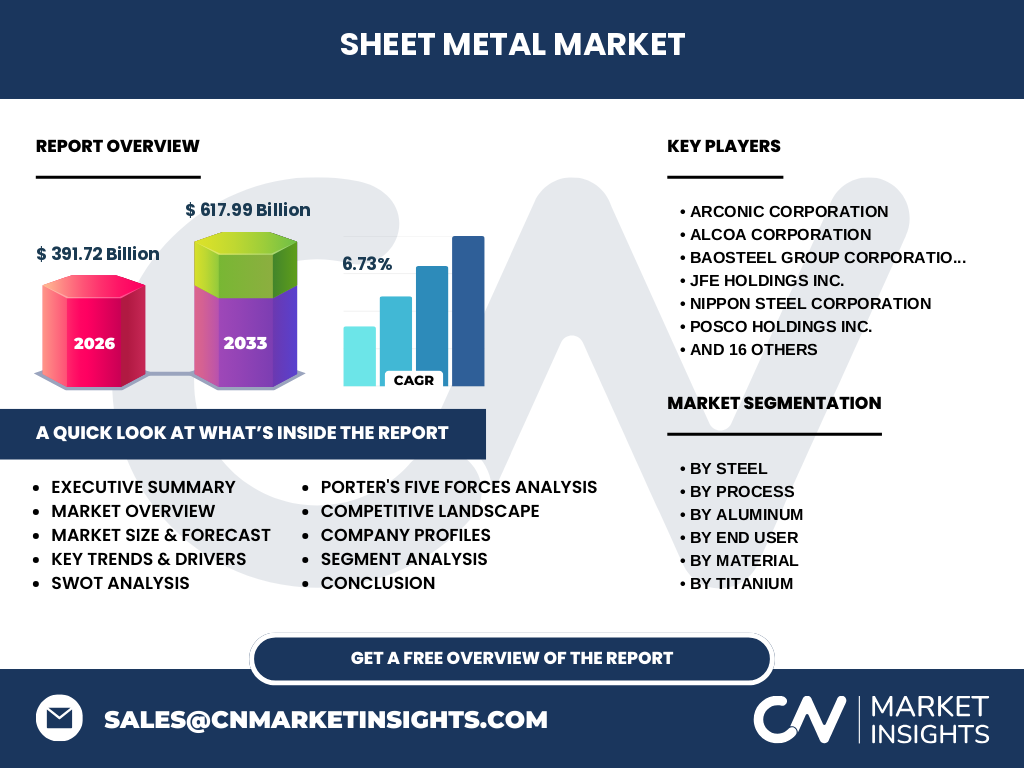
Our analysis indicates that the Sheet Metal Market represents a foundational pillar of modern manufacturing, encompassing advanced processing of materials like carbon steel, aluminum, and titanium. Valued at $391.72 Billion in 2026, this sector drives precision fabrication across automotive, aerospace, and construction verticals, requiring stringent compliance with ASTM and ISO metallurgical standards.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
The market is propelled by lightweighting demands in electric vehicles and stringent carbon emission regulations set by the EPA and EU. However, margin pressures from raw material price volatility in nickel and copper remain critical restraints. Strategic opportunities lie in high-strength 7000 series aluminum applications within aerospace.
Emerging Trends and Growth Patterns in the Industry
The shift toward automation and IoT-enabled laser cutting is redefining shop floor productivity. Industry leaders are integrating AI-driven nesting software to minimize scrap rates in stainless steel and alloy steel processing, directly enhancing operational margins amid tightening supply chain tolerances.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted global supply chains, halting operations at major ports and causing acute shortages in cold-rolled steel coils. Recovery has been spearheaded by digital supply chain diversification, with fabricators adopting dual-sourcing strategies for aluminum and titanium to insulate against future logistical bottlenecks.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderate to high, dominated by integrated giants like ArcelorMittal S.A., Nippon Steel Corporation, and POSCO Holdings Inc. These entities leverage massive upstream smelting capabilities and proprietary alloy formulations to outcompete regional contract fabricators in high-margin automotive contracts.
Executive Summary of the Sheet Metal Market
Proprietary research confirms the Sheet Metal Market is on a robust trajectory, projected to reach $617.99 Billion by 2033 at a CAGR of 6.73% from 2027. Growth is anchored by surging infrastructure investments and lightweight material adoption across industrial machinery and consumer goods.
Market Forecast Analysis from 2027 to 2033
Expanding at a steady 6.73% CAGR, the market will scale from its 2026 baseline to $617.99 Billion by 2033. This expansion is heavily underpinned by rising consumption of advanced high-strength steels (AHSS) and aerospace-grade titanium alloys in emerging economies.
Segmentation Analysis by Material, Process, and End User
Our segmentation framework breaks down the market by material (Steel, Aluminum, Titanium, Other Materials), process (Rolling, Forging, Bending), and end user (Automotive, Defense, Aerospace, Industrial Tool And Machinery, Buildings And Construction, Home Appliances, Consumer Goods). Steel maintains dominant volume share, while aluminum leads in growth velocity.
Regional Market Analysis and Geographic Distribution
Geographically, Asia-Pacific dominates consumption due to massive manufacturing hubs in China, Japan, and South Korea, supported by localized steel mills like Baosteel. North America and Europe follow closely, driven by stringent safety mandates in aerospace and stringent environmental building codes.
In-Depth Regional Review of Key Markets
North American growth is anchored by robust defense spending and automotive re-tooling for EV platforms, benefiting domestic players like United States Steel Corporation and Nucor Corporation. Meanwhile, European markets focus intensely on green steel initiatives and circular economy mandates.
Company Profiles and Strategic Positioning
Industry leaders occupy distinct competitive niches. Alcoa Corporation and Constellium SE focus heavily on high-performance automotive and aerospace aluminum sheet solutions, whereas Tata Steel Limited and JFE Holdings Inc. leverage integrated steel production to capture high-volume construction and appliance contracts.
Porter's Five Forces Analysis of the Sector
The threat of new entrants remains low due to immense capital expenditure requirements for blast furnaces and rolling mills. However, supplier power is moderate to high, dictated by raw iron ore and bauxite pricing fluctuations controlled by multinational mining conglomerates.
SWOT Analysis of the Sheet Metal Industry
Key strengths include deep technological integration and versatile material offerings. Weaknesses involve high energy dependency. Opportunities abound in renewable energy infrastructure components, while threats stem from geopolitical trade tariffs impacting imported nickel, brass, and specialized stainless steel grades.
Value Chain Analysis from Raw Materials to End-Users
The value flow originates with raw material extraction (iron ore, bauxite, titanium sponge), moves through primary smelting and rolling mills operated by firms like Hindalco Industries Limited and Kaiser Aluminum Corporation, and culminates in precision stamping and fabrication by Tier-1 automotive and aerospace suppliers.
Investment Insights and High-Potential Areas
Investors should target technological innovators offering automated bending, laser welding, and AI-driven quality inspection. Companies specializing in sustainable, low-carbon steel and closed-loop aluminum recycling present the highest risk-adjusted return profile over the forecast horizon.
Conclusion and Key Takeaways
The Sheet Metal Market offers compelling growth, backed by a clear trajectory toward $617.99 Billion by 2033. Success in this sector requires continuous investment in advanced metallurgy, digital fabrication technologies, and resilient supply chain partnerships across both ferrous and non-ferrous material portfolios.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary executive interviews with C-suite stakeholders at firms like Maysteel Industries LLC and Aalco Metals Ltd., and secondary macroeconomic indicators from industrial production indices and World Steel Association reports.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for sheet metal across major industrial regions, analyzing ferrous and non-ferrous segments from 2026 through 2033. Excluded from this scope are custom artisanal metal smithing operations and unverified secondary scrap metal markets operating outside formal trade compliance.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features aggressive capacity expansions for green aluminum by players like Arconic Corporation and strategic joint ventures by Tata BlueScope Steel Pvt. Ltd. These moves reflect an industry-wide pivot toward sustainable manufacturing and localized supply chain resilience.