Market overview and structural significance of the Actuarial Consulting Service Market
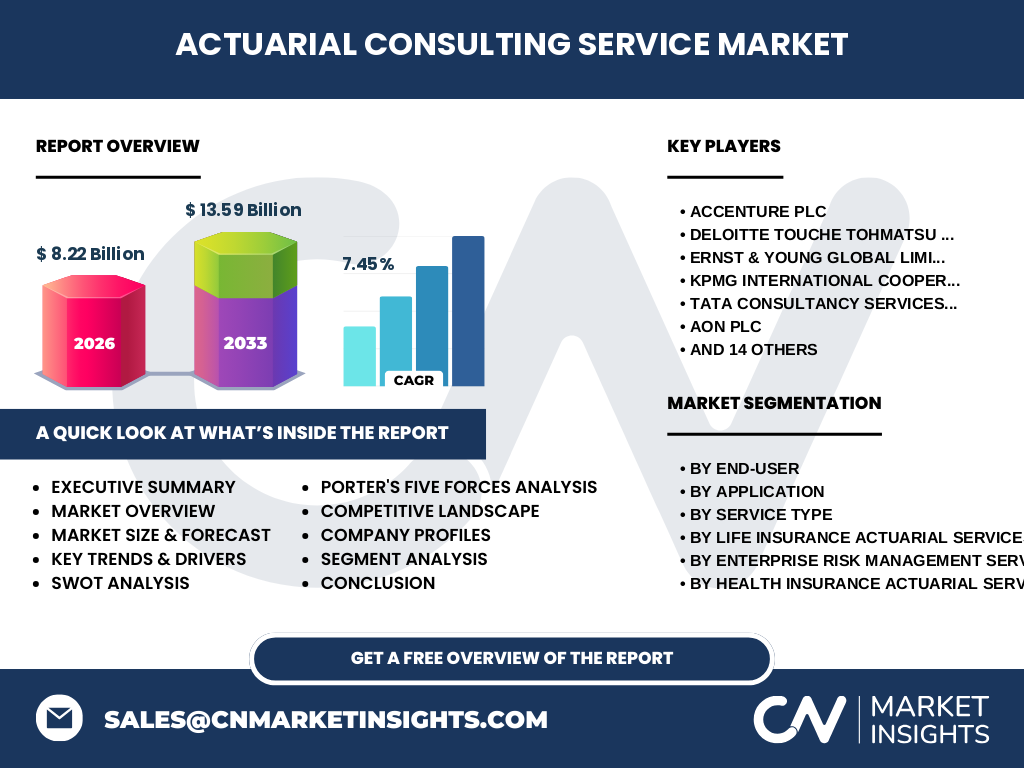
Our analysis indicates that the Actuarial Consulting Service Market is valued at 8.22 Billion in 2026. This sector provides essential financial risk assessment, liability valuation, and regulatory compliance advisory to institutions navigating complex statutory frameworks enforced by bodies like the NAIC and EIOPA.
Structural Growth Drivers and Market Restraints
The market is propelled by tightening solvency regulations such as Solvency II and IFRS 17, which demand sophisticated capital modeling and Risk Quantification. Conversely, acute talent shortages of credentialed actuaries and high implementation costs for predictive analytics platforms act as primary operational restraints.
Emerging Industry Trends in the Actuarial Consulting Service Market
Firms are rapidly integrating machine learning into Catastrophe Modelling and mortality analysis. This shift toward advanced data science allows major players like Milliman Inc. and Willis Towers Watson to deliver real-time risk evaluation that traditional stochastic models miss.
Post-Pandemic Recovery Trajectory and COVID-19 Impact
The pandemic exposed severe vulnerabilities in longevity and health assumptions, triggering a surge in demand for dynamic Medical Cost Trend Analysis. Post-COVID recovery has accelerated digital transformation, forcing insurers to modernize legacy pension valuation systems to handle unprecedented macroeconomic volatility.
Competitive Benchmarking and Industry Concentration
The landscape features a blend of Big Four accounting firms like Deloitte and EY alongside specialized consultancies such as Actuarial Resources Corporation. Market concentration is moderate to high, with industry leaders leveraging global footprints to service multinational insurance underwriters and pension funds.
Executive Summary of the Actuarial Consulting Service Market Analysis
Driven by compounding regulatory pressures and rising claims complexities, the Actuarial Consulting Service Market is positioned for robust expansion, scaling from 8.22 Billion in 2026 to 13.59 Billion by 2033, achieving a steady CAGR of 7.45%.
Long-Term Market Forecast and Revenue Projections (2027-2033)
Based on our research, the market will expand from its 2026 baseline of 8.22 Billion to reach 13.59 Billion by 2033. This expansion is sustained by a robust 7.45% CAGR, fueled by escalating demand for enterprise risk management and automated financial reporting solutions.
Segmentation Analysis Across End-Users, Applications, and Service Types
The market segments by end-user into Insurance Companies, Pension Funds, Government Organizations, and Corporations. Offerings span Life Insurance Actuarial Services, Enterprise Risk Management Services, and Health Insurance, addressing critical needs from Policy Valuation to Funding And Valuation.
Geographic Distribution and Regional Market Performance
North America dominates revenue generation due to stringent SEC and NAIC mandates, while Europe follows closely driven by stringent Solvency II requirements. Asia-Pacific represents the fastest-growing regional market, catalyzed by expanding insurance penetration and emerging regulatory frameworks in developing economies.
In-Depth Regional Review of Regulatory and Economic Pressures
In North America, demand focuses heavily on Pension Plan Design and Loss Reserving. Meanwhile, European markets prioritize comprehensive Regulatory Reporting and capital modeling, creating localized opportunities for specialized consultants like Oliver Wyman Group and Cheiron Inc.
Strategic Positioning of Leading Companies
Industry giants like Accenture Plc and KPMG International combine technology consulting with deep actuarial expertise, whereas boutique firms like Lewis & Ellis Inc. and Conrad Siegel focus on personalized pension and health consulting for regional corporations.
Porter's Five Forces Assessment of Competitive Intensity
Bargaining power of buyers is moderate due to the specialized nature of statutory actuarial opinions. Threat of substitutes remains low, as automated software cannot entirely replace certified actuarial judgment required for Claims Cost Analysis and complex reserve sign-offs.
SWOT Analysis of the Actuarial Consulting Service Market
Key strengths lie in high domain expertise and sticky client relationships. Weaknesses involve high project costs. Opportunities emerge in climate risk quantification, while threats stem from potential liability risks associated with flawed catastrophe and mortality forecasting models.
Value Chain Analysis from Data Inputs to End-User Delivery
The value chain begins with raw demographic and financial data ingestion, moves through stochastic modeling and regulatory compliance checks, and culminates in strategic advisory reports delivered to Chief Risk Officers and corporate boardrooms.
Investment Insights and High-Potential Opportunity Areas
Investors should target consultancies offering proprietary predictive software for Catastrophe Modelling and Enterprise Risk Management. These high-margin service lines align directly with corporate needs to optimize capital reserves under modern economic pressures.
Conclusion and Strategic Takeaways for Industry Stakeholders
With the market projected to hit 13.59 Billion by 2033 at a 7.45% CAGR, stakeholders must invest in advanced data analytics and talent retention to capture high-value opportunities in regulatory compliance and risk mitigation.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining statutory trade registry filings, primary executive interviews with chief actuaries, and secondary macroeconomic indicators from global insurance federations to ensure uncompromised accuracy.
Scope of the Report and Coverage Parameters
This report covers global trends within the Actuarial Consulting Service Market from 2026 to 2033, analyzing specific service types, applications, and end-user verticals while explicitly excluding informal internal corporate actuarial valuations.
Recent Developments, Partnerships, and Strategic Corporate Moves
Recent industry momentum highlights strategic acquisitions of boutique health analytics firms by global entities like Aon Plc and Marsh McLennan (Willis Towers Watson), alongside new product launches aimed at automating complex IFRS 17 compliance workflows.