What is the scope and industry significance of the Family/Indoor Entertainment Centers Market?
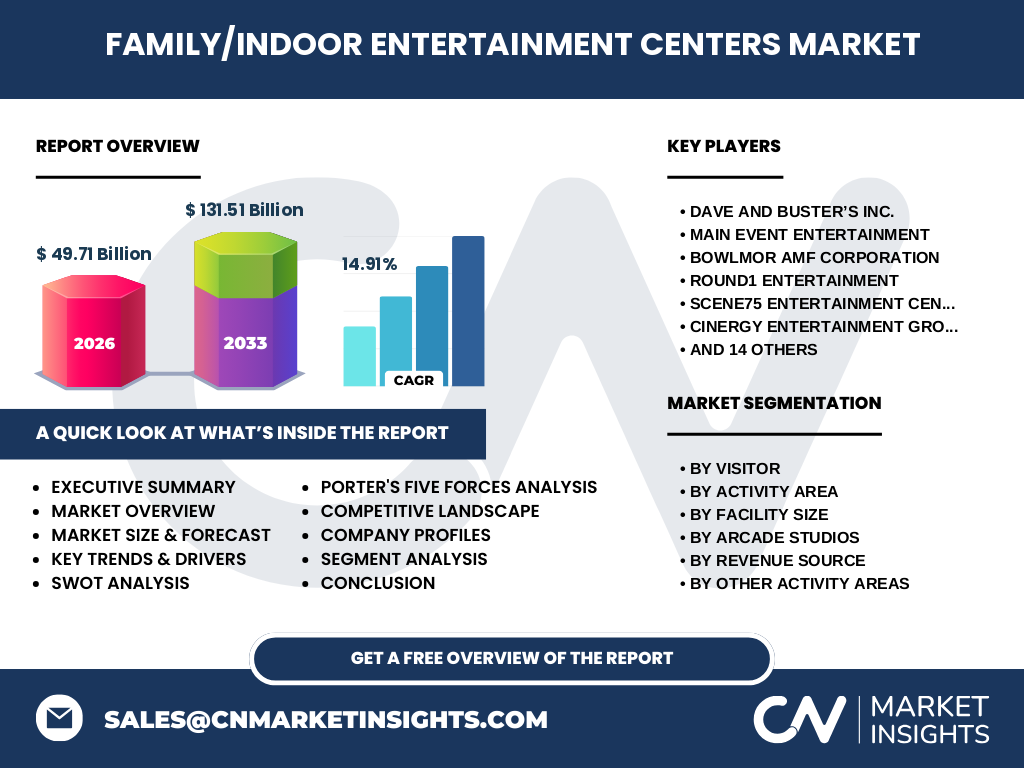
Our analysis indicates that the Family/Indoor Entertainment Centers Market represents a critical intersection of hospitality, digital gaming, and physical recreation. Reaching a market size of $49.71 Billion in 2026, the sector serves as a premier destination for experiential consumer spending. Industry significance is anchored in its ability to integrate high-margin food and beverage operations with immersive attractions, driving robust commercial real estate partnerships globally.
Key market drivers, restraints, challenges, and opportunities shaping the Family/Indoor Entertainment Centers Market
The market thrives on surging consumer preference for experiential spending over traditional retail, acting as a primary growth driver. However, high initial capital expenditure for advanced AR and VR gaming zones poses a notable restraint. Operators face persistent labor shortages and stringent municipal zoning constraints as operational challenges. Meanwhile, expanding into underserved suburban commercial hubs offers lucrative opportunities for branded operators.
The Shift Toward Immersive Tech: Emerging trends and growth patterns in the Family/Indoor Entertainment Centers Market
Industry trends highlight an accelerated migration toward multi-sensory attraction formats. Augmented Reality Games and location-based virtual reality experiences are redefining consumer expectations within arcade studios and dedicated gaming zones. Furthermore, operators are leveraging robust CRM platforms to track visitor telemetry, driving hyper-personalized marketing that significantly enhances customer retention and repeat visitation rates across core demographics.
How did the COVID-19 pandemic impact the Family/Indoor Entertainment Centers Market and drive its recovery trajectory?
The pandemic introduced severe liquidity crises and prolonged mandated closures, profoundly depressing visitation metrics. Recovery has been spearheaded by well-capitalized chains implementing contactless ticketing, upgraded HVAC air filtration systems, and diversified outdoor-indoor hybrid models. Consequently, consumer confidence rebounded rapidly, accelerating pent-up demand and positioning the industry for unprecedented post-pandemic expansion toward long-term valuation targets.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
Market concentration features a mix of dominant national franchises and agile independent operators. Industry leaders like Dave And Buster's Inc. and Round1 Entertainment utilize scale to secure prime real estate and negotiate favorable gaming licensing terms. Strategic dynamics increasingly revolve around cross-sector acquisitions, proprietary redemption game development, and the integration of high-end dining concepts to maximize per-capita visitor spend.
Executive summary of key findings regarding the Family/Indoor Entertainment Centers Market
Our comprehensive research projects the Family/Indoor Entertainment Centers Market to surge to $131.51 Billion by 2033, expanding at a remarkable CAGR of 14.91% from 2027. Growth is underpinned by relentless technological innovation in AR/VR and a structural shift toward experience-based consumer economies. Investors should target scalable footprints combining physical play with competitive socialising concepts.
Market forecast trajectory from 2027 to 2033
The forecast period signals extraordinary momentum, with the market scaling from its baseline to reach $131.51 Billion by 2033 at a CAGR of 14.91%. This trajectory is propelled by rising disposable incomes in emerging economies and continuous capital deployment toward advanced interactive attractions. Facilities offering diverse revenue streams, such as corporate event hosting and integrated merchandising, will capture disproportionate market share.
Segmentation analysis of visitor demographics, activity areas, and facility sizes
Segmentation spans multiple dimensions: By Visitor (Families with Children 0-8, 9-12, Teenagers 13-19, Young Adults 20-25, and Adults 25+); By Activity Area (Arcade Studios, AR and VR Gaming Zones, Physical Play Activities, Skill or Competition Games); and By Facility Size (ranging from up to 5,000 sq ft to expansive 20,001 to 40,000 sq ft destinations). Each segment addresses distinct consumer leisure preferences.
Geographic distribution and performance across regional sectors
Regional performance varies based on urban density, real estate availability, and discretionary spending power. North America maintains a dominant revenue share due to high consumer spending on leisure and established franchise networks. Meanwhile, Asia-Pacific exhibits the fastest adoption rate, driven by rapid urbanization, expanding middle-class demographics, and the proliferation of mega-mall developments incorporating high-tech entertainment complexes.
In-depth regional review of key growth markets
North American markets benefit from mature entertainment ecosystems featuring established giants like Sky Zone and Main Event Entertainment, where large-format facilities thrive in suburban retail corridors. Conversely, the Asia-Pacific review reveals explosive growth in densely populated urban centers, heavily influenced by location-based entertainment concepts popularized by innovators like KidZania and TimeZone Global.
Strategic positioning of leading companies in the Family/Indoor Entertainment Centers Market
Industry leaders maintain distinct competitive moats through specialized positioning. Dave And Buster’s Inc. combines high-end dining with mature arcade studios, whereas Urban Air Adventure Park and Sky Zone focus heavily on high-throughput physical play activities like trampoline parks. Meanwhile, Andretti Indoor Karting And Games targets thrill-seekers with premium high-speed karting coupled with advanced racing simulators.
Porter's Five Forces analysis of competitive pressures
The threat of new entrants remains moderate due to steep initial capital requirements for high-end simulation hardware and prime real estate leases. Bargaining power of buyers is high given abundant leisure alternatives, prompting operators to utilize sophisticated loyalty apps. Supplier power is concentrated among major arcade game manufacturers, while substitution threat is mitigated by ongoing technological integration.
SWOT analysis highlighting internal and external market dynamics
Strengths include robust customer retention loops and diversified revenue streams across food, beverage, and ticketing. Weaknesses involve vulnerability to economic downturns and high maintenance costs for kinetic play structures. Opportunities lie in expanding immersive AR/VR gaming zones and corporate team-building events. Threats encompass rising commercial real estate lease rates and stringent regional health compliance regulations.
Value chain analysis from raw materials to end-user experiences
The value chain originates with raw material suppliers providing structural steel, electronics, and specialized polymers for play equipment. Component manufacturers and software developers then build proprietary arcade hardware and VR software. System integrators, facility designers, and real estate developers construct the venues, culminating in operators delivering immersive leisure experiences directly to end-consumers.
Investment insights and high-potential areas within the sector
Strategic investment should prioritize mid-to-large format facilities ranging from 10,001 to 40,000 sq ft that incorporate high-margin AR And VR Gaming Zones alongside food and beverage operations. Investors must evaluate operators leveraging robust data analytics for dynamic pricing and inventory management, ensuring optimal return on capital expenditure during the 2027 to 2033 forecast window.
Conclusion and key takeaways for industry stakeholders
The Family/Indoor Entertainment Centers Market offers compelling growth, moving toward $131.51 Billion by 2033 at a 14.91% CAGR. Success hinges on transitioning from traditional static attractions to dynamic, technology-infused experiential environments. Stakeholders must prioritize technological agility, strategic real estate selection, and diversified monetization channels to capture expanding consumer wallet share.
Research methodology for baseline estimations and market triangulations
Our baseline estimates are triangulated through a rigorous methodology combining exhaustive trade registry data, primary stakeholder interviews with C-suite executives across leading chains, and secondary macroeconomic indicators. We cross-reference proprietary foot-traffic analytics, municipal licensing filings, and corporate financial disclosures to ensure high-fidelity market sizing and accurate growth projections.
Scope of the report, coverage parameters, and analytical limitations
This report encompasses comprehensive global coverage of the Family/Indoor Entertainment Centers Market market size, segmented by visitor demographics, activity areas, facility size, and revenue sources. Limitations include potential variance in localized municipal permitting timelines and unquantified impacts of sudden macroeconomic policy shifts on discretionary consumer spending patterns across developing regions.
Recent developments, strategic partnerships, and product launches
Recent industry momentum is characterized by aggressive expansion and strategic franchising deals. Major market participants are actively deploying next-generation immersive software updates, partnering with Hollywood studios for branded intellectual property attractions, and introducing cashless RFID payment ecosystems to streamline in-venue spending and elevate overall operational efficiency.