What is the scope and definition of the Metallurgical Coal Market industry?
Our research establishes that the Metallurgical Coal Market encompasses the vital global trade of coking coal utilized primarily as a reducing agent and heat source in blast furnace steelmaking. Industrial significance is underscored by its irreplaceable chemical role in reducing iron ore to pig iron, driving heavy manufacturing supply chains worldwide.
Key market drivers, restraints, challenges, and opportunities shaping Metallurgical Coal Market
The market is propelled by expanding urban infrastructure in developing economies, though constrained by stringent decarbonization mandates and strict environmental regulations from bodies like the EPA and EU directives. Primary opportunities lie in technological integration like pulverized coal injection efficiency, balancing input costs against surging global steel demands.
Emerging trends and growth patterns in Metallurgical Coal Market
Industry trends highlight an accelerated pivot toward Premium HCC grades to optimize blast furnace productivity and minimize carbon output per ton of steel. Producers are increasingly adopting automated longwall mining technologies to mitigate rising extraction expenditures and manage complex geologic constraints in deep underground operations.
How did the COVID-19 pandemic affect the Metallurgical Coal Market and its recovery trajectory?
Pandemic-induced lockdowns severely disrupted maritime logistics and port throughput, causing temporary demand contraction across major steel hubs. Recovery materialized rapidly as fiscal stimulus packages revived construction, though labor shortages and supply chain bottlenecks tested the resilience of major export terminals in Australia and North America.
Competitive landscape — major players, market concentration, and strategic dynamics
The competitive arena features concentrated leadership by mining giants such as BHP Group plc, Glencore Plc, and Anglo American Plc, alongside specialized operators like Warrior Met Coal Inc. Strategic dynamics focus on securing tier-one metallurgical assets, optimizing rail-to-port logistics corridors, and navigating shifting trade tariffs across Asia-Pacific.
Executive summary of the Metallurgical Coal Market research report
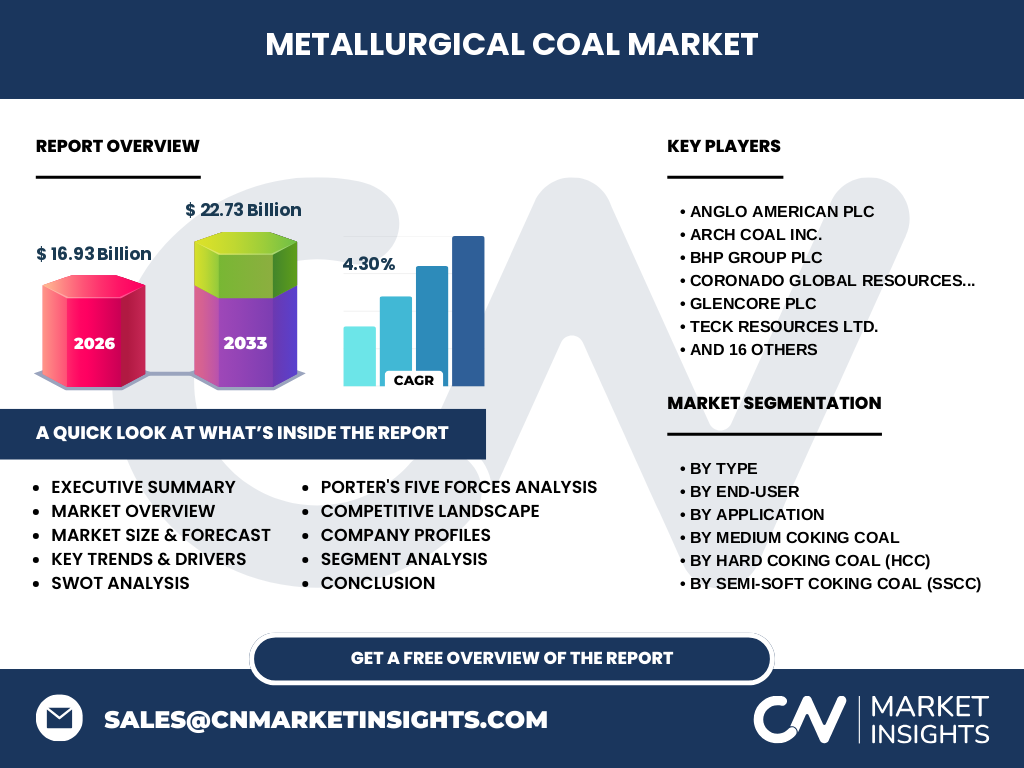
Our comprehensive analysis values the Metallurgical Coal Market size at $16.93 billion in 2026, expanding to $22.73 billion by 2033 at a steady CAGR of 4.30%. This trajectory reflects resilient blast furnace dependency in emerging economies despite mounting global carbon neutrality pressures.
Market forecast and projected growth trajectory from 2027 to 2033
Projections indicate steady expansion, scaling the market from its 2026 baseline to reach $22.73 billion by 2033, underpinned by a 4.30% CAGR. Growth catalysts remain anchored in long-term supply agreements between Australian and North American extractors and steel mills in India and Southeast Asia.
Segmentation analysis of the Metallurgical Coal Market industry
Segmentation is categorized by type, end-user, and application. Type includes Hard Coking Coal, Medium Coking Coal, Semi-Soft Coking Coal, and Pulverized Coking Injection Coal. End-users span Iron And Steel, Chemical And Pharmaceutical, and Paper And Pulp, while applications focus predominantly on Steelmaking versus Non-Steelmaking.
Regional market analysis and geographic performance distribution
Geographic performance is heavily skewed toward Asia-Pacific, driven by massive steel production capacity in China and India. North America and Europe maintain steady baseline demand, though regional consumption faces structural headwinds from scrap-based electric arc furnace conversions and stringent decarbonization policies.
In-depth regional review of high-growth territories
India emerges as the primary demand engine, offsetting slowing growth in mature industrial economies through aggressive domestic blast furnace capacity expansions. Meanwhile, Australian export terminals manage regional supply flows, navigating seasonal weather disruptions like cyclones that periodically impact Queensland rail networks.
Company profiles and strategic positioning of leading market participants
Leading entities leverage distinct geographic and portfolio advantages. Teck Resources Ltd. and Arch Coal Inc. focus on high-volatility and premium hard coking coal exports, whereas state-backed enterprises like China Shenhua Energy Co. Ltd. and Coal India Ltd. prioritize domestic energy security and localized industrial supply.
Porter's Five Forces analysis of the Metallurgical Coal Market
Competitive rivalry is moderate to high among established export titans, while the threat of substitutes remains constrained by the lack of viable commercial alternatives to coking coal in primary blast furnaces. Supplier power fluctuates based on specialized grade availability, particularly for low-volatile PCI and premium HCC.
SWOT analysis of the Metallurgical Coal Market sector
Strengths include high energy density and essential chemical properties for steel reduction. Weaknesses involve high capital expenditure and carbon-intensive extraction. Opportunities stem from industrialization in South Asia, while threats encompass regulatory carbon penalties and alternative green hydrogen steelmaking advancements.
Value chain analysis from raw materials to end-users
The value chain initiates with geological exploration and underground or surface extraction, followed by wet washery processing to reduce ash content. Processed coal moves via dedicated heavy-haul rail networks to major export ports, ultimately reaching blast furnace operators for coking and iron reduction.
Investment insights and strategic recommendations for stakeholders
Investors should target tier-one assets producing Low-Volatile Coking Coal, as these grades are essential for blending optimization. Strategic focus must be placed on operations with certified low carbon intensity profiles and diversified logistics networks insulated from regional weather vulnerabilities.
Conclusion and key takeaways for industry participants
The Metallurgical Coal Market industry trends confirm that while green steel initiatives are advancing, blast furnace dependency ensures stable medium-term growth. Capitalizing on the forecasted 4.30% CAGR requires disciplined cost control, technological efficiency, and proactive navigation of evolving global trade and environmental standards.
Research methodology and data triangulation framework
Our analytical baseline combines exhaustive primary stakeholder interviews with coking plant operators, trade registry customs data, and secondary macroeconomic indicators. Triangulation models cross-reference historical export volumes from major ports with regional pig iron production statistics to ensure absolute forecast accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics from 2026 through 2033, evaluating quantitative financial metrics alongside qualitative structural shifts. Limitations include unforeseen geopolitical trade embargoes or sudden regulatory policy overhauls that could alter baseline macroeconomic forecasts.
Recent developments, strategic partnerships, and corporate announcements
Recent industry activity centers on asset portfolio optimization, with major players divesting thermal assets to concentrate capital on metallurgical coal reserves. Strategic joint ventures focus on upgrading port loading infrastructure and deploying autonomous fleet management systems to enhance operational margins.