Market overview and structural significance of the Frac Sand And Proppant Market
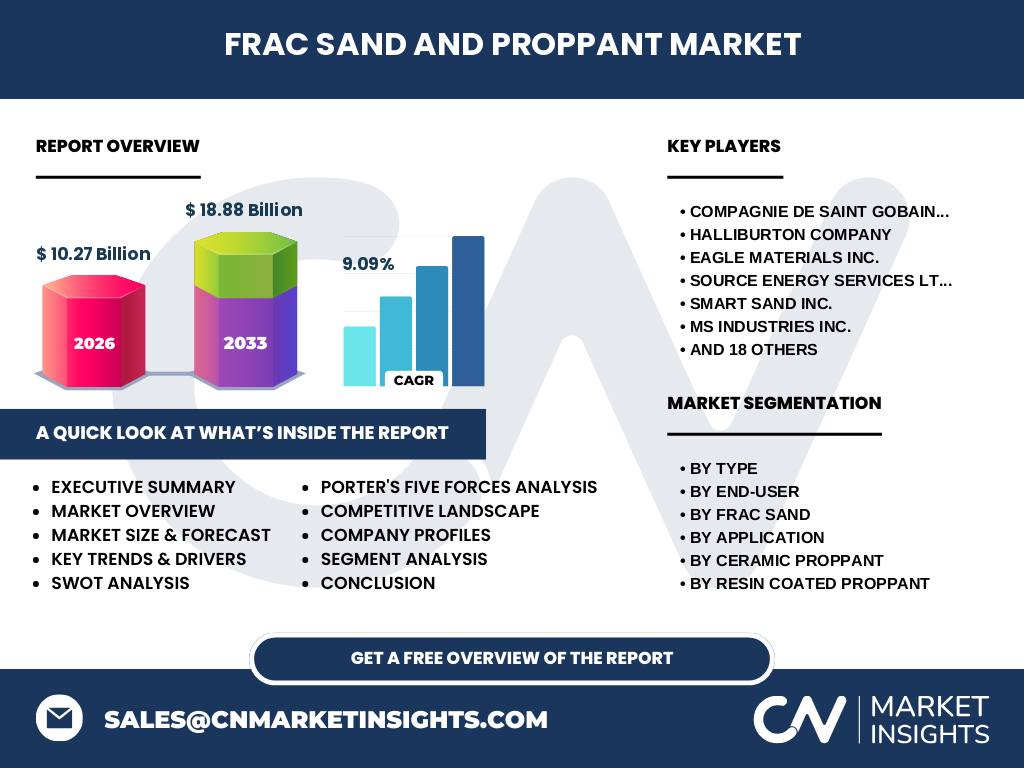
The Frac Sand And Proppant Market is valued at 10.27 Billion in 2026, serving as the foundational raw material sector for unconventional oil and gas extraction. Our analysis indicates that high-purity silica sand, resin-coated variants, and engineered ceramics are essential for propping open subterranean fissures created during hydraulic fracturing operations managed by key players like U.S. Silica Holdings Inc. and Halliburton Company.
Key market drivers, restraints, challenges, and opportunities shaping Frac Sand And Proppant Market
Growth is propelled by rising lateral well lengths and escalating proppant loading intensities per wellbore. However, the Frac Sand And Proppant Market faces logistical headwinds, including Class I rail freight bottlenecks and tightening OSHA silica dust exposure limits. Significant opportunities lie in regional mine expansions by Atlas Sand Company LLC and Covia Holdings Corporation to reduce costly last-mile trucking distances.
Emerging trends and growth patterns in Frac Sand And Proppant Market
A definitive shift toward in-basin sand sourcing is redefining supply chains across major North American plays. Industry trends highlight increased adoption of Northern White Sand alongside local brown variants to optimize logistics spend. Companies like Smart Sand Inc. are capitalizing on automated terminal storage to streamline delivery schedules for hydraulic fracturing service providers operating in remote tight gas formations.
COVID-19 impact analysis and recovery trajectory for Frac Sand And Proppant Market
The pandemic triggered an unprecedented contraction in upstream capital expenditures, halting active rig counts and depressing spot pricing for proppant supplies. The subsequent recovery trajectory has been shaped by disciplined capital allocation among operators, prioritizing cash flow generation over aggressive production growth, which allowed established manufacturers like CARBO Ceramics Inc. to realign structural production capacities.
Competitive landscape, major players, market concentration, and strategic dynamics
The competitive landscape features moderate consolidation, with major enterprises like Covia Holdings Corporation, U.S. Silica Holdings Inc., and Hi Crush Inc. dominating volume output. Strategic dynamics center on vertical integration, where players acquire dedicated transload facilities and last-mile logistics fleets to secure long-term supply agreements with tier-one exploration and production corporations.
Executive summary of the Frac Sand And Proppant Market report
Our comprehensive evaluation confirms that the Frac Sand And Proppant Market is positioned for robust expansion, scaling from a baseline valuation of 10.27 Billion in 2026 to reach 18.88 Billion by 2033. This trajectory represents a steady CAGR of 9.09%, driven by technological advancements in well completion designs and sustained global demand for hydrocarbon energy resources.
Market forecast and revenue projections from 2027 to 2033
Driven by compounding activity in unconventional shale plays, the market is projected to expand significantly over the forecast window. Based on our research, the Frac Sand And Proppant Market will achieve a valuation of 18.88 Billion by 2033, expanding at a notable 9.09% CAGR from its 2026 baseline of 10.27 Billion, propelled by rising proppant intensity per well.
Segmentation analysis across types, end-users, and applications
Market segmentation categorizes the industry by type (Frac Sand, Resin Coated Proppant, Ceramic Proppant), end-user (Oil And Gas, Hydraulic Fracturing Service Providers), and application (Shale Gas, Tight Gas, Coalbed Methane). Specialized sub-segments include Northern White Sand and pre-cured resin-coated options, which cater to high-pressure, deep-well environments requiring exceptional crush resistance and minimal embedment losses during production cycles.
Regional market analysis and geographic distribution performance
Geographic performance is heavily anchored by North American sedimentary basins, where prolific unconventional shale formations dictate high volumetric consumption. Regional analysis reveals that proximity to active plays in the Permian Basin and the Marcellus Shale dictates supply chain efficiency, favoring localized producers such as Sierra Frac Sand LLC and Alpine Silica LLC over distant competitors relying on expensive inter-state rail transit.
In-depth regional review of key operational hubs and constraints
The Permian Basin remains the primary demand center, absorbing massive tonnages of both local brown sand and Northern White varieties. Regional reviews highlight localized logistical constraints, including municipal road wear regulations and driver shortages, which compel regional suppliers like Eagle Materials Inc. and Source Energy Services Ltd. to invest heavily in automated transloading hubs and dedicated last-mile storage silos.
Company profiles and strategic positioning of leading industry participants
Key market participants deploy distinct strategies to maintain competitive moats. U.S. Silica Holdings Inc. and Covia Holdings Corporation leverage extensive reserve footprints and multi-basin terminal networks. Meanwhile, specialized innovators like Select Sands Corp. and Fairmount Santrol LLC focus on high-purity silica grades and sustainable ESG mining practices to attract environmentally conscious exploration and production clientele.
Porter's Five Forces analysis of the Frac Sand And Proppant Market
Porter's framework reveals moderate-to-high buyer power due to fragmented supply options, balanced by high switching costs associated with rigorous well-testing protocols. Supplier power remains moderate, constrained by abundant regional sand reserves. Threat of substitution is low for standard depths but rises for ceramic proppants in ultra-deep, high-pressure reservoirs where crush resistance is paramount for long-term well productivity and sustained hydrocarbon flow rates.
SWOT analysis highlighting internal capabilities and external pressures
Strengths include vast high-purity silica reserves and established logistics networks. Weaknesses involve high sensitivity to upstream oil and gas commodity price volatility. Opportunities emerge from proppant optimization in extended-reach lateral wells. Threats encompass stringent environmental regulations regarding particulate emissions and the ongoing commercial development of alternative well stimulation fluids that could potentially reduce overall proppant dependency over time.
Value chain analysis from raw mining to end-user deployment
The value chain initiates with geological exploration and dry-mining or dredging of raw silica deposits. Processing involves multi-stage crushing, wet and dry screening, and classification for sphericity and turbidity standards. The chain extends through resin-coating applications by firms like Badger Mining Corporation, bulk rail transport via companies like Hi Crush Inc., and terminal offloading directly into client blending units at the wellsite.
Investment insights, strategic recommendations, and high-potential areas
Investors should target regional mines offering low extraction costs and short transit radii to major shale plays. Strategic focus on ESG-compliant mining operations and advanced resin-coated proppant technologies will yield superior returns. Our analysis indicates that companies investing in automated last-mile logistics assets will outperform peers by mitigating supply chain friction and capturing higher operating margins.
Conclusion and core takeaways for market stakeholders
The Frac Sand And Proppant Market represents a critical, growth-oriented sector underpinned by a solid 9.09% CAGR toward the 18.88 Billion valuation target by 2033. Stakeholders must prioritize operational efficiency, logistical integration, and environmental compliance to successfully navigate evolving industry demands and secure durable competitive advantages across major unconventional basins.
Research methodology for data triangulation and market estimation
Baseline market estimates are constructed through rigorous data triangulation, combining official trade registry records, regulatory filings from publicly traded proppant suppliers, and extensive primary interviews with hydraulic fracturing engineers and logistics directors. Secondary macroeconomic indicators, rig count metrics, and proppant intensity ratios are synthesized to validate market sizing and revenue growth projections through 2033.
Scope of the report, coverage parameters, and analytical limitations
This report encompasses global and regional evaluations of the Frac Sand And Proppant Market, detailing product types, applications, and end-user segments from 2026 to 2033. Limitations include inherent volatility in upstream exploration and production spending, sudden geopolitical shifts affecting global energy demand, and localized regulatory changes regarding water usage and particulate matter emissions during mining and processing operations.
Recent developments, corporate announcements, and strategic industry moves
Recent strategic moves across the sector feature facility expansions, M&A activity, and technological rollouts focused on reducing carbon footprints. Major producers have forged long-term supply pacts with hydraulic fracturing service providers to guarantee volume off-take. Concurrently, innovators like ChangQing Proppant Corporation and Epic Ceramic Proppants Inc. have launched high-strength ceramic grades designed to enhance conductivity in challenging deepwater and ultra-deep onshore reservoirs.