What is the market overview and industry significance of the Oil And Gas Upstream Activities Market?
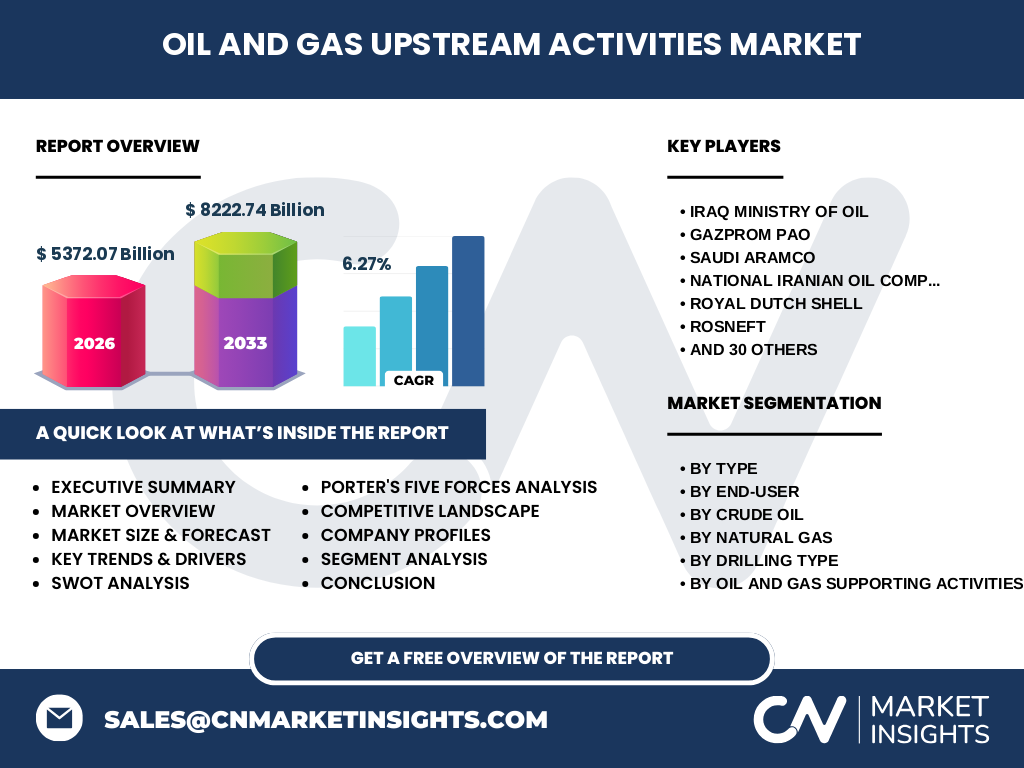
The Oil And Gas Upstream Activities Market represents the foundational tier of energy exploration and extraction. Valued at $5,372.07 Billion in 2026, this sector encompasses critical operations managed by heavyweights like Saudi Aramco and Gazprom PAO. It drives global energy security through capital-intensive onshore and offshore drilling, seismic acquisition, and reservoir evaluation.
What are the structural growth drivers, restraints, challenges, and opportunities shaping the Oil And Gas Upstream Activities Market?
Our analysis indicates that rising global primary energy consumption acts as a primary catalyst, while stringent environmental regulations by bodies like the EPA pose notable operational restraints. Volatile crude pricing creates acute logistical hurdles, yet substantial opportunities emerge in digital reservoir modeling deployed by innovators such as Schlumberger Ltd. and Halliburton Company.
Emerging trends and growth patterns in the Oil And Gas Upstream Activities Market
The sector is witnessing an accelerated shift toward automation and real-time downhole telemetry. Industry leaders including Baker Hughes Company and Weatherford International plc are pioneering automated rig operations that significantly reduce non-productive time, optimizing extraction efficiency across both mature basins and frontier offshore blocks.
How did the COVID-19 pandemic impact the Oil And Gas Upstream Activities Market and what does the recovery trajectory look like?
Pandemic-induced demand destruction triggered unprecedented capital expenditure cuts across upstream portfolios. However, aggressive post-pandemic fiscal recovery and rebounding mobility have propelled the market toward a robust valuation of $8,222.74 Billion by 2033, heavily supported by state-backed operators like the Iraq Ministry of Oil.
Competitive benchmarking and strategic dynamics in the Oil And Gas Upstream Activities Market
Market concentration remains high among national oil companies and tier-one oilfield service providers. Strategic maneuvers focus on deepwater asset optimization and technological integration, where specialized firms like Transocean Ltd. and TechnipFMC plc maintain distinct competitive advantages through proprietary subsea architecture.
Executive summary of key findings for the Oil And Gas Upstream Activities Market
Driven by a robust CAGR of 6.27% from 2027 to 2033, the Oil And Gas Upstream Activities Market is transitioning from pure volume extraction to efficiency-driven production. Capital deployment increasingly favors advanced directional drilling and enhanced oil recovery techniques executed by established players such as Chevron and Rosneft.
What is the market forecast for the Oil And Gas Upstream Activities Market from 2027 to 2033?
Based on our comprehensive econometric modeling, the market is projected to surge from its 2026 baseline to reach $8,222.74 Billion by 2033. This trajectory reflects sustained global reliance on hydrocarbon feedstocks alongside expanding liquefied natural gas processing infrastructure managed by entities like Equinor.
Segmentation analysis of the Oil And Gas Upstream Activities Market
The sector bifurcates by type into Crude Oil, Natural Gas, Oil And Gas Wells Drilling Services, and Oil And Gas Supporting Activities. End-user demand is dominated by crude petroleum companies and natural gas extraction enterprises, with specialized services like Seismic Data Collection driving precision exploration.
Geographic distribution and regional performance in the Oil And Gas Upstream Activities Market
Regional performance is heavily anchored by prolific reserves in the Middle East and North America. The Middle East commands substantial share via state entities like the National Iranian Oil Company, while North American markets thrive on advanced onshore horizontal drilling technologies driven by independent operators.
In-depth regional review of key operational hubs
Middle Eastern jurisdictions continue to lead in low-cost production capacity expansion. Concurrently, North American basins exhibit high responsiveness to rig count fluctuations, supported by specialized equipment suppliers and hydraulic fracturing specialists such as Helmerich & Payne Inc. and ProPetro Holding Corp.
Company profiles and strategic positioning of leading market participants
Industry leaders balance capital discipline with targeted technological investments. Giants like Royal Dutch Shell and Gazprom Neft focus on high-margin offshore assets, while service providers such as National Oilwell Varco Inc. and Baker Hughes Company supply critical drilling hardware and digital monitoring solutions.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers remains moderate due to standardized global commodity pricing, while supplier power is high for specialized ultra-deepwater drillships owned by firms like Noble Corporation plc and Seadrill Limited. Threat of substitution is cushioned by persistent baseline global energy demands.
SWOT analysis of the Oil And Gas Upstream Activities Market
Strengths lie in established subterranean asset knowledge and massive infrastructure networks. Weaknesses involve high exposure to geopolitical instability. Opportunities abound in digital oilfield investments, while threats stem from accelerating energy transition policies and regulatory carbon constraints.
Value chain analysis from raw materials to end-users
The value chain initiates with geological surveys and seismic acquisition, progressing through exploratory drilling, well completion, and commercial hydrocarbon production. Logistics providers like Tidewater Inc. and Bristow Group Inc. ensure seamless offshore supply chain continuity from shorebases to rig floors.
Investment insights and high-potential areas within the sector
High-potential capital allocation targets automated drilling systems and predictive maintenance software. Investors should prioritize asset-light digital service providers and low-breakeven offshore developments championed by firms like Aker Solutions ASA and Oceaneering International Inc.
Conclusion and key takeaways for strategic decision-makers
The Oil And Gas Upstream Activities Market offers compelling growth toward $8,222.74 Billion by 2033. Success requires disciplined capital allocation, rigorous compliance with regional environmental frameworks, and early adoption of AI-driven drilling automation provided by market leaders.
Research methodology used to triangulate baseline estimates
Our analysis triangulates data from national trade registries, regulatory filings with bodies like OPEC, and primary executive interviews across upstream operators. Secondary macroeconomic indicators are cross-referenced with rig count data from service contractors to ensure high-fidelity market sizing.
Scope of the report, coverage parameters, and analytical limitations
This report covers global upstream activities from 2026 through 2033, analyzing crude oil, natural gas, drilling services, and supporting infrastructure. Limitations include potential unforeseen geopolitical shocks and sudden shifts in international trade sanctions affecting state-run oil companies.
Recent developments, corporate announcements, and strategic partnerships
Recent market dynamism is characterized by cross-border joint ventures, rig fleet modernizations, and digital oilfield software deployments. Major service providers such as Baker Hughes Company and Schlumberger Ltd. have recently unveiled carbon-reduced drilling initiatives tailored for strict regulatory jurisdictions.