What is the market overview and industry significance of the TV Advertising Market?
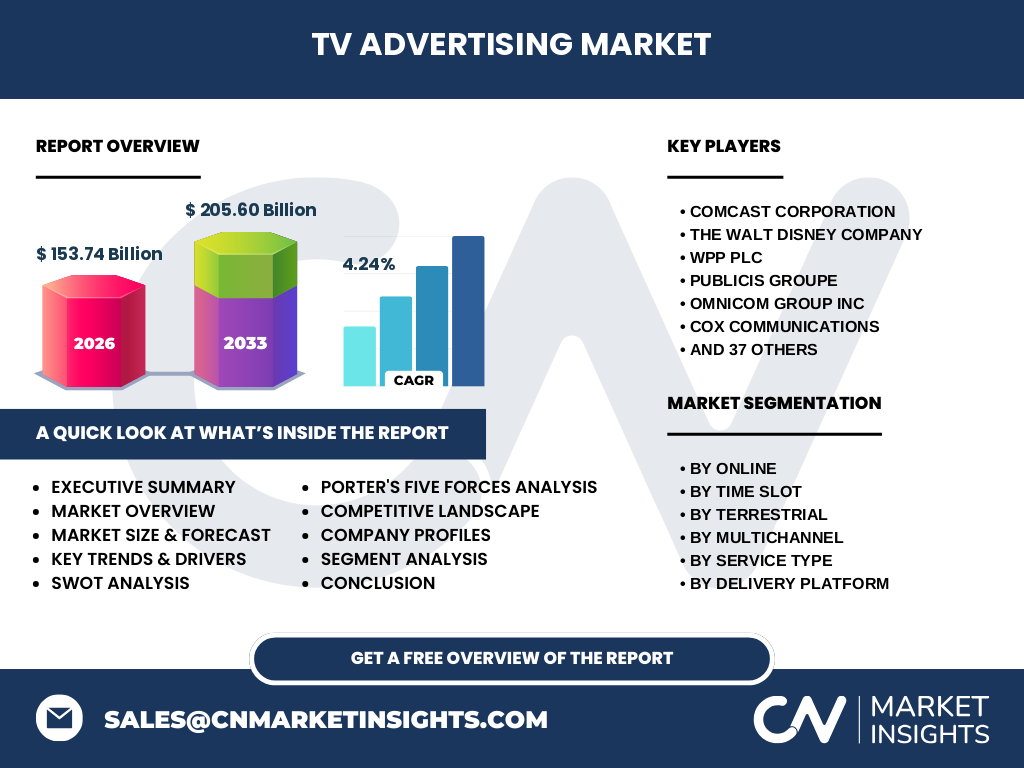
Our analysis indicates that the TV Advertising Market represents a critical commercial pillar, valued at $153.74 Billion in 2026. This sector bridges content creators and enterprise brands through linear and digital formats. Industry titans like Comcast Corporation and The Walt Disney Company dictate prime-time pricing architectures, navigating strict regulatory oversight from bodies like the Federal Communications Commission regarding spot lengths and political ad disclosures.
Structural Growth Drivers and Market Restraints
The data suggests that programmatic linear integration serves as a primary growth catalyst, alongside rising Connected TV adoption. Conversely, ad-blocking technology and stringent privacy mandates from the European Union act as notable restraints. Enterprises such as Publicis Groupe and Omnicom Group Inc must continuously adapt their media buying strategies to maintain ROI amidst these shifting regulatory and technological hurdles.
Emerging Trends and Growth Patterns in TV Advertising Market
The shift toward advanced audience targeting is reshaping the TV Advertising Market. Advertisers increasingly leverage deterministic data sets rather than broad demographic sweeps. Agencies like WPP plc and DENTSU INC. pioneer dynamic ad insertion technologies, enabling hyper-localized messaging across regional broadcast feeds while maximizing viewer engagement across multiple screen ecosystems.
How did COVID-19 impact the TV Advertising Market and shape recovery?
The pandemic initially caused severe supply chain disruptions for consumer goods manufacturers, prompting widespread ad spend freezes. However, our research confirms that the recovery trajectory accelerated digital transformation. Broadcasters and agencies pivoted rapidly toward streaming inventories, mitigating traditional linear broadcast losses and establishing resilient, hybrid monetization models that persist across the current economic cycle.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains moderately fragmented, featuring global agency holding companies alongside specialized creative powerhouses. Firms like Interpublic Group counterparts and independent innovators such as Droga5 LLC compete fiercely for multinational accounts. Competitive advantage hinges on proprietary data analytics platforms, exclusive premium inventory access, and seamless cross-platform attribution capabilities.
Executive Summary of TV Advertising Market Insights
A high-level synthesis reveals robust expansion, with the TV Advertising Market projected to reach $205.60 Billion by 2033 at a CAGR of 4.24%. Convergence between linear television and programmatic streaming defines this era. Industry leaders must prioritize flexible technological infrastructures and data-driven accountability to capture high-margin opportunities across fragmented consumer touchpoints.
Market Forecast Projections (2027 to 2033)
Our econometric modeling indicates steady valuation gains, moving from the 2026 baseline of $153.74 Billion to $205.60 Billion by 2033, expanding at a 4.24% CAGR. This trajectory is underpinned by accelerating cord-cutting behaviors and increased programmatic adoption in emerging regional economies, favoring agile networks and technology-first media agencies.
Segmentation Analysis of the TV Advertising Market
The market divides across several core vectors: By Online (Streaming Service Advertising, Video On Demand Advertising); By Time Slot (20 Seconds, 60 Seconds, More Than 60 Seconds); By Terrestrial (Analog, Digital Terrestrial); By Multichannel (Cable, Satellite); By Service Type; By Delivery Platform; and By Broadcasting Services (Advertisement, Subscription), each fulfilling distinct brand exposure objectives.
Geographic Distribution and Regional Performance
Regional performance varies significantly based on broadband infrastructure maturity and regulatory frameworks. North America commands the largest revenue share due to high upfront television scatter markets, whereas Asia-Pacific demonstrates the fastest growth rate, fueled by rapid smartphone penetration and expanding digital terrestrial networks managed by regional telecom regulators.
In-Depth Regional Review of Key Markets
North American expenditures remain heavily concentrated around upfront seasons managed by networks like Sinclair Broadcast Group and Gray Television Inc. Meanwhile, European markets operate under strict European Union Audiovisual Media Services Directive caps on commercial breaks, forcing agencies like Havas Worldwide India Private Limited and Vivendi SA to innovate with native product placement.
Strategic Positioning of Leading Companies
Key market participants deploy distinct positioning strategies to defend their turf. The Walt Disney Company leverages its unmatched content library and direct-to-consumer streaming apps, while holding groups like Publicis Groupe and Omnicom Group Inc utilize massive global media-buying scale to negotiate preferential ad rates with major network operators.
Porter's Five Forces Analysis of Industry Attractiveness
Bargaining power of buyers is moderately high due to consolidated agency holding groups commanding massive ad budgets. Threat of substitutes remains elevated via social media video platforms. Rivalry among existing competitors is fierce, driven by technological parity and the constant battle for exclusive live sports and premium entertainment broadcasting rights.
SWOT Analysis: Strengths, Weaknesses, Opportunities, Threats
Strengths include unmatched mass-reach capabilities and high brand trust. Weaknesses involve complex attribution measurement and ad-skipping behaviors. Opportunities lie in addressable TV and programmatic linear expansion. Threats encompass stringent data privacy regulations and shifting consumer consumption habits away from scheduled linear programming toward ad-free subscription tiers.
Value Chain Analysis from Content Creators to End-Users
The value chain flows from raw creative development by agencies like Ogilvy & Mather Worldwide Inc. and McCann Worldgroup, through production and network scheduling by entities like British Broadcasting Corporation and Sun TV Network, down to distribution via cable and satellite platforms, culminating in targeted delivery to end-user households.
Investment Insights and High-Potential Areas
Strategic recommendations highlight Connected TV measurement platforms and dynamic ad insertion software as prime investment targets. Venture capital and private equity firms should focus on ad-tech innovators capable of solving cross-device attribution challenges, as brand advertisers increasingly demand verifiable return on ad spend across fragmented broadcast channels.
Conclusion and Strategic Takeaways
In summary, the TV Advertising Market is undergoing a structural renaissance, balancing traditional reach with digital precision. Reaching $205.60 Billion by 2033, the sector rewards organizations that seamlessly integrate linear broadcast assets with programmatic streaming capabilities while adhering strictly to evolving global compliance standards.
Research Methodology and Data Triangulation
Baseline estimates are meticulously triangulated by combining official trade registry data, primary qualitative interviews with C-suite executives across top agencies, and secondary macroeconomic indicators. This multi-layered approach ensures robust validation of market size figures, growth rates, and segment valuations across all covered geographic regions.
Scope of the Report and Coverage Parameters
This comprehensive research report covers global market dynamics from 2027 to 2033, utilizing 2026 as the foundational base year valued at $153.74 Billion. Parameters encompass terrestrial, multichannel, and online delivery mechanisms, excluding unverified black-market ad networks and subterranean localized closed-circuit television systems.
Recent Developments, Partnerships, and Strategic Moves
Recent industry activity features major strategic alliances between traditional broadcasters and ad-tech platforms. Notable agency moves, such as digital transformation initiatives by Goodby Silverstein & Partners and Crispin Porter + Bogusky, demonstrate an industry-wide commitment to enhancing programmatic capabilities and automated workflow efficiencies across global television ad inventories.