What is the baseline market overview for the Wet Flue Gas Desulfurization System Market?
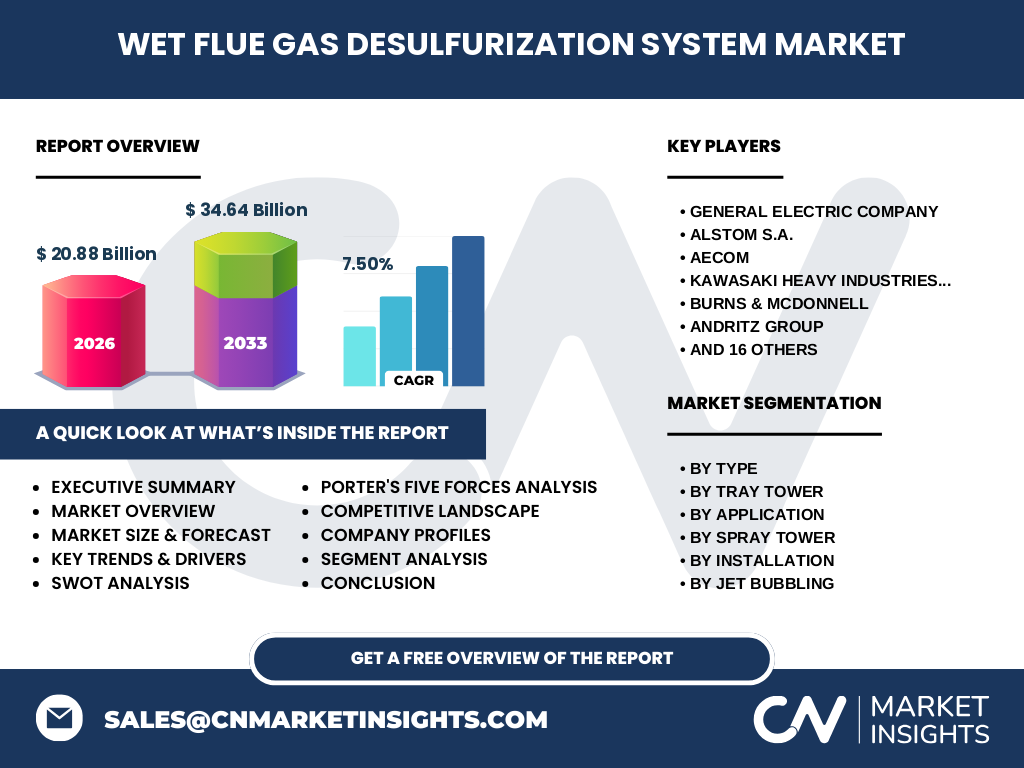
The Wet Flue Gas Desulfurization System Market size is valued at $20.88 Billion in 2026, underpinning global industrial compliance for sulfur dioxide emission control. Our analysis indicates these capital-intensive scrubbing installations remain critical for heavy manufacturing assets utilizing high-sulfur raw materials.
Key market drivers, restraints, challenges, and opportunities shaping Wet Flue Gas Desulfurization System Market
Strict environmental mandates from bodies like the EPA drive adoption, while high capital expenditures for limestone slurry infrastructure act as primary restraints. Opportunities emerge in upgrading legacy facilities with advanced corrosion-resistant metallurgy and wastewater minimization units.
Emerging trends and growth patterns in Wet Flue Gas Desulfurization System Market
The shift toward zero-liquid discharge (ZLD) configurations dominates current Wet Flue Gas Desulfurization System Market industry trends. Operators increasingly demand automated reagent dosing loops to optimize limestone consumption and lower operational overhead.
COVID-19 impact analysis on the Wet Flue Gas Desulfurization System Market
Pandemic-induced supply chain disruptions delayed engineering, procurement, and construction schedules across coal-fired and petrochemical assets. However, our research reveals a robust post-pandemic recovery trajectory as deferred environmental retrofits resume under tightened local compliance timelines.
Competitive benchmarking and strategic dynamics in the sector
Market concentration remains moderate, with technology leaders like General Electric Company, Mitsubishi Hitachi Power Systems Ltd, and Babcock & Wilcox Enterprises Inc. dictating engineering standards through proprietary absorber designs and global patent portfolios.
Executive summary of key findings for the Wet Flue Gas Desulfurization System Market
The Wet Flue Gas Desulfurization System Market industry trends point toward a solid expansion phase driven by stringent air quality regulations. Strategic positioning among EPC contractors will dictate success as operators prioritize turnkey modular solutions.
What is the long-term market forecast for the sector from 2027 to 2033?
Our projection shows the market expanding to $34.64 Billion by 2033, growing at a steady CAGR of 7.50%. This trajectory is supported by mandatory sulfur abatement decrees across developing industrial economies and aging power infrastructure.
Segmentation analysis of the Wet Flue Gas Desulfurization System Market
The sector is categorized by Type (Spray Tower, Jet Bubbling, Tray Tower), Tray Tower type (Counter-Flow, Co-Current), Application (Power Plants, Chemical, Cement, Metal Processing, Manufacturing), Spray Tower type (Single-Stage, Multi-Stage), Installation (Greenfield, Brownfield), and Jet Bubbling (Venturi, Non-Venturi), defining specialized roles across heavy industry.
Geographic distribution and regional performance in the global landscape
Geographic performance is heavily weighted toward Asia-Pacific due to extensive coal-fired capacity in rapidly developing industrial corridors. North America and Europe maintain stable demand driven by retrofitting aging assets to meet secondary air quality standards.
In-depth regional review of key operational territories
Localized constraints in heavily industrialized zones of China and India necessitate high-capacity multi-stage spray towers. Meanwhile, European markets focus on efficiency upgrades, favoring advanced tray tower configurations for tighter sulfur capture.
Company profiles and strategic positioning of leading industry players
Key innovators like Andritz Group, Valmet Corporation, and Chiyoda Corporation leverage specialized liquid-gas contacting patents. Meanwhile, regional specialists such as KC Cottrell and Thermax Ltd. capture localized market share through agile, cost-competitive engineering delivery.
Porter's Five Forces analysis of the competitive ecosystem
Supplier power remains moderate due to specialized alloy requirements for scrubber vessels, while buyer power is high given the multi-million-dollar scale of utility tenders. Threat of substitutes is mitigated by the unmatched chemical efficiency of wet scrubbing.
SWOT analysis of Wet Flue Gas Desulfurization System Market operations
Strengths lie in proven high-efficiency SO2 removal rates exceeding 95%. Weaknesses involve high parasitic power losses. Opportunities exist in circular economy gypsum monetization, while strict carbon-neutrality initiatives pose a long-term threat to fossil-fuel applications.
Value chain analysis from raw materials to end-user deployment
The value chain originates with raw material suppliers providing high-grade limestone, caustic soda, and corrosion-resistant alloys like nickel-based superalloys. It flows through specialized engineering firms like Burns & McDonnell and AECOM before reaching power and chemical plant operators.
Investment insights and high-potential areas for capital allocation
Investors should target technology providers offering modular brownfield retrofit solutions that minimize plant downtime. Capital is increasingly attracted to firms integrating artificial intelligence for real-time reagent optimization and predictive slurry pump maintenance.
Conclusion and key takeaways for stakeholders
The Wet Flue Gas Desulfurization System Market analysis confirms that regulatory compliance remains the ultimate catalyst for sustained capital expenditure. Vendors mastering wastewater reduction and energy-efficient absorption towers will capture outsized profit margins.
Research methodology used for market sizing and validation
Baseline estimates are triangulated by combining proprietary customs trade registries, primary stakeholder interviews with C-level engineering executives, and secondary macroeconomic indicators regarding global industrial capacity expansion and energy consumption patterns.
Scope of the report, coverage parameters, and analytical limitations
This report covers global deployment metrics across designated industrial verticals from 2026 through 2033. Limitations include potential variances in regional policy enforcement schedules and unpredictable fluctuations in raw commodity pricing for limestone and specialty steels.
Recent developments, strategic partnerships, and technological advancements
Recent market activities feature major EPC joint ventures focused on integrating carbon capture readiness into existing wet scrubber installations. Firms like Ducon Technologies Inc. and Marsulex Environmental Technologies have recently secured high-profile municipal and utility contracts for advanced particulate-scrubbing upgrades.