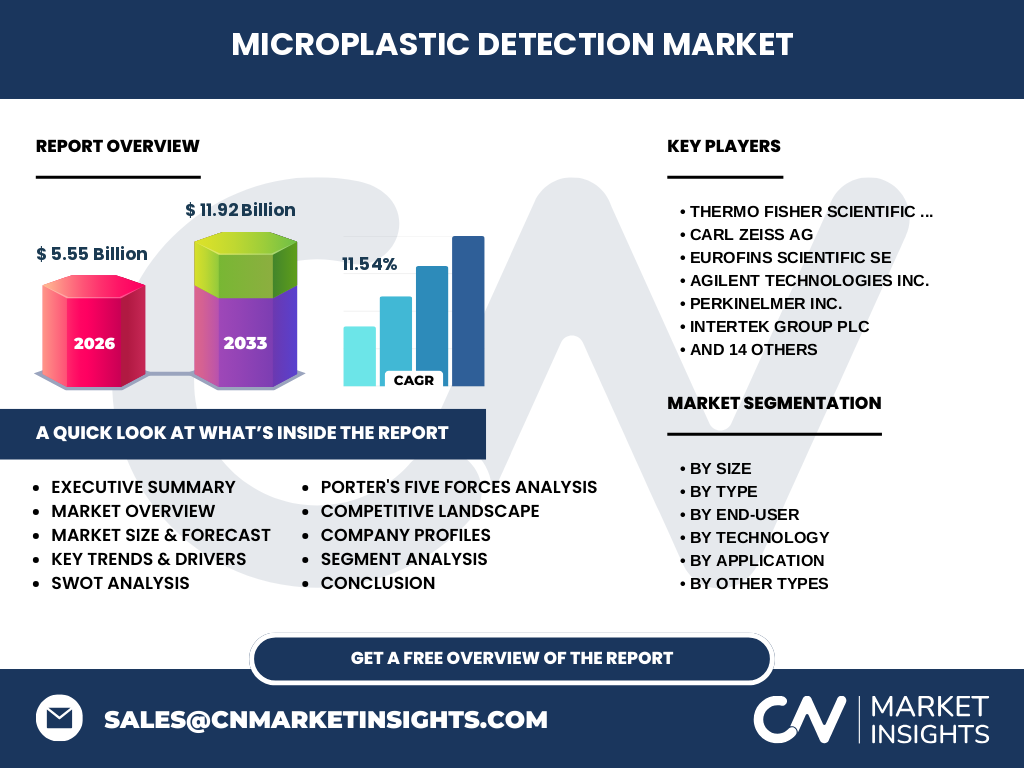
Market overview of the Microplastic Detection Market
Our analysis indicates the Microplastic Detection Market represents a critical frontier in environmental safety, valued at $5.55 Billion in 2026. This sector encompasses advanced analytical instruments designed to identify synthetic polymer particles across aquatic, atmospheric, and terrestrial samples, safeguarding global ecosystems.
What are the core market drivers, restraints, challenges, and opportunities?
Strict mandates by bodies like the EPA and EU drive expansion, yet high equipment acquisition costs act as a primary restraint. The persistent challenge of matrix interference during sample preparation opens lucrative opportunities for automated micro-Raman and FTIR instrumentation developers.
Emerging trends and growth patterns in the industry
The shift toward automated particle characterization is transforming laboratories. Industry trends highlight increased adoption of hyperspectral imaging coupled with machine learning algorithms, enabling rapid identification of polymers like polyethylene and polystyrene without manual intervention.
How did COVID-19 impact the sector and shape its recovery?
Pandemic-induced supply chain disruptions temporarily stalled component procurement for high-end spectrometers. However, the subsequent post-recovery surge in wastewater surveillance initiatives accelerated demand, anchoring a robust 11.54% CAGR trajectory moving toward the 2027 forecast.
Competitive benchmarking and strategic market concentration
The market features moderate concentration dominated by analytical instrument heavyweights. Firms like Thermo Fisher Scientific Inc. and Agilent Technologies Inc. leverage proprietary spectroscopy suites to capture high-value government contracts, while niche innovators focus on portable detection.
Executive Summary of industry findings
Our comprehensive findings project the market to surge from its 2026 baseline to $11.92 Billion by 2033. Driven by rising regulatory pressures in food safety and environmental monitoring, technological convergence remains the primary catalyst for enterprise valuation.
Microplastic Detection Market forecast from 2027 to 2033
The forecast period signals extraordinary expansion, scaling the market from $5.55 Billion in 2026 to $11.92 Billion by 2033 at an impressive 11.54% CAGR. Accelerated municipal investments in advanced water treatment facilities underpin this sustained valuation growth.
Segmentation analysis by size, type, end-user, technology, and application
Segmentation spans particle sizes (<1 mm, 1-3 mm, 3-5 mm), polymer types (polyethylene, polystyrene, polypropylene), and advanced technologies including Fourier Transform Infrared (FTIR) Spectroscopy and Micro-Raman Spectroscopy across research laboratories and government bodies.
Geographic distribution and regional market performance
Regional performance varies significantly, with North America leading adoption due to stringent environmental protection policies. Meanwhile, the Asia-Pacific territory exhibits the fastest uptake, propelled by rapid industrialization and escalating municipal water testing mandates.
In-depth regional review of high-growth territories
Urban centers across Western Europe and North America show heavy utilization of Scanning Electron Microscopy (SEM) for microplastic pollution mapping. Conversely, emerging markets in Asia are prioritizing lower-cost flow cytometry solutions for routine environmental monitoring.
Company profiles and strategic positioning of leading innovators
Industry stalwarts such as Bruker Corporation, Shimadzu Corporation, and PerkinElmer Inc. dominate through robust R&D spending. Specialized entrants like Ocean Diagnostics Inc. and Wasser 3.0 gemeinnützige GmbH carve out unique positions via targeted environmental sampling tools.
Porter's Five Forces analysis of competitive intensity
Rivalry is intense among established instrument manufacturers, while the threat of new entrants remains moderate due to steep intellectual property barriers. Buyer power is tempered by the specialized nature of high-end spectroscopic hardware required for accurate polymer identification.
SWOT analysis of the Microplastic Detection ecosystem
Strengths lie in high-precision analytical capabilities; weaknesses involve complex sample preparation protocols. Opportunities abound in food and beverage testing applications, whereas threats stem from inconsistent global regulatory standards regarding allowable microplastic thresholds.
Value chain analysis from raw materials to end-users
The value chain flows from optical component manufacturers and software developers to analytical instrument assemblers like Carl Zeiss AG and Horiba Ltd., ultimately serving research laboratories and water treatment plants requiring rigorous quality assurance.
Strategic investment insights and high-potential areas
Investors should target firms developing field-portable Micro-Raman systems and AI-driven automated particle sizing software. These technologies resolve critical bottlenecks in rapid environmental screening, offering superior margin potential.
Conclusion and key takeaways for stakeholders
The market trajectory highlights an indispensable shift toward automated, high-throughput detection systems. Stakeholders must align R&D with multi-polymer identification capabilities—specifically targeting polyethylene and polypropylene derivatives—to capture emerging municipal and industrial contracts.
Research methodology behind our data triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-level executives, secondary macroeconomic indicators from global environmental agencies, and proprietary trade registry data tracking analytical instrument shipments worldwide.
Scope of the report and coverage parameters
This report covers global microplastic detection technologies, applications, and end-user segments from 2026 through 2033. Excluded from this scope are macro-plastic sorting facilities and generalized solid waste recycling infrastructure metrics.
Recent developments in partnerships, product launches, and strategic moves
Recent market dynamics feature strategic acquisitions and collaborative R&D agreements among market leaders. For instance, firms like Eurofins Scientific SE and Intertek Group plc continue expanding their accredited testing laboratories to accommodate rising commercial demand.