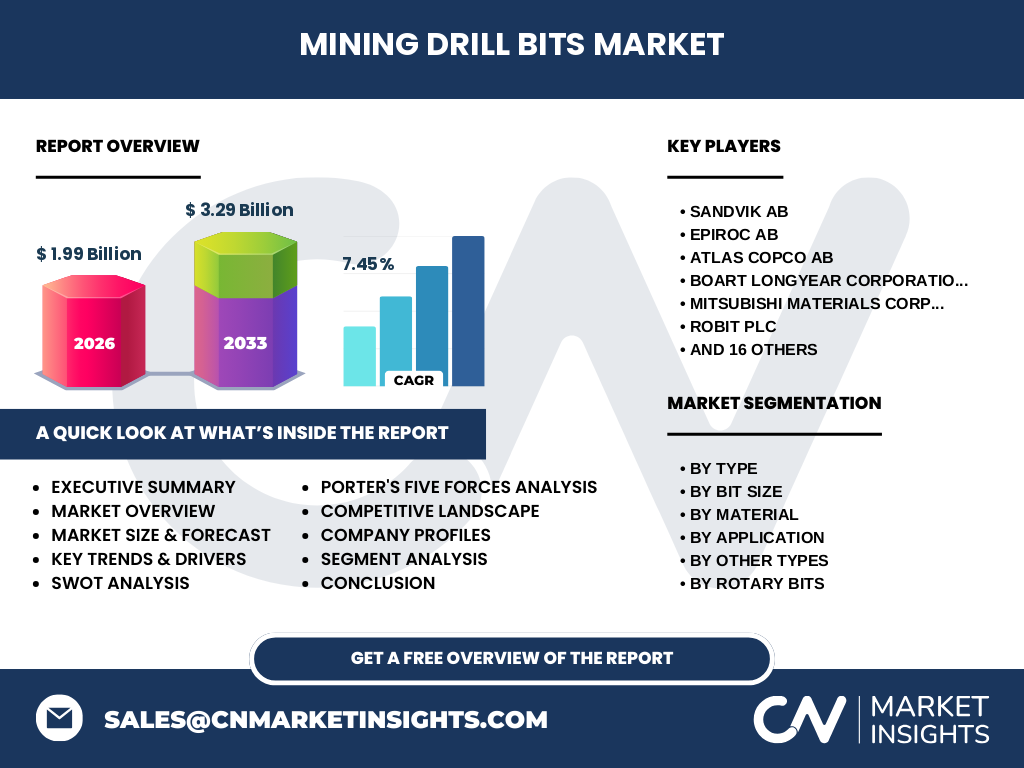
Market overview of the Mining Drill Bits Market
Our analysis indicates that the Mining Drill Bits Market is valued at 1.99 Billion in 2026. This sector encompasses critical consumable tooling used across surface and underground extraction operations, relying heavily on advanced metallurgy like tungsten carbide and PDC diamond to withstand abrasive geological formations encountered by industry leaders such as Sandvik AB and Epiroc AB.
Key market drivers, restraints, challenges, and opportunities shaping the Mining Drill Bits Market
The Mining Drill Bits Market industry trends reveal surging demand for high-performance PDC (Polycrystalline Diamond Compact) Bits driven by deep-earth mineral exploration. However, volatile raw material costs for tungsten carbide act as a key restraint, challenging supply chain margins for manufacturers like Boart Longyear Corporation while opening lucrative recycling opportunities.
Emerging trends and growth patterns in the Mining Drill Bits Market
The shift toward automated, heavy-duty rotary drilling has accelerated adoption rates for Tricone Bits and specialized DTH Hammer bits with Dome Face. Based on our research, operators increasingly demand real-time telemetry integration, favoring tech-forward suppliers who optimize bit life under severe thermal and mechanical stress.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions severely throttled logistical routes through major global ports, creating acute delivery bottlenecks for heavy-duty Roller Cone Bits. Mining Drill Bits Market analysis shows that aggressive modernization investments by firms like Mitsubishi Materials Corporation catalyzed a rapid post-pandemic volume recovery.
Competitive benchmarking and strategic dynamics in the Mining Drill Bits Market
Market concentration remains moderately fragmented, featuring tier-one giants like Atlas Copco AB alongside agile specialists such as Robit plc and Mincon Group plc. Competitive positioning hinges on proprietary diamond bonding technologies and localized service footprints designed to reduce downtime for high-capital surface mining projects.
Executive summary of the Mining Drill Bits Market
Our proprietary research projects the Mining Drill Bits Market to expand from 1.99 Billion in 2026 to 3.29 Billion by 2033, registering a robust 7.45% CAGR. Growth is decisively anchored by escalating global demand for critical energy transition minerals and technological shifts toward advanced metallurgy.
Market forecast trajectory from 2027 to 2033
Driven by aggressive iron ore and copper extraction initiatives, the data suggests the Mining Drill Bits Market market size will scale rapidly over the forecast horizon. Achieving a 7.45% CAGR to hit 3.29 Billion by 2033 reflects sustained capital expenditure in both surface and underground mining assets.
Segmentation analysis across product types and applications
Categorized by type (Rotary Bits, DTH Hammer bits), size (ranging from Below 5” to Above 14”), material (PDC Diamond, Tungsten Carbide, Steel), and application (Surface vs Underground), the taxonomy highlights diverse end-user needs. Button Bits and Core Bits dominate niche geological sampling operations globally.
Regional market analysis and geographic performance
Geographic performance varies significantly, with the Asia-Pacific region leading consumption due to extensive coal and iron ore mining operations. Meanwhile, North America and Latin America demonstrate high concentration demand for high-end PDC Diamond bits deployed in deep hard-rock subterranean extraction.
In-depth regional review of high-growth mining jurisdictions
Strict environmental compliance by regulatory bodies like the EPA and MSHA in North America drives strict operational safety standards, favoring premium durability products from Varel International Energy Services Inc. and Rockmore International Inc. Conversely, cost-sensitive markets in emerging economies prioritize volume-heavy Drag Bits and traditional steel variations.
Company profiles and strategic positioning of leading participants
Industry leaders like Sandvik AB and Epiroc AB maintain dominant market share via expansive global distribution and R&D focused on wear-resistant alloys. Meanwhile, specialized innovators such as Ulterra Drilling Technologies LLC leverage proprietary cutter geometries to capture high-margin underground drilling contracts.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate to high given numerous tier-two alternatives, whereas supplier power over raw tungsten and cobalt remains a persistent squeeze. Threat of substitutes stays low due to the irreplaceable mechanical nature of heavy-duty rock destruction in hard-rock subterranean environments.
SWOT analysis for the Mining Drill Bits Market ecosystem
Strengths lie in advanced proprietary metallurgy and high thermal-tolerance PDC cutters. Weaknesses involve high sensitivity to macroeconomic commodity cycles. Opportunities emerge from deep-sea and subterranean electrification minerals, while threats stem from geopolitical trade tariffs impacting raw material imports.
Value chain analysis from raw materials to end-users
The value chain initiates with raw powder metallurgy (tungsten carbide and cobalt), progressing through precision CNC machining and proprietary diamond sintering by fabricators like Numa S.A. and Master Drilling Group Limited, ultimately terminating at heavy equipment fleets operated by global mining houses.
Investment insights and high-potential growth areas
Strategic investors should prioritize firms specializing in automated, sensor-embedded DTH Bits with Flat Face and eco-friendly manufacturing processes. Capital allocation toward proprietary diamond synthesis yielding superior wear resistance offers the highest risk-adjusted yield through 2033.
Conclusion and key takeaways for stakeholders
Surpassing 3.29 Billion by 2033 at a 7.45% CAGR, the Mining Drill Bits Market represents a high-conviction growth sector. Success heavily depends on material science innovation, localized supply chain resilience, and alignment with automated underground extraction methodologies.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by cross-referencing primary stakeholder interviews with C-level executives, official trade registry statistics from mining equipment exporters, and secondary macroeconomic indicators tracking global mineral capex budgets through 2033.
Scope of the report and coverage parameters
This report covers global manufacturing, distribution, and end-user demand dynamics across surface and underground mining verticals from 2026 to 2033. Limitations exclude artisanal, small-scale unmechanized quarrying operations and non-industrial drilling applications.
Recent developments, partnerships, and strategic moves
Recent strategic moves feature major collaborative R&D pacts between tier-one toolmakers and digital automation providers to embed IoT sensors directly into Tricone Bits. These telemetry-enabled launches aim to preemptively mitigate catastrophic bit failure during high-cost remote extraction projects.