Market overview of the Mining Market
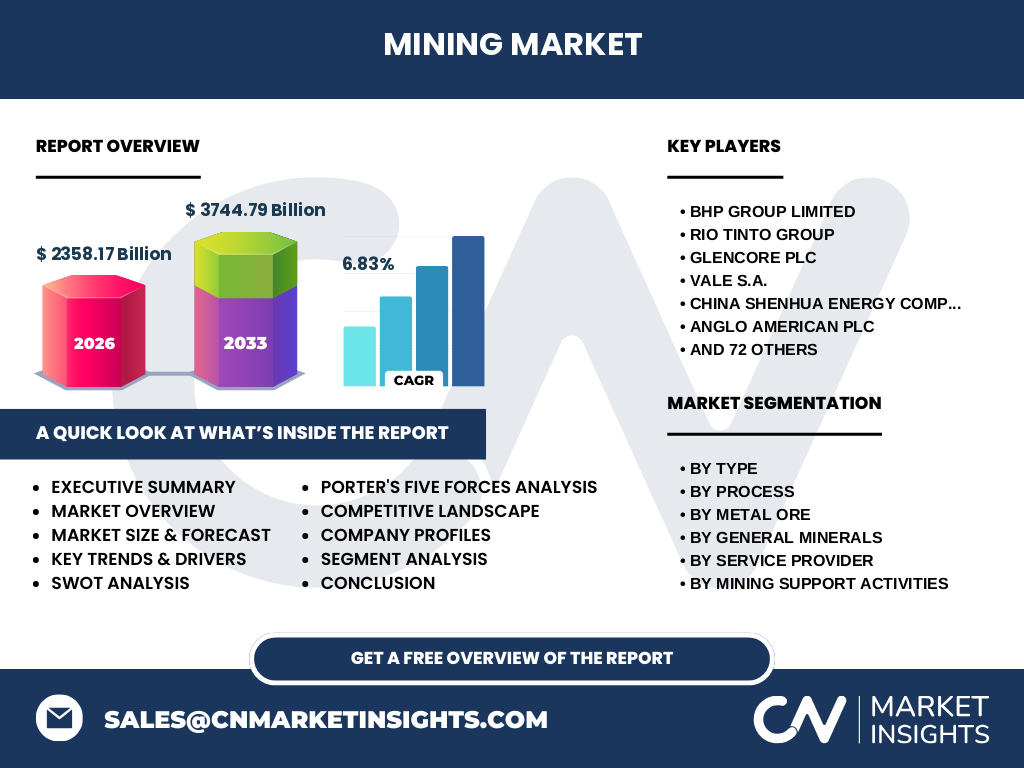
Our analysis indicates that the Mining Market stands at a valuation of 2358.17 Billion in 2026. This foundational sector encompasses the extraction of valuable minerals and geological materials, serving as the bedrock for global manufacturing, energy generation, and infrastructure development across raw material categories.
Key market drivers, restraints, challenges, and opportunities shaping the Mining Market
Growth is heavily propelled by escalating demand for transition metals like copper and nickel, balanced against stringent environmental compliance mandates and high capital expenditure hurdles. Opportunities heavily favor automated drilling services and advanced exploration technologies managed by major players like BHP Group and Rio Tinto.
Emerging trends and growth patterns in the Mining Market
The industry is witnessing an aggressive pivot toward autonomous hauling, decarbonized underground operations, and digitalized Mining Support Activities. Companies are increasingly integrating ESG metrics into asset management, directly shifting capital toward low-emission extraction of critical energy transition minerals.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain fractures and labor shortages temporarily stalled project pipelines, yet the recovery phase catalyzed robust digital investments. Post-pandemic resilience has been anchored by automated remote operations, allowing industry leaders to rebound swiftly and capture surging commodity demand.
Competitive benchmarking and strategic dynamics in the Mining Market
Market concentration remains moderately high, dominated by diversified extraction titans such as Glencore plc, Vale S.A., and Anglo American Plc. Strategic positioning increasingly revolves around securing high-grade deposits, vertical integration, and aggressive investments in sustainable metal ore extraction to outpace competitors.
Executive summary of key findings
Driven by a robust CAGR of 6.83%, the market is projected to reach 3744.79 Billion by 2033. Our research underscores that technological adoption in underground mining and surging consumption of copper, nickel, and lithium-adjacent minerals will dictate market leadership over the forecast window.
Market forecast from 2027 to 2033
The Mining Market is set for sustained expansion, accelerating from its 2026 baseline of 2358.17 Billion to hit 3744.79 Billion by 2033. This trajectory represents a steady compound annual growth rate (CAGR) of 6.83%, fueled by green energy transitions and infrastructure spending.
Segmentation analysis across operational categories
The market is structurally divided by type, process, metal ore, and general minerals. Key segments include Underground Mining and Surface Mining, alongside specialized divisions for Copper Mining Operations, Industrial Minerals, and comprehensive Mining Support Activities covering equipment rental and consulting.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with the Asia-Pacific region dominating consumption and extraction volume due to massive industrial hubs in China and India. Meanwhile, Latin America and Africa remain critical export powerhouses for high-grade iron ore, precious stones, and specialized metal ores.
In-depth regional review of key territories
North American and Australian jurisdictions emphasize mechanized efficiency, strict regulatory adherence, and advanced consulting and advisory services. Conversely, emerging regional markets focus on scaling production volumes in bituminous coal and bauxite to satisfy domestic industrial expansion.
Company profiles and strategic positioning
Industry heavyweights like Freeport-McMoRan, Newmont Mining, and Southern Copper leverage massive balance sheets to optimize open-pit and subterranean assets. Specialized firms like Jiangxi Copper and Fortescue Metals focus heavily on technological differentiation and regional supply chain dominance.
Porter's Five Forces analysis of competitive pressures
Bargaining power of buyers remains moderate due to standardized commodity pricing, while supplier power is constrained by specialized equipment scarcity. Threat of substitutes is low for core structural metals, though environmental scrutiny elevates regulatory barriers for new entrants.
SWOT analysis of the global extraction sector
Strengths lie in vast mineral reserves and advanced extraction technologies; weaknesses involve high capital intensity and carbon footprints. Opportunities emerge from green energy mineral demand, whereas threats stem from geopolitical trade frictions and tightening safety regulations.
Value chain analysis from raw materials to end-users
The value flow initiates with geological exploration and drilling services, progresses through ore extraction and beneficiation, and culminates in refined metal supply for manufacturing. Independent contractors and equipment lessors play vital operational roles at the extraction and processing nodes.
Investment insights and high-potential areas
High-potential capital allocation targets automated drilling services, nickel and copper mining operations, and proprietary decarbonization technologies. Investors should prioritize asset owners with diversified portfolios and robust ESG compliance frameworks to mitigate regulatory exposure.
Conclusion and strategic takeaways
The Mining Market presents compelling growth prospects, anchored by a projected valuation of 3744.79 Billion by 2033. Success in this landscape requires rigorous operational efficiency, proactive environmental management, and strategic investments in specialized metal ore extraction.
Research methodology and data triangulation
Our findings are synthesized by triangulating primary stakeholder interviews with mining executives, trade registry datasets, and macroeconomic industrial indicators. Baseline estimates are continuously cross-verified against corporate financial disclosures and regional production metrics to ensure absolute accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics across 2026 baseline metrics and forecasts out to 2033. Analysis encompasses all primary extraction categories, support services, and regional jurisdictions, though specific localized artisanal mining data is excluded from macro aggregates.
Recent developments in the Mining Market
Recent industry momentum highlights strategic joint ventures in battery-grade nickel and decarbonization pacts among major miners like Rio Tinto and Glencore. Furthermore, increased M&A activity in copper-focused operations underscores the relentless race to secure future-facing transition assets.