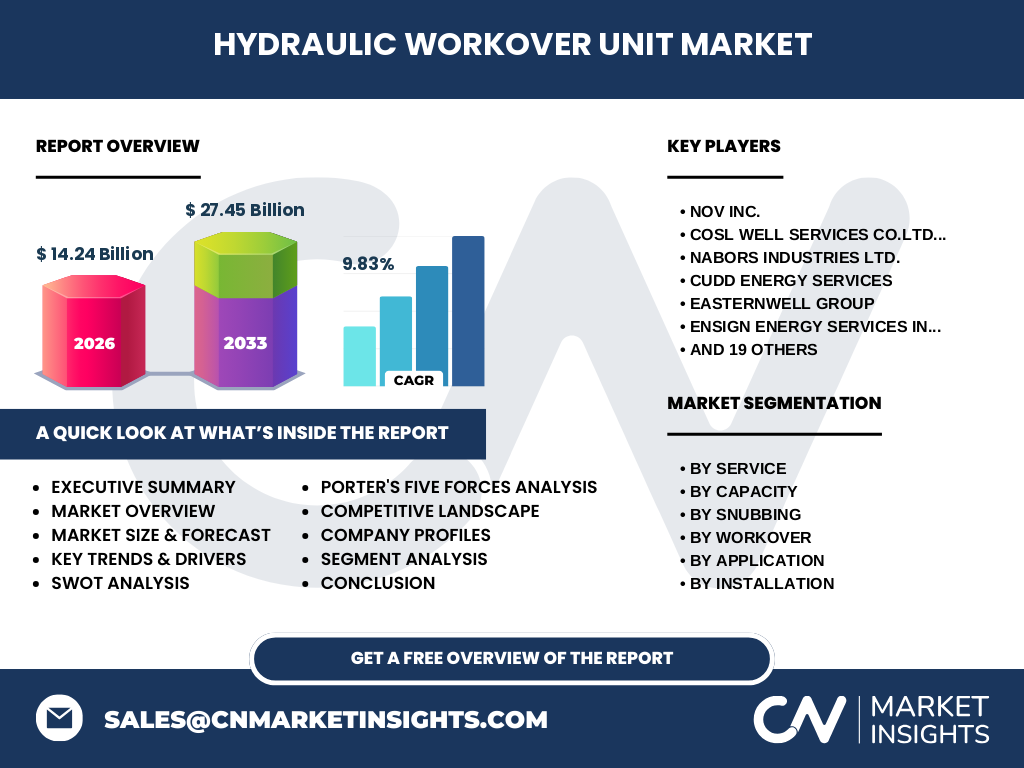
What is the market overview and industry significance of the Hydraulic Workover Unit Market?
Our analysis indicates that the Hydraulic Workover Unit Market is valued at $14.24 Billion in 2026, serving as a critical pillar for mature field intervention. These systems utilize specialized hydraulic jacks to handle tubing strings without killing the well, minimizing formation damage. Industry significance centers on cost-effective well servicing, bypassing the high day-rates of traditional heavy rigs.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Hydraulic Workover Unit Market?
The market is propelled by a massive global inventory of aging brownfields requiring artificial lift installations. However, supply chain bottlenecks for high-grade alloy steels and strict API compliance standards act as persistent restraints. Growth opportunities lie in deploying automated snubbing units to reduce crew exposure on high-pressure offshore platforms.
Emerging trends and growth patterns in the Hydraulic Workover Unit Market
The sector is witnessing a definitive pivot toward automated rigless intervention technologies that significantly reduce non-productive time. Operators are increasingly adopting specialized 0-50 Tons capacity units for lightweight onshore interventions, optimizing operational footprints in environmentally sensitive acreage.
COVID-19 impact analysis and recovery trajectory for the Hydraulic Workover Unit Market
The pandemic caused severe capital expenditure contractions, forcing delayed well intervention campaigns across major basins. Recovery has been robustly led by post-pandemic energy security demands, driving a rapid rebound in utilization rates for skid-mounted and trailer-mounted assets alike.
Competitive benchmarking and strategic dynamics in the Hydraulic Workover Unit Market
Market concentration is moderately high, with tier-one contractors dominating complex deepwater operations. Industry leaders like NOV Inc. and Nabors Industries Ltd. leverage proprietary manufacturing and global logistics networks, while regional players compete on localized agility and asset customization.
Executive summary of key findings for the Hydraulic Workover Unit Market
Our research projects the market to expand from $14.24 Billion in 2026 to $27.45 Billion by 2033, achieving a stellar CAGR of 9.83%. This acceleration is underpinned by brownfield maturation and a heightened global focus on well integrity mandated by agencies like BSEE.
Market forecast trajectory from 2027 to 2033
Driven by sustained crude pricing and aggressive infill drilling programs, the market will nearly double over the forecast period. We project cumulative revenues to surge toward the $27.45 Billion mark by 2033, maintaining a strong 9.83% CAGR trajectory.
Comprehensive segmentation analysis of the Hydraulic Workover Unit Market
Segmentation spans service types including workover and snubbing, capacity ranges from 0-50 Tons to Above 150 Tons, and application tiers covering Onshore and Offshore environments. Each segment addresses specific pressure regimes, with offshore platforms favoring robust skid-mounted configurations for optimal weight distribution.
Geographic distribution and regional performance in the Hydraulic Workover Unit Market
Regional performance diverges sharply based on brownfield maturity and regulatory intensity. North America dominates onshore activity via intensive Permian Basin interventions, whereas the Middle East and Asia-Pacific regions drive offshore demand, leveraging major maritime hubs to service expansive offshore platforms.
In-depth regional review of high-growth Hydraulic Workover Unit Market territories
North America remains the revenue anchor due to mature shale plays requiring aggressive artificial lift retrofits. Meanwhile, Asia-Pacific exhibits the fastest incremental growth, powered by national oil company investments in mature offshore fields across Southeast Asia and the South China Sea.
Company profiles and strategic positioning of leading industry participants
Industry titans such as Cudd Energy Services, Precision Drilling Corporation, and Superior Energy Services Inc. anchor their strategies in technological differentiation and geographic diversification. These firms actively integrate digital monitoring systems into their heavy-duty snubbing fleets to secure long-term service contracts.
Porter's Five Forces analysis of the Hydraulic Workover Unit Market
Bargaining power of buyers is moderate to high due to intense competition among oilfield service providers. Threat of substitutes remains low because conventional rigs cannot match the operational efficiency and cost-savings of specialized hydraulic workover and snubbing spreads.
SWOT analysis framework for the Hydraulic Workover Unit Market
Key strengths include unmatched operational safety in live-well environments, while weaknesses stem from high initial capital expenditure requirements. Significant opportunities emerge in digital automation integration, contrasted against threats from macroeconomic commodity price volatility.
Value chain analysis from raw materials to end-users
The value chain initiates with alloy steel and hydraulic component manufacturers, progressing to OEMs like NOV Inc. who fabricate the units. Service providers then deploy these assets for upstream exploration and production operators to maximize hydrocarbon recovery from aging wells.
Strategic investment insights and high-potential areas
Investors should prioritize companies deploying automated, high-capacity snubbing units (Above 150 Tons) capable of handling complex high-pressure, high-temperature (HPHT) offshore wells. These high-spec assets command premium day-rates and insulate service providers from commoditized onshore price wars.
Conclusion and core takeaways for stakeholders
The Hydraulic Workover Unit Market represents a high-growth sector set to reach $27.45 Billion by 2033. Stakeholders must embrace digital transformation and modular equipment designs to capture market share in an increasingly safety-conscious and efficiency-driven energy landscape.
Research methodology applied in compiling this market assessment
Our baseline estimates are rigorously triangulated by combining custom trade registry data, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators from agencies like the EIA and OPEC, ensuring robust and defensible market sizing.
Scope of the report, coverage parameters, and analytical limitations
This report covers global deployment of hydraulic workover and snubbing units across onshore and offshore installations from 2026 through 2033. Limitations include potential unforeseen geopolitical disruptions impacting regional rig deployment schedules and raw material supply chains.
Recent developments, corporate announcements, and strategic alliances
Recent industry momentum highlights aggressive fleet upgrades by major players like Archer Limited and Velesto Energy Berhad. Companies are increasingly forging technological partnerships to integrate remote telemetry and automated pipe-handling systems into their core service offerings.