What is the scope and industry significance of the Drilling Data Management Systems Market?
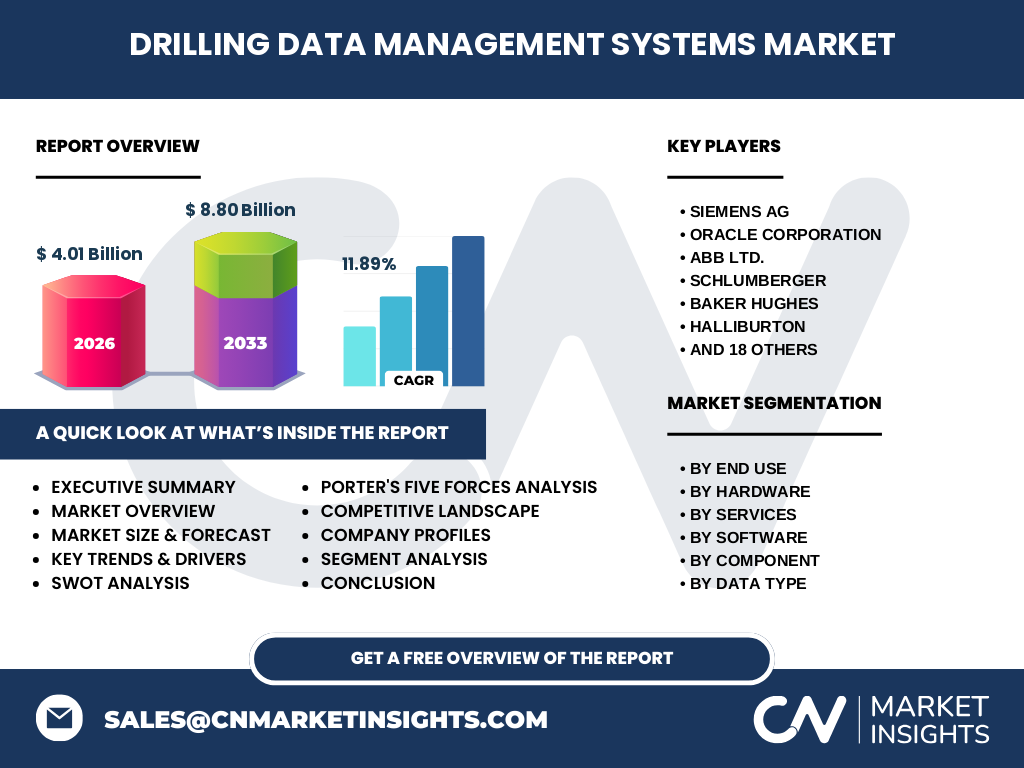
Our analysis indicates that the Drilling Data Management Systems Market is valued at $4.01 Billion in 2026, serving as the foundational digital infrastructure for modern subsurface operations. By integrating real-time data and advanced storage devices, this sector underpins critical asset monitoring across petroleum and geothermal energy extraction worldwide.
Structural Growth Drivers and Market Restraints
The market is propelled by a CAGR of 11.89%, driven by intense demands for drilling optimization and real-time data tracking in complex offshore blocks. Conversely, strict data sovereignty regulations and high deployment costs for hybrid and on-premises storage systems act as primary restraints limiting rapid technology adoption.
The Shift Toward Cloud-Native Architectures and Emerging Trends
Industry trends reveal a massive migration toward cloud-based data analytics software and edge sensor integration. Organizations increasingly leverage solutions from innovators like Cognite AS and Quorum Software to break down data silos, enabling automated remote decision-making across high-stakes exploration and production sites.
COVID-19 Impact Analysis and Market Recovery
The pandemic caused unprecedented capital expenditure cuts, temporarily stalling hardware deployments and sensor installations. However, our research shows a robust recovery trajectory as operators accelerate remote-operations workflows, relying heavily on automated maintenance and support services to maintain operational continuity during supply chain disruptions.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a mix of oilfield services giants and specialized software firms. Market leaders such as Schlumberger, Halliburton, and Baker Hughes leverage integrated service portfolios, while pure-play tech specialists like Peloton Computer Enterprises and Pason Systems focus on agile, specialized visualization software.
Executive Summary of the Drilling Data Management Systems Market
Driven by a projected expansion to $8.80 Billion by 2033, the Drilling Data Management Systems Market is undergoing rapid transformation. Data integration software and cloud platforms are critical value creators, helping operators reduce non-productive time and maximize asset returns in volatile commodity environments.
Long-Term Market Forecast from 2027 to 2033
Our forecast models project accelerated expansion from 2027 through 2033, scaling the market from its 2026 baseline to $8.80 Billion by 2033 at an impressive 11.89% CAGR. This growth is underpinned by escalating deepwater drilling complexities and automated performance monitoring requirements.
Segmentation Analysis Across Hardware, Software, and Services
The market is segmented by components including hardware, software, and services, alongside data types and deployment models. Data analytics software and cloud deployments dominate value capture, while sensors and communication devices form the critical physical backbone for real-time tracking.
Geographic Distribution and Regional Market Performance
Regional performance varies significantly based on upstream capital expenditure and regulatory stringency. North America leads in adoption due to mature shale plays, whereas the Middle East and Asia-Pacific show rapid growth driven by complex offshore projects and heavy investments in geothermal and energy drilling.
In-Depth Regional Review of Key Markets
North America commands the largest share of the Drilling Data Management Systems Market, fueled by intense Permian Basin activity and demand for historical data modeling. Meanwhile, offshore basins in Europe and Latin America prioritize real-time sensor data architectures to comply with stringent environmental bodies.
Company Profiles and Strategic Positioning
Key market participants occupy distinct strategic niches. Corporations like Siemens AG, ABB Ltd., and Emerson Electric Co. provide robust hardware and automation controls, whereas software leaders like AVEVA Group plc and Aspen Technology Inc. deliver sophisticated visualization and optimization analytics.
Porter's Five Forces Competitive Assessment
Industry rivalry is intense, shaped by high switching costs for proprietary database architectures and moderate threat of substitutes. Supplier power remains balanced, but high buyer power among major energy conglomerates pressures vendors to continuously innovate their data integration software offerings.
SWOT Analysis of the Drilling Data Management Systems Sector
Strengths lie in advanced predictive analytics and robust real-time monitoring capabilities. Weaknesses include high integration friction with legacy rigs. Opportunities abound in geothermal expansion, while cybersecurity vulnerabilities and fluctuating oil prices remain notable strategic threats.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw silicon and specialized sensor component manufacturers to hardware assemblers, software developers, and system integrators. Installation and integration services act as the vital bridge ensuring seamless data flow from remote drills to corporate decision-makers.
Investment Insights and High-Potential Growth Areas
Investors should target providers specializing in hybrid cloud-data solutions and automated compliance reporting tools. Companies offering seamless interoperability between legacy hardware and modern analytics software present the highest risk-adjusted return potential across the forecast period.
Conclusion and Strategic Takeaways
The Drilling Data Management Systems Market represents a high-growth frontier within industrial digital transformation. Reaching $8.80 Billion by 2033, success in this sector hinges on proprietary software agility, robust cloud infrastructure, and deep domain expertise in subsurface operations.
Rigorous Research Methodology and Data Triangulation
Our baseline estimates are built by triangulating primary stakeholder interviews with C-level executives, secondary macroeconomic data, regulatory filings from bodies like the SEC, and trade registry statistics. This rigorous validation ensures high-fidelity market sizing and accurate CAGR projections.
Scope of the Report and Analytical Limitations
This report covers global revenue streams across hardware, software, and services from 2026 to 2033. Limitations include unforeseen geopolitical shifts impacting cross-border software deployments and rapid technological obsolescence inherent in sensor and instrumentation data hardware markets.
Recent Industry Developments and Strategic Partnerships
Recent market dynamism is marked by strategic alliances between cloud hyperscalers and oilfield tech providers, such as collaborations involving Katalyst Data Management and TGS-NOPEC Geophysical Company. These partnerships aim to deploy scalable AI-driven visualization software for complex offshore drilling optimization.