What is the scope and industry significance of the Lead Market?
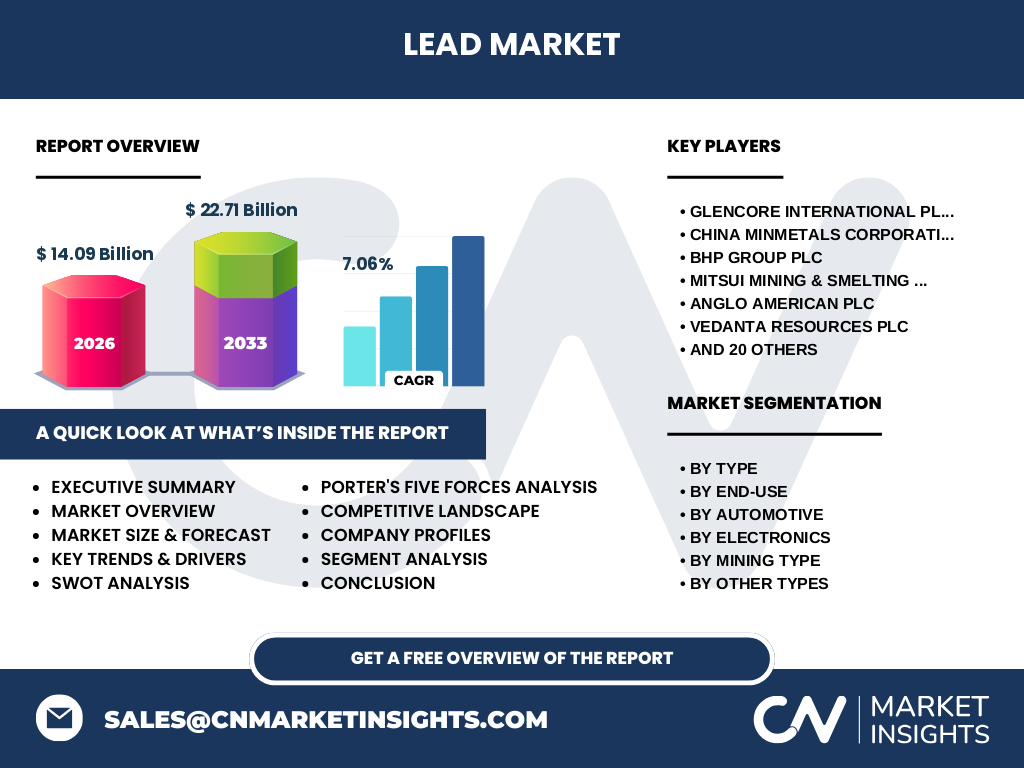
Our analysis indicates the Lead Market is valued at 14.09 Billion in 2026, serving as a critical foundation for global industrial infrastructure. The sector encompasses heavy-duty manufacturing applications, underpinning critical supply chains from energy storage to heavy construction across international trade hubs.
Key market drivers, restraints, challenges, and opportunities shaping Lead Market
The sector is propelled by surging demand for energy storage and advanced metallurgical alloys. However, stringent environmental mandates from regulatory bodies like the EPA constrain traditional smelting operations. Growth opportunities lie in optimizing underground and surface mining methodologies to secure raw material supply.
Emerging trends and growth patterns in Lead Market
The shift toward circular economy models is transforming the Lead Market industry trends, emphasizing secondary smelting and closed-loop recycling. Technological advancements in Lead-Based Semiconductors and radiation shielding materials are creating high-value niches away from traditional heavy industry reliance.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted global logistics, shutting down key smelting facilities and crippling mining output across major deposits. Recovery has been driven by aggressive fiscal stimulus directed toward grid infrastructure and automotive manufacturing revival, pushing market valuations upward toward forecasted targets.
Competitive Benchmarking and Market Concentration
Market concentration remains moderately consolidated among Tier-1 multinational miners and refiners. Industry leaders leverage vertical integration to dominate raw material extraction and secondary processing, effectively squeezing smaller regional operators facing escalating environmental compliance costs.
Executive Summary: High-Level Synthesis of Key Findings
Our comprehensive Lead Market analysis reveals a robust expansion path, projecting the market to reach 22.71 Billion by 2033 at a 7.06% CAGR from 2026. Strategic capital allocation toward sustainable recycling and advanced alloy production will dictate future market winners.
Market forecast from 2027 to 2033
Driven by accelerating demand in energy storage and infrastructural renewal, the sector will expand from 14.09 Billion in 2026 to 22.71 Billion by 2033. This consistent trajectory represents a steady 7.06% CAGR, outperforming historical baseline growth rates.
Segmentation analysis across primary categories
The ecosystem breaks down distinctly across key verticals:
- By Type: Automotive, Electronics, Other Types
- By End-Use: Batteries, Construction, Ammunition, Chemical Industry, Other End-Uses
- By Automotive: Lead-Acid Batteries, Lead Alloys, Lead Solder
- By Electronics: Lead Soldering Materials, Lead-Based Semiconductors, Lead-Acid Batteries For Electronics
- By Mining Type: Underground Mining, Surface Mining
- By Other Types: Lead-Based Pigments, Radiation Shielding Materials, Lead Pipes And Fittings, Lead Glass And Crystal Products
Regional market analysis and geographic performance
Geographic performance is heavily anchored by industrial output in Asia-Pacific, North America, and Europe. Regional divergence is dictated by localized environmental regulations, recycling infrastructure maturity, and the concentration of secondary smelting operations feeding local automotive manufacturing complexes.
In-depth regional review of key markets
Asia-Pacific dominates consumption and production, driven by massive domestic manufacturing hubs in China and India. Meanwhile, North American and European markets prioritize strict environmental compliance, focusing investments heavily on advanced recycling technologies and high-purity specialized alloy production.
Company profiles and strategic positioning
Industry titans like Glencore International plc, BHP Group plc, and China Minmetals Corporation leverage massive asset portfolios to control global supply. Specialty players such as Korea Zinc Co. Ltd. and Hindustan Zinc Ltd. focus on high-efficiency extraction and proprietary refining techniques.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to the dominance of large-scale mining conglomerates. Threat of substitutes is low in high-reliability energy storage applications, while competitive rivalry is intense among established refiners vying for limited high-grade ore deposits.
SWOT analysis of the sector
Key strengths include established recycling networks and unmatched energy storage reliability. Weaknesses center on heavy environmental liabilities. Opportunities exist in high-purity electronics applications, while strict regulatory threats pose continuous operational hurdles for traditional smelters.
Value chain analysis from raw materials to end-users
The value chain initiates with surface and underground mining operations managed by firms like Anglo American plc and Teck Resources Ltd. Raw ores flow through smelting and refining by processors like Nyrstar NV and Grupo Mexico S.A.B. de C.V. before reaching battery and construction end-users.
Investment insights and high-potential areas
Investors should target closed-loop recycling facilities and advanced secondary smelting technologies. Capital deployed into high-purity Lead Solder and specialized radiation shielding manufacturing yields superior risk-adjusted returns amidst tightening regulatory frameworks.
Conclusion and key takeaways for stakeholders
The Lead Market market size expansion to 22.71 Billion highlights enduring industrial demand. Success requires pivoting toward sustainable processing, technological innovation in electronics, and rigorous supply chain risk management across all operational tiers.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by synthesizing customs trade registry data, primary stakeholder interviews with C-suite executives across mining firms like First Quantum Minerals Ltd., and secondary macroeconomic indicators regarding global industrial output.
Scope of the report and coverage parameters
This report covers global production, consumption, and trade flows across all major end-use segments from 2026 to 2033. Limitations include potential data lag in informal recycling sectors and unpredictable shifts in regional trade tariffs.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights strategic joint ventures in sustainable smelting technology by firms like Yuguang Gold and Lead Co. Ltd. and capacity expansions by Sumitomo Metal Mining Co. Ltd., signaling proactive adaptation to tightening global environmental standards.