What is the scope of the Reentry Rocket Systems Market?
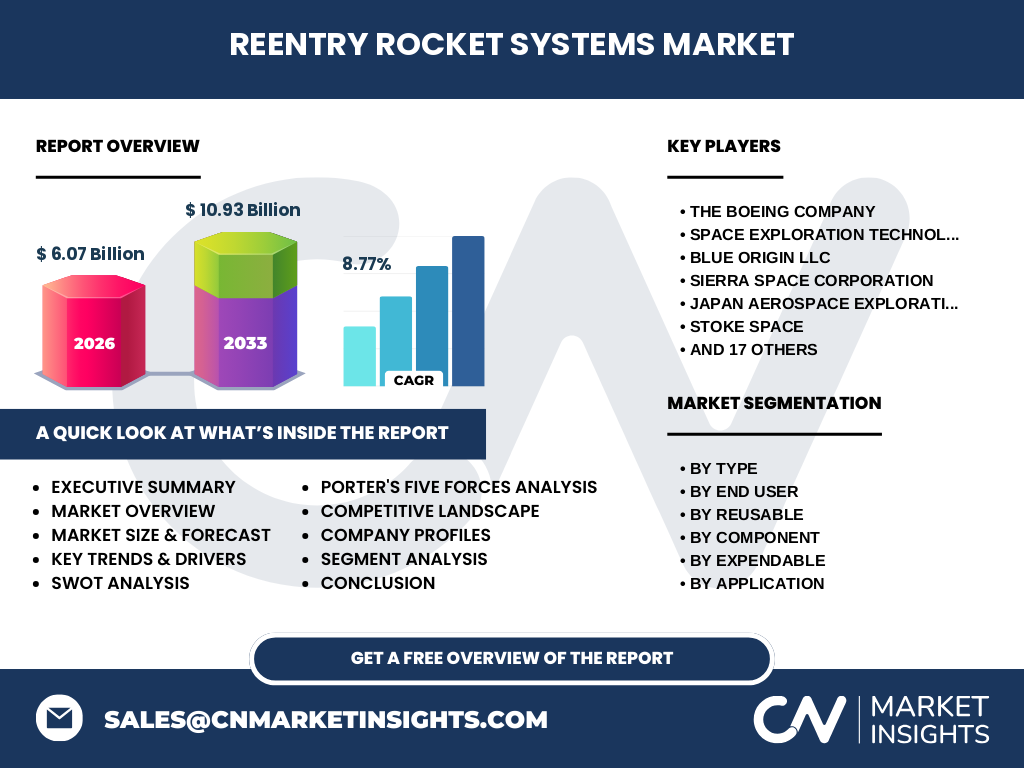
Our analysis indicates that the Reentry Rocket Systems Market encompasses specialized aerospace technologies designed to safely return payloads and launch vehicles from orbit. Valued at 6.07 Billion in 2026, this industry supports critical orbital logistics, cargo return, and defense operations. The sector bridges heavy-lift launch infrastructure with reusable thermal protection systems, serving space agencies, private operators, and research institutions worldwide.
Structural Growth Drivers and Market Restraints
The market is propelled by a surge in commercial satellite constellations and orbital manufacturing demands. Key growth drivers include the lowering cost-per-pound to orbit through reusability innovations by pioneers like Space Exploration Technologies Corp. and Blue Origin LLC. Conversely, severe regulatory hurdles from the FAA and stringent export controls on high-temperature carbon-composite materials act as primary market restraints, alongside immense capital expenditure requirements.
Emerging Industry Trends in Reentry Rocket Systems
Industry trends highlight a definitive pivot toward fully autonomous landing mechanisms and advanced ceramic matrix composites. Based on our research, emerging players like Stoke Space and Varda Space Industries Inc. are pioneering miniaturized capsule architectures. These innovations drastically reduce aerodynamic drag during atmospheric entry, fundamentally altering how microgravity manufacturing products are recovered safely on land or at sea.
Evaluating the COVID-19 Impact and Recovery Trajectory
The pandemic caused severe supply chain disruptions for aerospace-grade titanium and ablative resins, temporarily stalling prototype testing. However, our data suggests the crisis accelerated digital engineering workflows and simulation-driven design. The post-pandemic recovery trajectory has been exceptionally robust, fueled by emergency defense appropriations and a surge in venture capital funding targeting commercial in-space infrastructure and rapid point-to-point transportation.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains moderately high, dominated by established defense primes and agile NewSpace entrants. Competitive benchmarking shows The Boeing Company and Sierra Space Corporation leveraging decades of legacy capsule expertise, while disruptors like Radian Aerospace and Pangea Aerospace introduce novel propulsion concepts. Strategic positioning relies heavily on securing proprietary launch manifests and forging lucrative partnerships with commercial space station developers.
Executive Summary of the Reentry Rocket Systems Market
This comprehensive executive overview reveals a thriving sector poised for exponential expansion. Driven by the commercialization of low Earth orbit, the Reentry Rocket Systems Market market size is projected to scale remarkably, underpinning the future of global space commerce, national defense readiness, and rapid global logistics networks.
Market Forecast and Growth Projections (2027-2033)
Our long-term forecast demonstrates exceptional momentum for the sector. The data projects the market to expand from its 2026 baseline to reach 10.93 Billion by 2033, expanding at a robust 8.77% CAGR. This growth trajectory reflects surging demand for reusable flight hardware and orbital return capabilities across both commercial and defense verticals.
Segmentation Analysis of Launch and Recovery Systems
Segmentation is categorized by type into Reusable and Expendable systems. Reusable systems encompass refurbishable boosters, reusable fairings, landing legs, and heat shields, while expendable configurations utilize single-use boosters and ablative heat shields. End-user segments span space agencies, private enterprises, and defense organizations, each requiring tailored thermal protection and propulsion avionics.
Geographic Distribution and Regional Performance
Geographic performance is heavily concentrated in North America, anchored by established launch infrastructure and extensive Department of Defense contracting. Meanwhile, the Asia-Pacific region, spearheaded by the Japan Aerospace Exploration Agency and emerging local startups like ElevationSpace, exhibits the fastest relative growth, driven by aggressive national space exploration roadmaps and localized manufacturing incentives.
In-Depth Regional Review of Key Markets
North America commands the lion's share of industry revenue, benefiting from deep-pocketed private space companies and dedicated test ranges like Cape Canaveral and White Sands. In Europe, specialized firms such as The Exploration Company GmbH and Atmos Space Cargo GmbH are capitalizing on European Space Agency initiatives to secure regional supply chain independence in cargo return solutions.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct competitive moats. Space Exploration Technologies Corp. dominates heavy booster reuse, whereas Blue Origin LLC focuses on vertical landing precision. Innovative upstarts like Hypersonix Launch Systems and Exos Aerospace Systems & Technologies Inc. carve out niches in hypersonic flight testing and suborbital research, respectively, optimizing their portfolios for specific payload recovery thresholds.
Porter's Five Forces Analysis
An assessment of Porter's forces indicates moderate-to-high barriers to entry due to extreme capital intensity and strict regulatory certification processes. Supplier power remains concentrated among specialized refractory metal and composite fabricators. Meanwhile, competitive rivalry is intensifying rapidly as venture-backed startups challenge legacy defense contractors for commercial cargo and defense transport contracts.
SWOT Analysis of the Reentry Rocket Systems Industry
Strengths include advanced thermal protection materials and proven vertical landing engineering. Weaknesses involve high initial capital outlays and complex recovery logistics. Opportunities lie in emerging in-space manufacturing and rapid military logistics. Threats center on stringent environmental regulations for atmospheric reentry debris and potential geopolitical launch restrictions.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing carbon-carbon composites, nickel alloys, and ablative polymers. These feed into component manufacturers producing propulsion systems, avionics, and thermal protection shields. System integrators then assemble the vehicles for operators who deliver finished launch and recovery services to end-users like defense organizations and scientific researchers.
Investment Insights and High-Potential Areas
Investors should direct capital toward firms specializing in advanced thermal protection systems and automated recovery avionics, as these represent critical technological bottlenecks. Companies developing low-cost, rapidly refurbishable boosters—such as Stoke Space and Pangea Aerospace—offer exceptional upside potential as commercial demand for frequent orbital return missions accelerates.
Conclusion and Key Takeaways
In summary, the Reentry Rocket Systems Market industry trends point toward a permanent shift from expendable hardware to highly sustainable, reusable architectures. With a projected valuation of 10.93 Billion by 2033, stakeholders must prioritize technological agility, regulatory compliance, and strategic supply chain partnerships to capture long-term market share.
Research Methodology for Baseline Estimates
Our baseline estimates are rigorously triangulated using a multi-tiered methodology. We combine proprietary trade registry data, primary stakeholder interviews with aerospace chief technology officers, and secondary macroeconomic indicators from global space agencies. This ensures our Reentry Rocket Systems Market analysis delivers institutional-grade accuracy and reliable forecasts.
Scope of the Report and Coverage Parameters
This report covers global deployment dynamics, component manufacturing ecosystems, and regulatory frameworks influencing orbital return technologies from 2026 through 2033. Limitations include restricted access to classified military payload specifications and proprietary cost structures of privately held NewSpace enterprises, which are modeled using secondary financial proxies.
Recent Developments and Strategic Industry Moves
Recent market activities feature aggressive joint ventures and flight test campaigns by companies like Intuitive Machines, Inversion Space, and Outpost Space. Strategic partnerships between defense agencies and private cargo developers are accelerating the deployment of precision-guided re-entry vehicles, validating the commercial viability of rapid orbital return systems.