Market overview — definition, scope, and industry significance of Golf Club Market
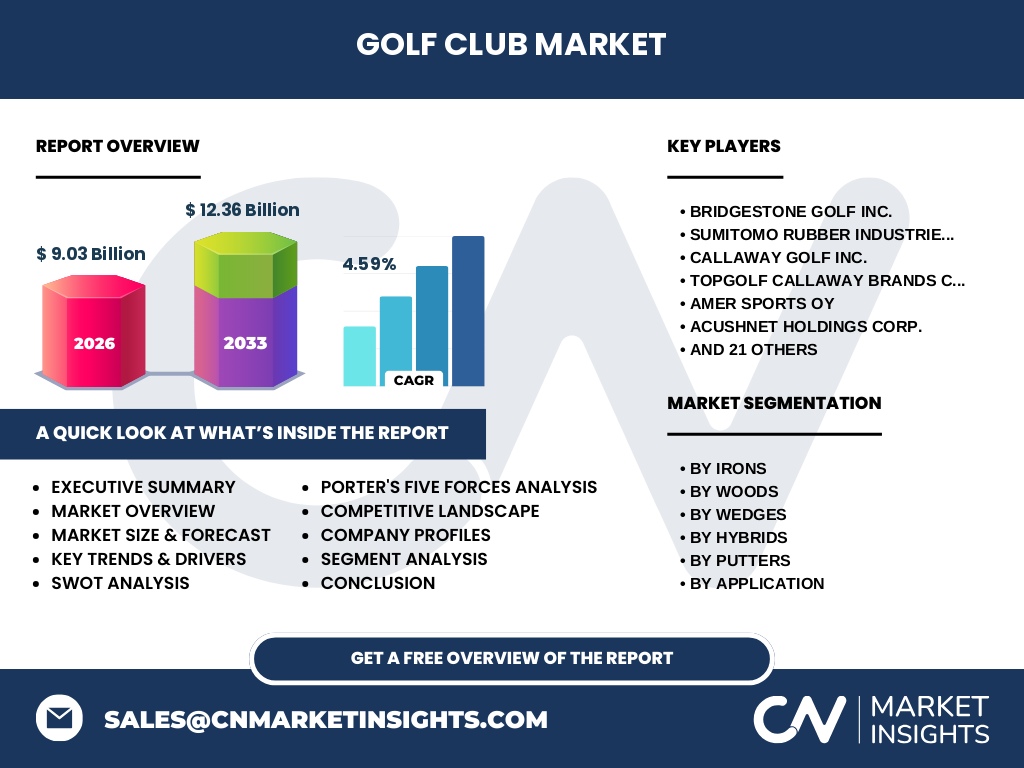
Our analysis indicates the Golf Club Market reaches a valuation of 9.03 Billion in 2026. This sector encompasses precision-engineered hardware including woods, irons, wedges, hybrids, and putters designed for both leisure and professional applications. The industry significance lies in its complex integration of high-grade raw materials, proprietary aerodynamics, and stringent compliance with the United States Golf Association governing bodies.
Key market drivers, restraints, challenges, and opportunities shaping Golf Club Market
Growth is propelled by rising participation in leisure sports and technological innovations in custom fitting. However, supply chain bottlenecks for carbon fiber and titanium restrict output. Our research highlights that industry participants face severe logistical hurdles at major container ports, creating exciting opportunities for direct-to-consumer digital channels and localized manufacturing to capture surging consumer demand.
The Shift Toward Advanced Customization in Golf Club Market Industry Trends
Consumers increasingly demand bespoke equipment tailored via launch monitors and advanced fitting studios. This trend favors agile manufacturers like Parsons Xtreme Golf LLC and Miura Golf LP over legacy mass-producers. Data suggests that customization yields higher margins, transforming standard retail transactions into high-touch, consultative service experiences that drive long-term brand loyalty.
COVID-19 impact analysis — how the pandemic affected Golf Club Market and the recovery trajectory
The pandemic initially paralyzed global supply chains and closed retail storefronts, yet it paradoxically catalyzed a massive outdoor recreation boom. As social distancing favored socially distant outdoor sports, demand surged. Companies like Callaway Golf Inc. and Acushnet Holdings Corp. navigated logistical disruptions by pivoting aggressively toward online retail channels, securing a robust recovery trajectory heading toward 2027.
Competitive Benchmarking and Strategic Dynamics in Golf Club Market
The competitive landscape features intense rivalry among heavyweights like Topgolf Callaway Brands Corp., TaylorMade Golf Company Inc., and Ping Inc. Market concentration remains moderately high in premium segments, while boutique brands like Bettinardi Golf and Evnroll carve out lucrative niches in precision-milled putters. Strategic mergers and aggressive patent portfolios for clubhead aerodynamics define the primary battlegrounds for market share.
Executive summary — high-level synthesis of key findings about Golf Club Market
Valued at 9.03 Billion in 2026, the market is projected to expand to 12.36 Billion by 2033 at a CAGR of 4.59%. Driven by technological advancements in multi-material construction and expanding demographics in leisure play, the sector offers compelling opportunities. Premium pricing tiers and specialized fitting channels remain the primary catalysts for sustainable revenue generation.
Market forecast — projected growth from 2027 to 2033
Our projections indicate steady expansion, scaling the market from its 2026 baseline to 12.36 Billion by 2033, achieving a steady 4.59% CAGR. This trajectory reflects sustained consumer interest, accelerated replacement cycles for technological upgrades, and the rising popularity of golf across emerging geographic regions and diverse demographic groups.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation spans multiple vectors: Product Types include woods, hybrids, irons, wedges, and putters; Hand Orientation covers left-hand and right-hand clubs; Price Ranges divide into premium and economy tiers; and Distribution Channels encompass specialty stores and online retail. Each segment serves distinct consumer cohorts, from beginner leisure participants to elite professionals.
Regional market analysis — geographic distribution and performance across regions
Geographic performance is heavily anchored by North America, followed by strong adoption across Europe and the Asia-Pacific region. Regional dynamics are influenced by course density, disposable income levels, and local climate conditions. Our analysis shows that urbanizing markets in Asia present the fastest-growing frontier, driven by rising corporate wealth and new course developments.
In-depth regional review — detailed examination of key regional markets
North America dominates consumption due to a mature infrastructure of private and public courses. Meanwhile, the Asia-Pacific region—anchored by key markets in Japan and South Korea—demonstrates extraordinary appetite for ultra-premium forged irons and specialized wedges produced by brands like Honma Golf Ltd. and Fourteen Golf.
Company profiles — strategic positioning of leading companies in Golf Club Market
Industry leaders maintain distinct competitive moats. Sumitomo Rubber Industries Ltd. and its subsidiary Srixon Ltd. focus on advanced ball-and-club integration, while U.S. Kids Golf LLC dominates youth-specific equipment. Premium entities like Ben Hogan Golf Equipment Company and Vega Golf leverage heritage craftsmanship to capture purist segments.
Porter's Five Forces analysis of Golf Club Market
Supplier power remains moderate due to the specialized sourcing of aerospace-grade titanium and carbon composites. Buyer power is high given extensive online review ecosystems. Threat of substitutes is low, but competitive rivalry is fierce, forcing incumbents like Cobra Golf Inc. and Cleveland Golf Company Inc. to continuously innovate.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Strengths include strong brand equity and proprietary metallurgical innovations. Weaknesses involve high research and development overheads and supply chain fragility. Opportunities lie in digital custom-fitting tools and direct-to-consumer platforms. Threats encompass economic downturns impacting discretionary leisure spending and counterfeit manufacturing.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain initiates with raw material sourcing of steel, graphite, and titanium. Manufacturing hubs in Asia process these materials into clubheads and shafts before assembly. Distribution flows through specialty golf shops, e-commerce platforms, and green-grass pro shops, ultimately reaching the end-user seeking optimized performance.
Investment insights — strategic recommendations and high-potential areas
Investors should target brands exhibiting strong proprietary fitting technology and agile direct-to-consumer supply chains. Strategic focus on the premium putter segment, populated by innovators like Piretti Golf Inc. and Sub 70 Golf Ltd., offers exceptional margin stability and resilient consumer demand.
Conclusion and key takeaways
The market demonstrates robust health, advancing toward 12.36 Billion by 2033. Success in this landscape requires balancing technological innovation with responsive omnichannel distribution, ensuring brands can capture both traditionalists and digitally native consumers.
Research methodology — detail how baseline estimates are triangulated
Our research methodology combines exhaustive primary stakeholder interviews with C-suite executives, rigorous trade registry data analysis, and secondary macroeconomic indicators. Baseline 2026 estimates of 9.03 Billion are triangulated using customs shipping logs, point-of-sale data, and expert consensus panels.
Scope of the report — coverage parameters and limitations
This report covers global developments in the Golf Club Market from 2027 to 2033, evaluating specific product categories, regional performances, and distribution channels. Limitations include unforeseen macroeconomic shocks, sudden trade tariff adjustments, and rapid shifts in consumer discretionary spending patterns.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent industry momentum features aggressive product launches focusing on artificial intelligence-optimized clubface geometries and multi-material weighting. Strategic partnerships between equipment manufacturers and digital instruction platforms, alongside direct-to-consumer expansions by emerging brands, continue to redefine market accessibility and consumer engagement.