Market overview — definition, scope, and industry significance of Regulatory Information Management System Market
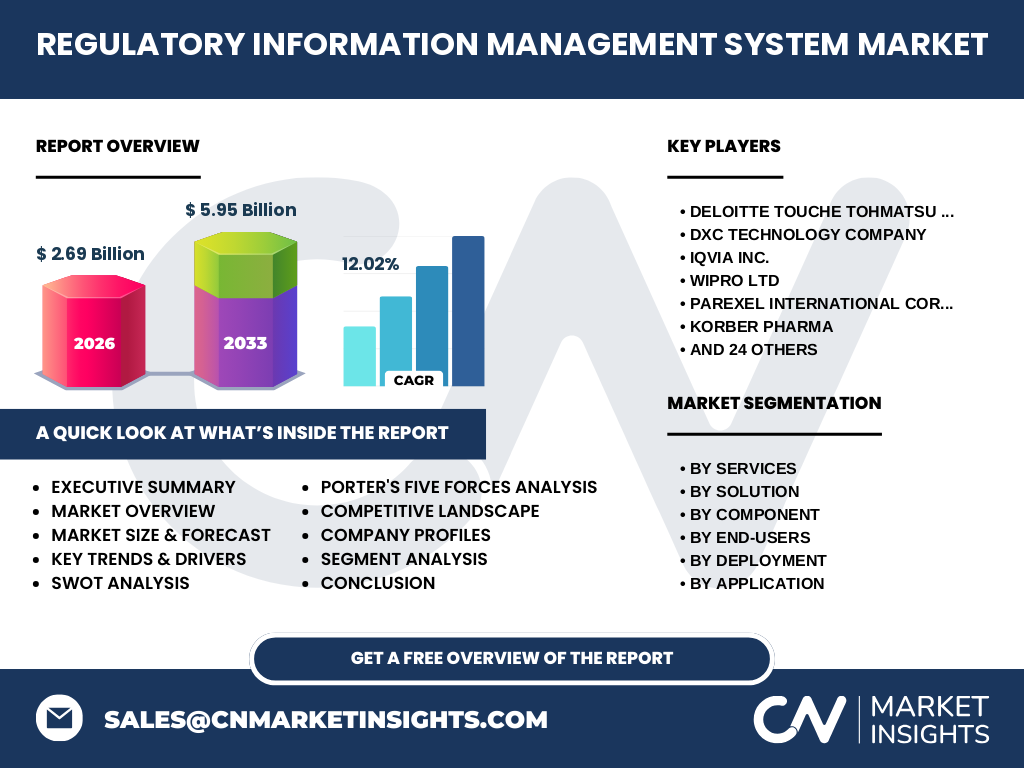
The Regulatory Information Management System Market is valued at $2.69 Billion in 2026, serving as the foundational digital architecture for managing medicinal product lifecycles. Our analysis indicates this industry handles complex global dossiers for the FDA, EMA, and PMDA, bridging critical compliance gaps across life sciences.
Key market drivers, restraints, challenges, and opportunities shaping Regulatory Information Management System Market
Strict mandates from the European Medicines Agency and FDA act as primary catalysts. However, high migration costs and legacy infrastructure pose notable restraints. Growth opportunities lie in automating submissions for personalized medicine and scaling global cloud adoption.
Emerging trends and growth patterns in Regulatory Information Management System Market
The industry trends toward AI-driven regulatory intelligence and unified cloud platforms. Vendors like Veeva Systems Inc and ArisGlobal LLC lead this charge, replacing fragmented point solutions with interconnected ecosystems that accelerate submission planning and tracking management.
COVID-19 impact analysis — how the pandemic affected Regulatory Information Management System Market and the recovery trajectory
The pandemic accelerated digital transformation, forcing life sciences organizations to abandon manual document management in favor of remote-access cloud systems. Post-COVID recovery shows sustained enterprise spending on compliance solutions to handle emergency vaccine authorizations efficiently.
Competitive landscape — major players, market concentration, and strategic dynamics
The market features intense competition among specialized life sciences software providers and major tech consultancies. Companies like IQVIA Inc., Parexel International Corporation, and DXC Technology Company leverage strategic partnerships and cloud-native acquisitions to capture enterprise market share.
Executive summary — high-level synthesis of key findings about Regulatory Information Management System Market
Driven by rising compliance complexity, the Regulatory Information Management System Market industry trends point to a robust expansion, scaling from $2.69 Billion in 2026 to $5.95 Billion by 2033 at a 12.02% CAGR.
Market forecast — projected growth from 2027 to 2033
Our research confirms the market will expand dynamically from 2027 through 2033, achieving a projected valuation of $5.95 Billion by 2033. This trajectory reflects a steady 12.02% CAGR fueled by expanding pharmaceutical pipelines and stringent medical device oversight.
Segmentation analysis — break down each segment category, explain what it covers and its market role
The market segments into Services (consulting, implementation, support, training), Solutions (compliance software, document management, analytics), Deployment (on-premise, cloud), Application (registration, labeling, publishing), and Enterprise Size (SMEs, large enterprises) across pharmaceutical and medical device sectors.
Regional market analysis — geographic distribution and performance across regions
North America dominates the landscape due to stringent FDA oversight and early technology adoption. Meanwhile, the Asia-Pacific region demonstrates the fastest growth rate, driven by expanding clinical trial hubs in India and localized regulatory reforms in Japan and China.
In-depth regional review — detailed examination of key regional markets
European markets prioritize GDPR-compliant cloud deployments and EMA IDMP standards. North America focuses on rapid cloud integration for decentralized clinical trials, while emerging economies leverage outsourced regulatory consulting services to streamline cross-border drug approvals.
Company profiles — strategic positioning of leading companies in Regulatory Information Management System Market
Industry leaders maintain distinct competitive moats. Veeva Systems Inc dominates with its Vault platform, LORENZ Life Sciences Group excels in electronic publishing, and MasterControl Solutions Inc. targets comprehensive quality and compliance automation.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate due to specialized technical talent scarcity. Buyer power is high among large pharma enterprises demanding customized compliance workflows, while threat of new entrants is mitigated by high validation hurdles and stringent data security mandates.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Key strengths include high customer retention and mission-critical utility. Weaknesses involve lengthy implementation cycles. Opportunities stem from emerging biotech startups, while threats include evolving cybersecurity regulations and proprietary software disruption.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain flows from foundational software development and R&D data input, through systems integration by firms like Wipro LTD and NNIT A/S, culminating in deployment for pharmaceutical and medical device end-users managing global regulatory dossiers.
Investment insights — strategic recommendations and high-potential areas
Investors should target cloud-native data management solutions and AI-powered regulatory intelligence tools. Companies offering seamless integration between labeling management and submission tracking represent prime acquisition targets for private equity.
Conclusion and key takeaways
The Regulatory Information Management System Market industry trends confirm that compliance is no longer a back-office function but a strategic growth driver. Reaching $5.95 Billion by 2033, the sector rewards vendors providing scalable, cloud-based automation.
Research methodology — detail how baseline estimates are triangulated (e.g., combining trade registry data, primary stakeholder interviews, and secondary macroeconomic indicators)
Our analysis triangulates baseline estimates by combining primary interviews with Chief Regulatory Officers, secondary macroeconomic indicators, and trade registry data from major life sciences hubs across North America, Europe, and Asia-Pacific.
Scope of the report — coverage parameters and limitations
This report covers global revenue streams, software licensing models, and professional services within the pharmaceutical and medical device sectors. Limitations exclude internal IT operational expenditures not directly tied to regulatory compliance software.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent market activity highlights aggressive M&A and AI integration. Firms such as Dot Compliance Ltd. and Rimsys Inc. have launched automated medical device classification tools, while Instem PLC expanded its global compliance footprint through strategic technological alliances.