What is the structural scope and market overview of the Gas To Liquid (GTL) Market?
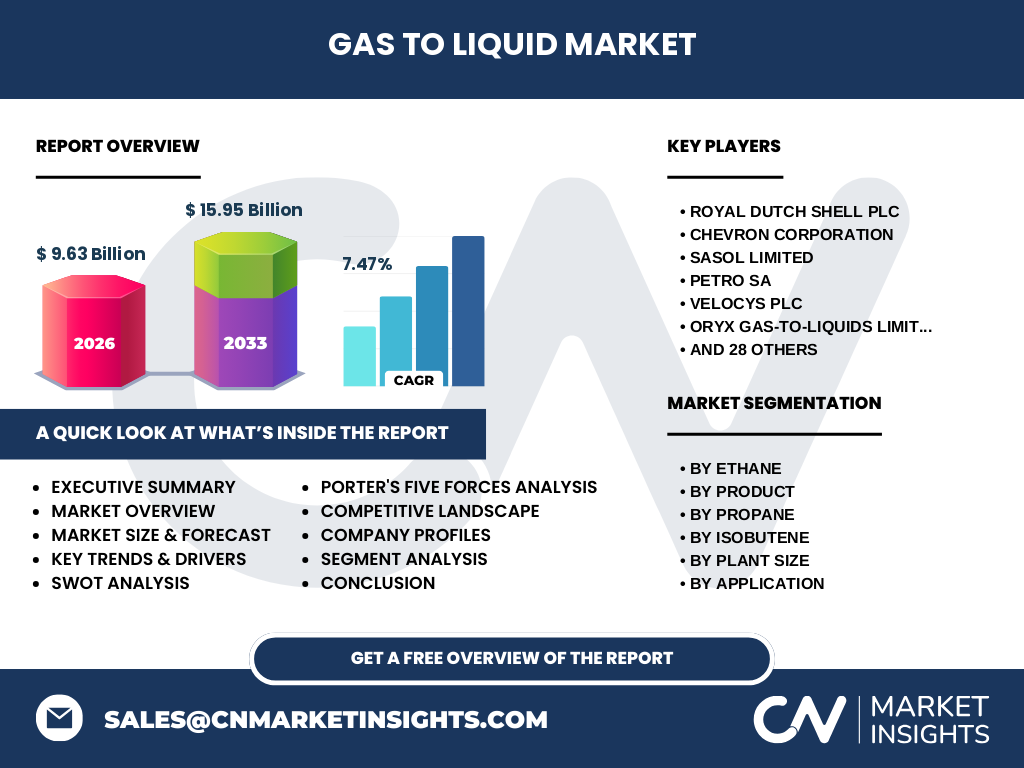
Our analysis indicates that the Gas To Liquid (GTL) Market represents a transformative chemical conversion sector converting stranded natural gas into high-value liquid hydrocarbons. Valued at 9.63 Billion in 2026, the industry is underpinned by proprietary Fischer-Tropsch (FT) and Methanol To Gasoline (MTG) processing technologies developed by innovators like Sasol Limited and Royal Dutch Shell PLC.
Structural Growth Drivers and Market Restraints
The Gas To Liquid (GTL) Market industry trends are heavily shaped by strict environmental regulations regarding flared associated gas, alongside stringent sulfur limits mandated by the International Maritime Organization (IMO). However, massive capital expenditure hurdles and complex catalyst degradation issues in large-scale plant operations serve as severe market restraints, stalling rapid deployment across developing regions.
Emerging Trends and Decarbonization Shifts
A defining trajectory within the Gas To Liquid (GTL) Market analysis is the pivot toward modular, micro-scale GTL units championed by pioneers like Velocys PLC and CompactGTL Limited. This technology enables monetization of remote onshore gas fields, bypassing costly pipeline infrastructure while aligning with global net-zero transition targets.
COVID-19 Impact Analysis and Macroeconomic Recovery
The pandemic caused severe supply chain disruptions and deferred final investment decisions (FID) for mega-projects spearheaded by QatarEnergy and Chevron Corporation. Nevertheless, post-pandemic energy security demands accelerated the recovery trajectory for the Gas To Liquid (GTL) Market market size, driven by surging global reliance on ultra-clean synthetic diesel and premium paraffinic waxes.
Competitive Landscape and Strategic Consolidation
The competitive ecosystem of the Gas To Liquid (GTL) Market exhibits high market concentration led by proprietary technology licensors such as Haldor Topsoe A/S, ExxonMobil Corporation, and Sasol Limited. Major energy conglomerates leverage exclusive catalyst portfolios and integrated upstream-to-downstream assets to maintain formidable entry barriers against new market entrants.
Executive Summary of Valuation Projections
Strategic synthesis of the Gas To Liquid (GTL) Market reveals a robust expansion trajectory, surging from 9.63 Billion in 2026 to reach 15.95 Billion by 2033. Propelled by a steady CAGR of 7.47%, this growth reflects accelerating commercialization of advanced syngas conversion methodologies worldwide.
Market Forecast Metrics from 2027 to 2033
Based on our research, the Gas To Liquid (GTL) Market is poised for sustained acceleration, scaling from its 2026 baseline of 9.63 Billion toward an anticipated valuation of 15.95 Billion by 2033. Maintaining a robust CAGR of 7.47%, this expansion highlights rising global demand for cleaner synthetic transportation fuels.
Segmentation Analysis of Processing Technologies and Products
The Gas To Liquid (GTL) Market segmentation spans Ethane (Petrochemical and Industrial Grade), Propane (Refrigeration and Commercial Grade), Isobutene (Polymer and Fuel Grade), Natural Gasoline (Light and Heavy), Plant Sizes, Applications (Fuel, Lubricating, and Process Oil), and Processing Technologies including Fischer-Tropsch (FT) and Methanol To Gasoline (MTG).
Regional Market Analysis and Geographic Distribution
Geographically, the Gas To Liquid (GTL) Market is heavily anchored by the Middle East and Africa, driven by abundant feedstock reserves managed by entities like QatarEnergy and The Nigerian National Petroleum Corporation Limited. Meanwhile, North American and European sectors focus on technological innovation, emissions compliance, and high-purity synthetic lubricants.
In-Depth Regional Review and Localized Constraints
In the Middle East, expansive reserves fuel mega-complexes managed by Oryx Gas-to-Liquids Limited and Oltin Yol GTL LLC, overcoming severe desert operating environments. Conversely, European markets face stringent carbon taxation frameworks, compelling operators like Equinor ASA and ENI S.p.A. to invest heavily in carbon capture integration.
Company Profiles and Strategic Positioning
Industry leaders like Royal Dutch Shell PLC, Sasol Limited, and Chevron Corporation dominate the Gas To Liquid (GTL) Market through patented FT synthesis expertise and massive capital deployment. Concurrently, specialized engineering firms such as TechnipFMC PLC, KBR Inc., and Black & Veatch Corp. provide essential EPC execution capabilities for complex plant constructions.
Porter's Five Forces Competitive Intensity Assessment
Our analysis indicates that supplier power remains moderate due to abundant natural gas reserves, while buyer power is constrained by specialized product specifications. However, threat of new entrants is remarkably low given the intensive capital requirements and proprietary intellectual property held by incumbents like Haldor Topsoe A/S and Air Liquide S.A.
SWOT Analysis of Industry Vulnerabilities and Upsides
Strengths of the Gas To Liquid (GTL) Market lie in ultra-clean product outputs, while weaknesses include astronomical capital expenditure. Opportunities abound in remote flare gas monetization, though geopolitical instability and tightening environmental mandates present persistent threats to long-term project viability.
Value Chain Analysis from Upstream Feedstock to End-Users
The value chain initiates with upstream natural gas extraction by firms like ConocoPhillips Company and TotalEnergies SE, transitioning through syngas generation and catalytic conversion technologies provided by Johnson Matthey PLC and Axens SA. Final distribution channels supply high-grade synthetic fuels and lubricating oils to commercial end-users.
Investment Insights and High-Potential Areas
High-potential investment avenues within the Gas To Liquid (GTL) Market concentrate on modular plant engineering and digital twin optimization software provided by Siemens AG and General Electric Company. Investors are advised to target partnerships that minimize capital risk while scaling micro-GTL infrastructure.
Conclusion and Strategic Key Takeaways
The trajectory of the Gas To Liquid (GTL) Market confirms its vital role in monetizing stranded hydrocarbon reserves. With a projected expansion to 15.95 Billion by 2033 at a 7.47% CAGR, early investment in modular processing technology remains paramount for sustained competitive advantage.
Research Methodology and Data Triangulation
Our proprietary methodology for the Gas To Liquid (GTL) Market combines rigorous bottom-up capacity modeling with exhaustive primary interviews across C-suite executives at Sasol Limited, Linde PLC, and Honeywell International Inc. This data is triangulated against official trade registry data and secondary macroeconomic indices.
Scope of the Report and Coverage Parameters
This comprehensive report evaluates the Gas To Liquid (GTL) Market across global geographies from 2027 to 2033, covering specified plant sizes, product categories, and processing technologies. Exclusions involve traditional petroleum refining sectors that do not utilize synthetic gas-to-liquid conversion pathways.
Recent Developments and Industry Partnerships
Recent strategic moves in the Gas To Liquid (GTL) Market highlight collaborative greenfield ventures and catalyst advancements by industry titans like Air Liquide S.A., Uhde GmbH, and Primus Green Energy Inc. These developments focus on enhancing thermal efficiency and reducing the carbon intensity of synthetic fuel production.